Germany's Residential Property Market Analysis 2026
Germany's housing recovery has run out of steam. House prices are barely rising in nominal terms and are falling once inflation is taken into account. The European Central Bank (ECB) has raised interest rates twice since June, mortgage rates have passed 4% for the first time since 2023, and new lending has stopped growing. Rents, by contrast, are still rising, because new construction remains far too low.
This extended overview from Global Property Guide covers key aspects of the German housing market and takes a closer look at its most recent developments and long-term trends.
Table of Contents
- Property Prices and Price Index
- Historic Perspective
- Property Supply and Demand Trends
- Rental Market: Rents and Rental Yields
- Mortgage Market and Interest Rates
- Economic and Social Factors
Property Prices and Price Index
In our May 2026 edition, the market was in a moderate, selective recovery. House prices had risen by 3.0% in the year to Q4 2025, the ECB had kept its rates on hold for almost a year, and analysts expected prices to rise by about 3% a year until 2028. Six months later, that picture has changed. Price growth has slowed to almost nothing, the ECB has raised its deposit rate from 2.00% to 2.50%, and mortgage rates have climbed above 4%.
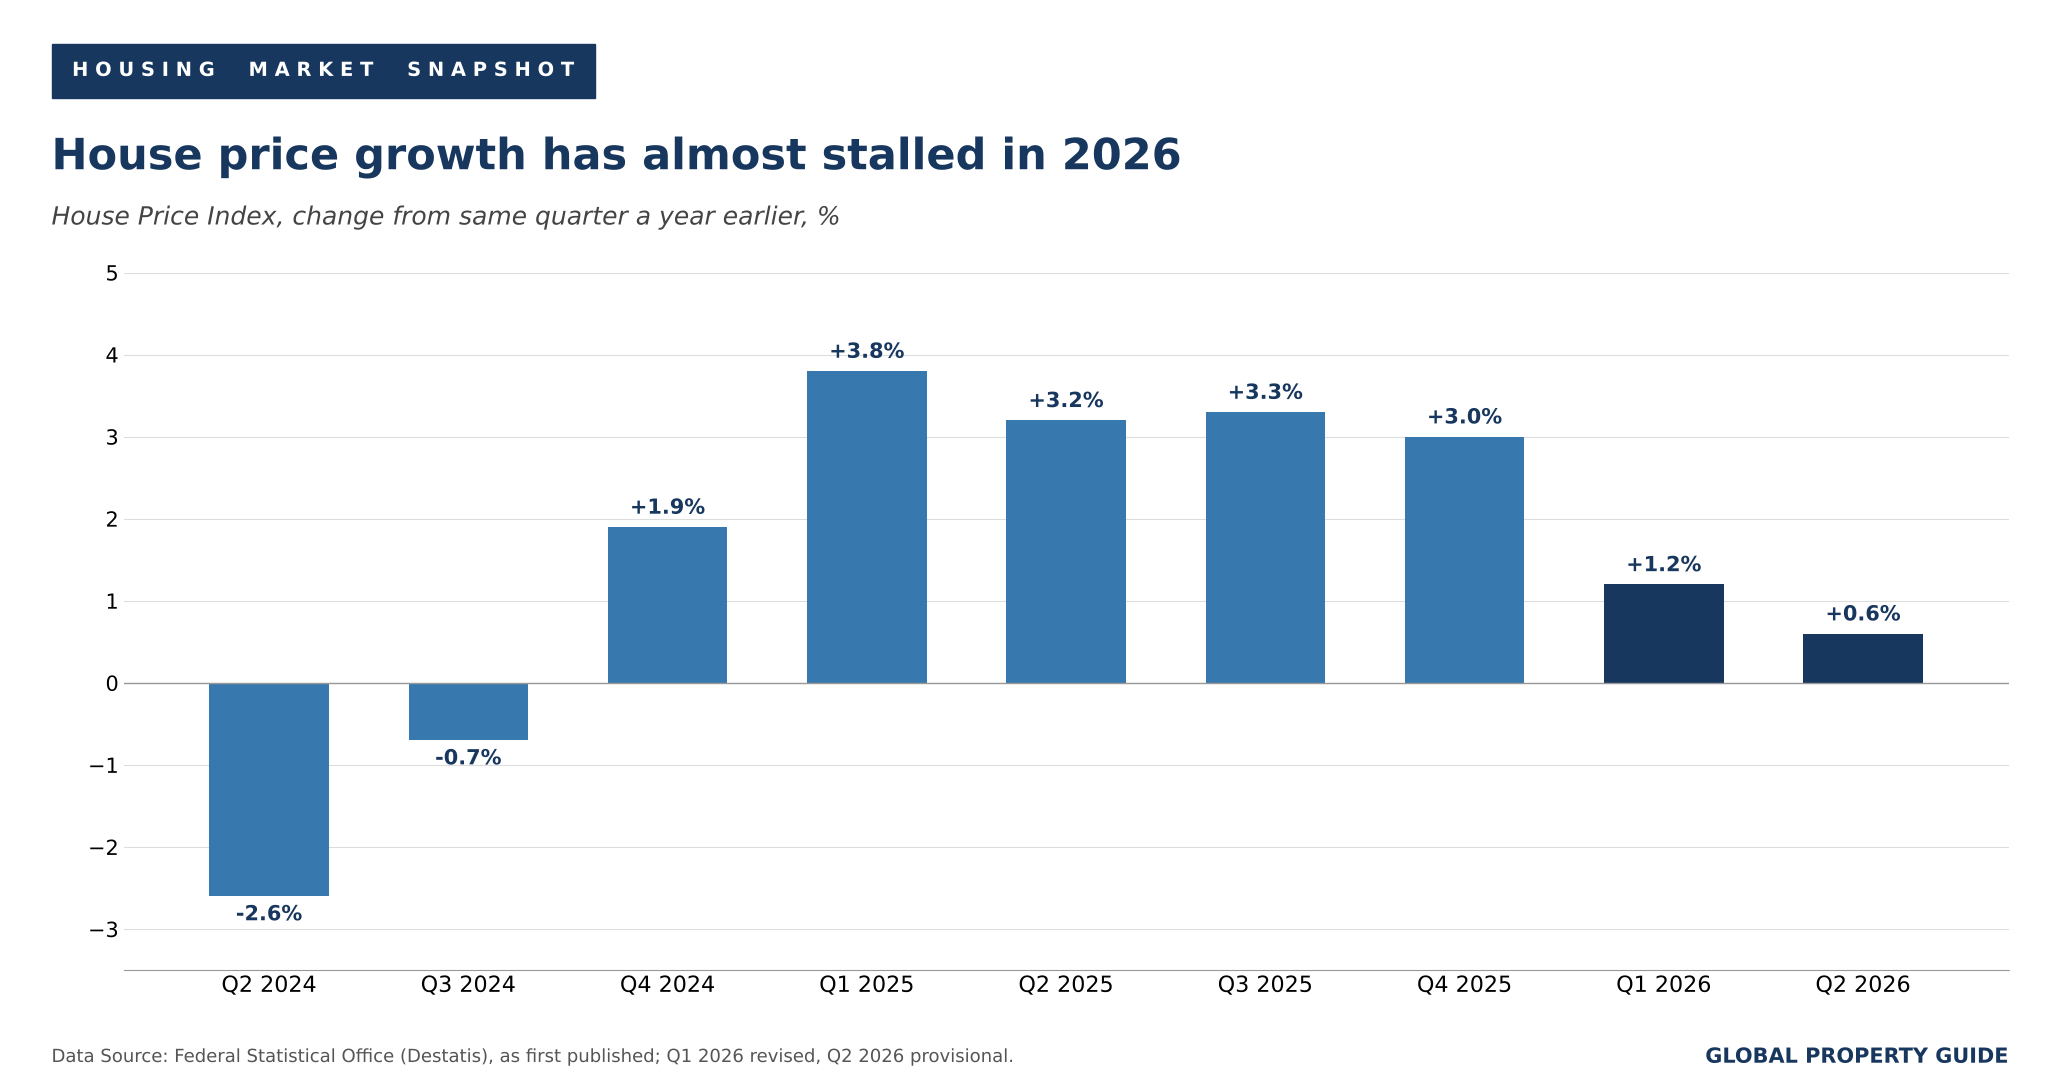
Germany's house price annual change:
House prices rose by just 0.6% in the year to Q2 2026, the Federal Statistical Office (Destatis) reported in its provisional estimate. From Q1, prices rose by 0.3%. Destatis also revised its figure for Q1 2026 down to 1.2%, from the 1.4% it had first published. Consumer prices rose by about 2.6% on average over the same April to June period, so house prices fell by about 1.9% in real terms.
The big cities are now the weakest part of the market. In the seven largest cities (Berlin, Hamburg, Munich, Cologne, Frankfurt, Stuttgart and Dusseldorf), apartment prices fell by 0.4% from a year earlier in Q2 2026, and by 0.5% from Q1, the Destatis release shows. Apartment prices in other large cities were still rising, by 2.0%. In densely populated rural districts, apartment prices fell by 1.8%, while house prices there rose by 1.0%.
Apartment prices are now falling
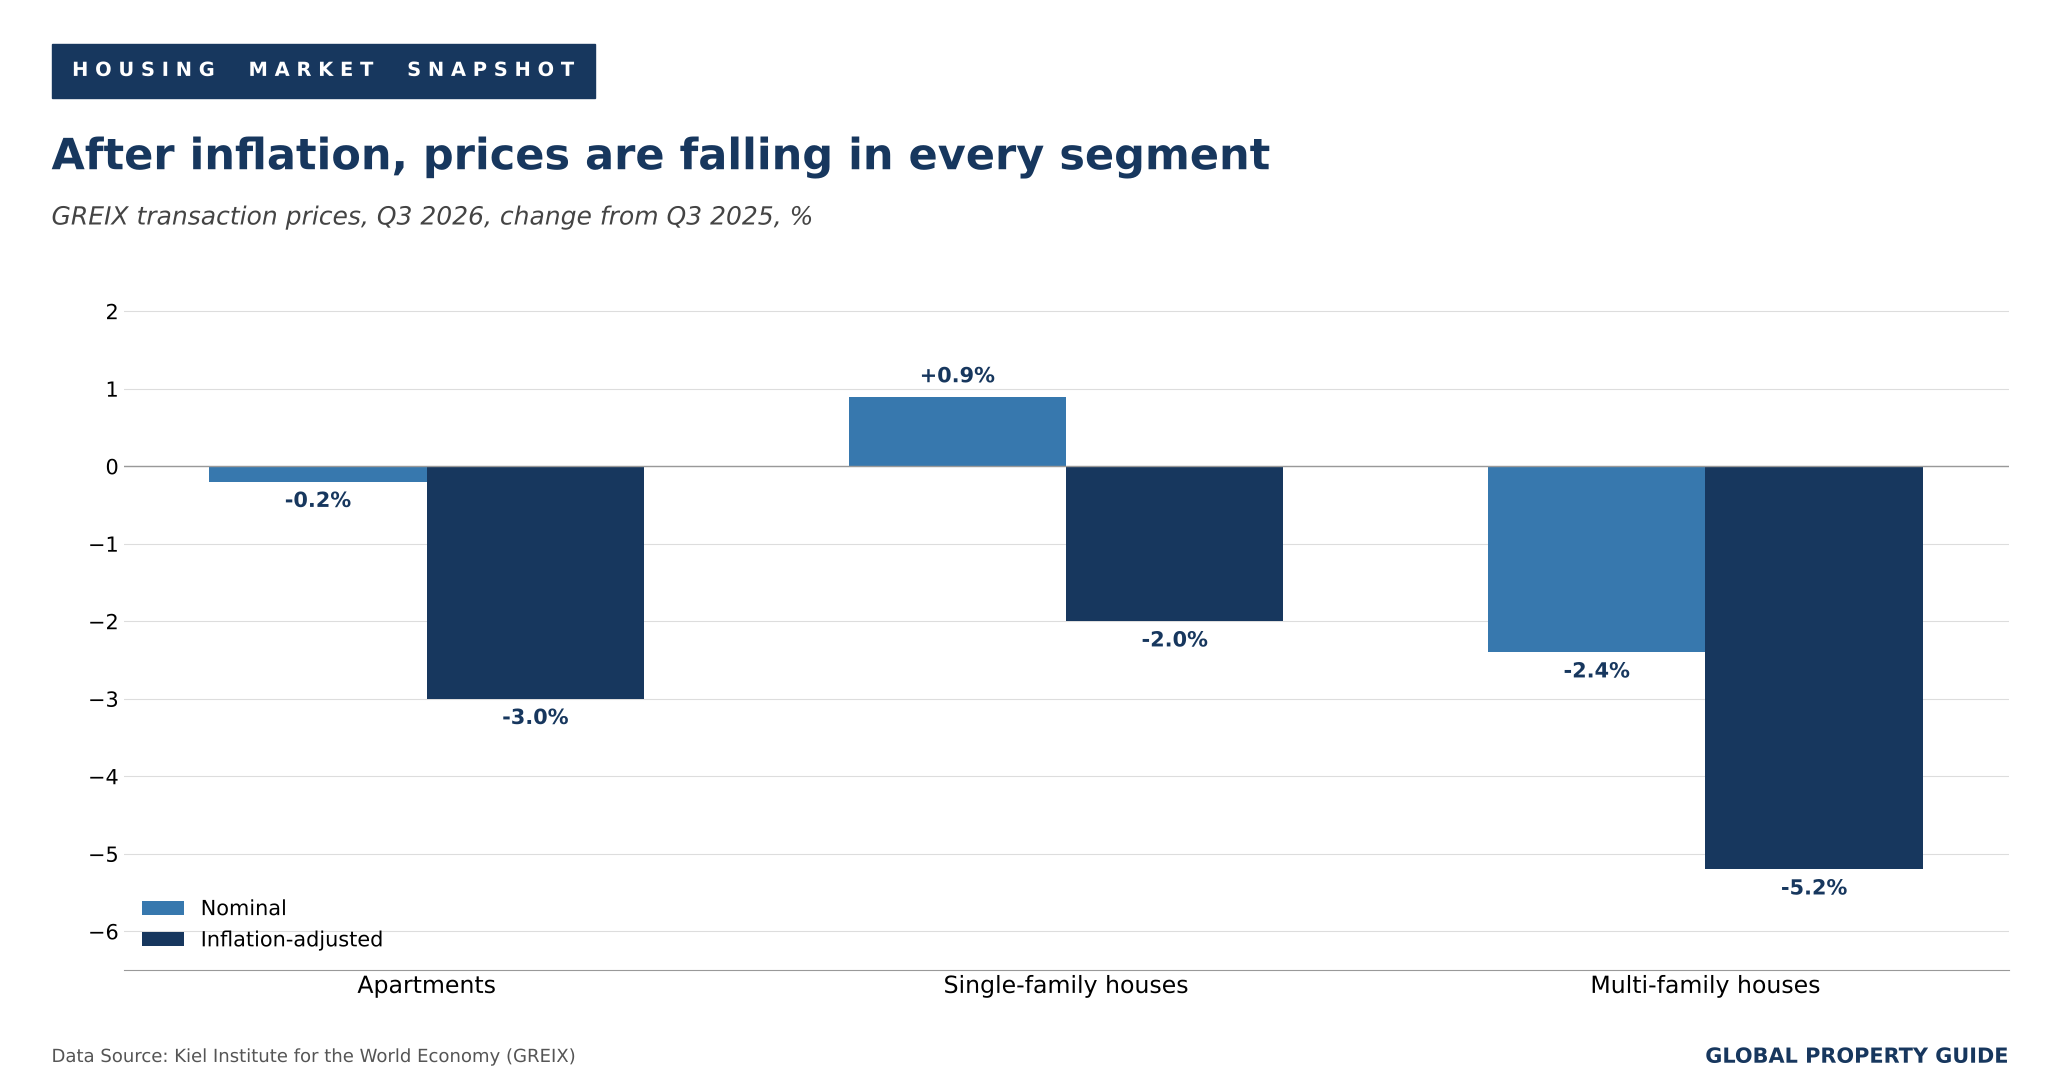
More recent transaction data confirm the slowdown. In Q3 2026, apartment prices were 0.2% lower than a year earlier, the first annual fall in more than two years, the Kiel Institute for the World Economy found in its GREIX index, which is based on notarized sales prices. Single-family house prices were still 0.9% higher than a year earlier, but 0.5% lower than in Q2. Prices of multi-family houses fell by 2.4%.
After inflation, prices fell in every segment: by 3.0% for apartments, 2.0% for single-family houses and 5.2% for multi-family houses. "Price growth for apartments has practically come to a standstill," said Jonas Zdrzalek, who leads the GREIX project. He added that "there can be no talk of a broad recovery."
Homes are taking longer to sell, about 94 days for apartments and 95 days for single-family houses, and sellers cut their asking price on 22.4% of apartment listings and 21.0% of house listings in Q3. Both shares have risen for five quarters in a row, the Kiel Institute said. Fewer homes are also changing hands: in Q2 2026, sales of apartments were 1.7% lower than a year earlier, and sales of single-family houses 8.2% lower.
Prices are diverging between cities. In Q3, apartment prices fell by 2.9% from a year earlier in Berlin, the third annual fall in a row, while they rose by 4.6% in Cologne. Expensive markets remain furthest below their previous peaks, Zdrzalek noted, probably because they are more sensitive to higher interest rates.
Asking prices in the big cities
Asking prices, which reflect what sellers want, held up better in the first half of the year. In the eight largest cities, the median asking price for an apartment was EUR 5,656 (USD 6,251) per square meter in H1 2026, up 2.9% from a year earlier, the real estate services firm JLL said. New apartments were offered at an average of EUR 7,935 (USD 8,770) per square meter, up 1.1%.
Asking prices for apartments in the eight largest cities:
| City | EUR per sq. m., H1 2026 |
USD per sq. m., H1 2026 |
Change from H1 2025 |
| Munich | EUR 8,860 | USD 9,792 | 2.2% |
| Frankfurt | EUR 6,330 | USD 6,996 | -1.0% |
| Hamburg | EUR 6,300 | USD 6,963 | 1.6% |
| Berlin | EUR 5,800 | USD 6,410 | 2.8% |
| Cologne | EUR 5,250 | USD 5,802 | 6.4% |
| Dusseldorf | EUR 4,950 | USD 5,471 | 6.4% |
| Stuttgart | EUR 4,620 | USD 5,106 | -1.3% |
| Leipzig | EUR 3,150 | USD 3,481 | 3.0% |
| Note: Converted at EUR 1 = USD 1.1052, the ECB reference rate on 13 November 2026. | |||
| Data source: JLL. | |||
All dollar conversions in this article use the ECB reference rate for 13 November 2026, EUR 1 = USD 1.1052, as published by the ECB. The euro has lost 5.6% of its value against the dollar since our previous edition, which used EUR 1 = USD 1.1703 for its price table.
Destatis will publish its first estimate for Q3 2026 in late December. With inflation near 3% and borrowing costs higher, real house prices are likely to keep falling in the coming quarters.
Historic Perspective
From stability to boom
In the 2000s, Germany was one of Europe's most stable housing markets. Prices moved only a little for most of the decade. Cautious mortgage lending, a large rental sector, modest wage growth, and the overbuilding that followed reunification all kept speculation in check. As a result, Germany had neither the housing boom seen in many European countries before 2008 nor the crash that followed.
That changed after 2010. A stronger labor market, growing cities and very cheap credit lifted demand, while new supply responded only slowly. What began as a catch-up after years of stagnation became a long boom, strongest in the big cities and the most prosperous regions. By 2021, prices were rising by more than 12% a year.
Correction and partial recovery
When inflation and interest rates rose sharply in 2022, the boom ended. Prices fell year-on-year in Q4 2022 for the first time since 2010. In 2023, prices fell by more than in any year since the Destatis index began, as higher mortgage rates cut buyers' purchasing power and investors withdrew. The decline continued, more slowly, into 2024.
Prices returned to growth in 2025, rising by about 3%. But in real terms the recovery was small, and in 2026 it has faded again as rates have risen. Real house prices are still well below their 2021 level.
Annual house price change, nominal and inflation-adjusted (end of year):
| Year | Nominal house prices |
Inflation-adjusted house prices |
| 2006 | 1.22% | -0.07% |
| 2007 | -1.69% | -4.62% |
| 2008 | 0.25% | -1.35% |
| 2009 | 2.93% | 2.52% |
| 2010 | -0.48% | -1.83% |
| 2011 | 4.18% | 1.91% |
| 2012 | 4.93% | 2.86% |
| 2013 | 1.53% | 0.19% |
| 2014 | 3.44% | 2.92% |
| 2015 | 5.82% | 5.49% |
| 2016 | 8.45% | 7.25% |
| 2017 | 6.25% | 5.04% |
| 2018 | 6.22% | 4.16% |
| 2019 | 6.50% | 5.19% |
| 2020 | 8.74% | 9.29% |
| 2021 | 12.61% | 7.55% |
| 2022 | -2.46% | -10.17% |
| 2023 | -7.63% | -10.80% |
| 2024 | 1.91% | -0.37% |
| 2025 | 3.02% | 0.83% |
| Data sources: Destatis, OECD. | ||
Property Supply and Demand Trends
Completions are at their lowest since 2012
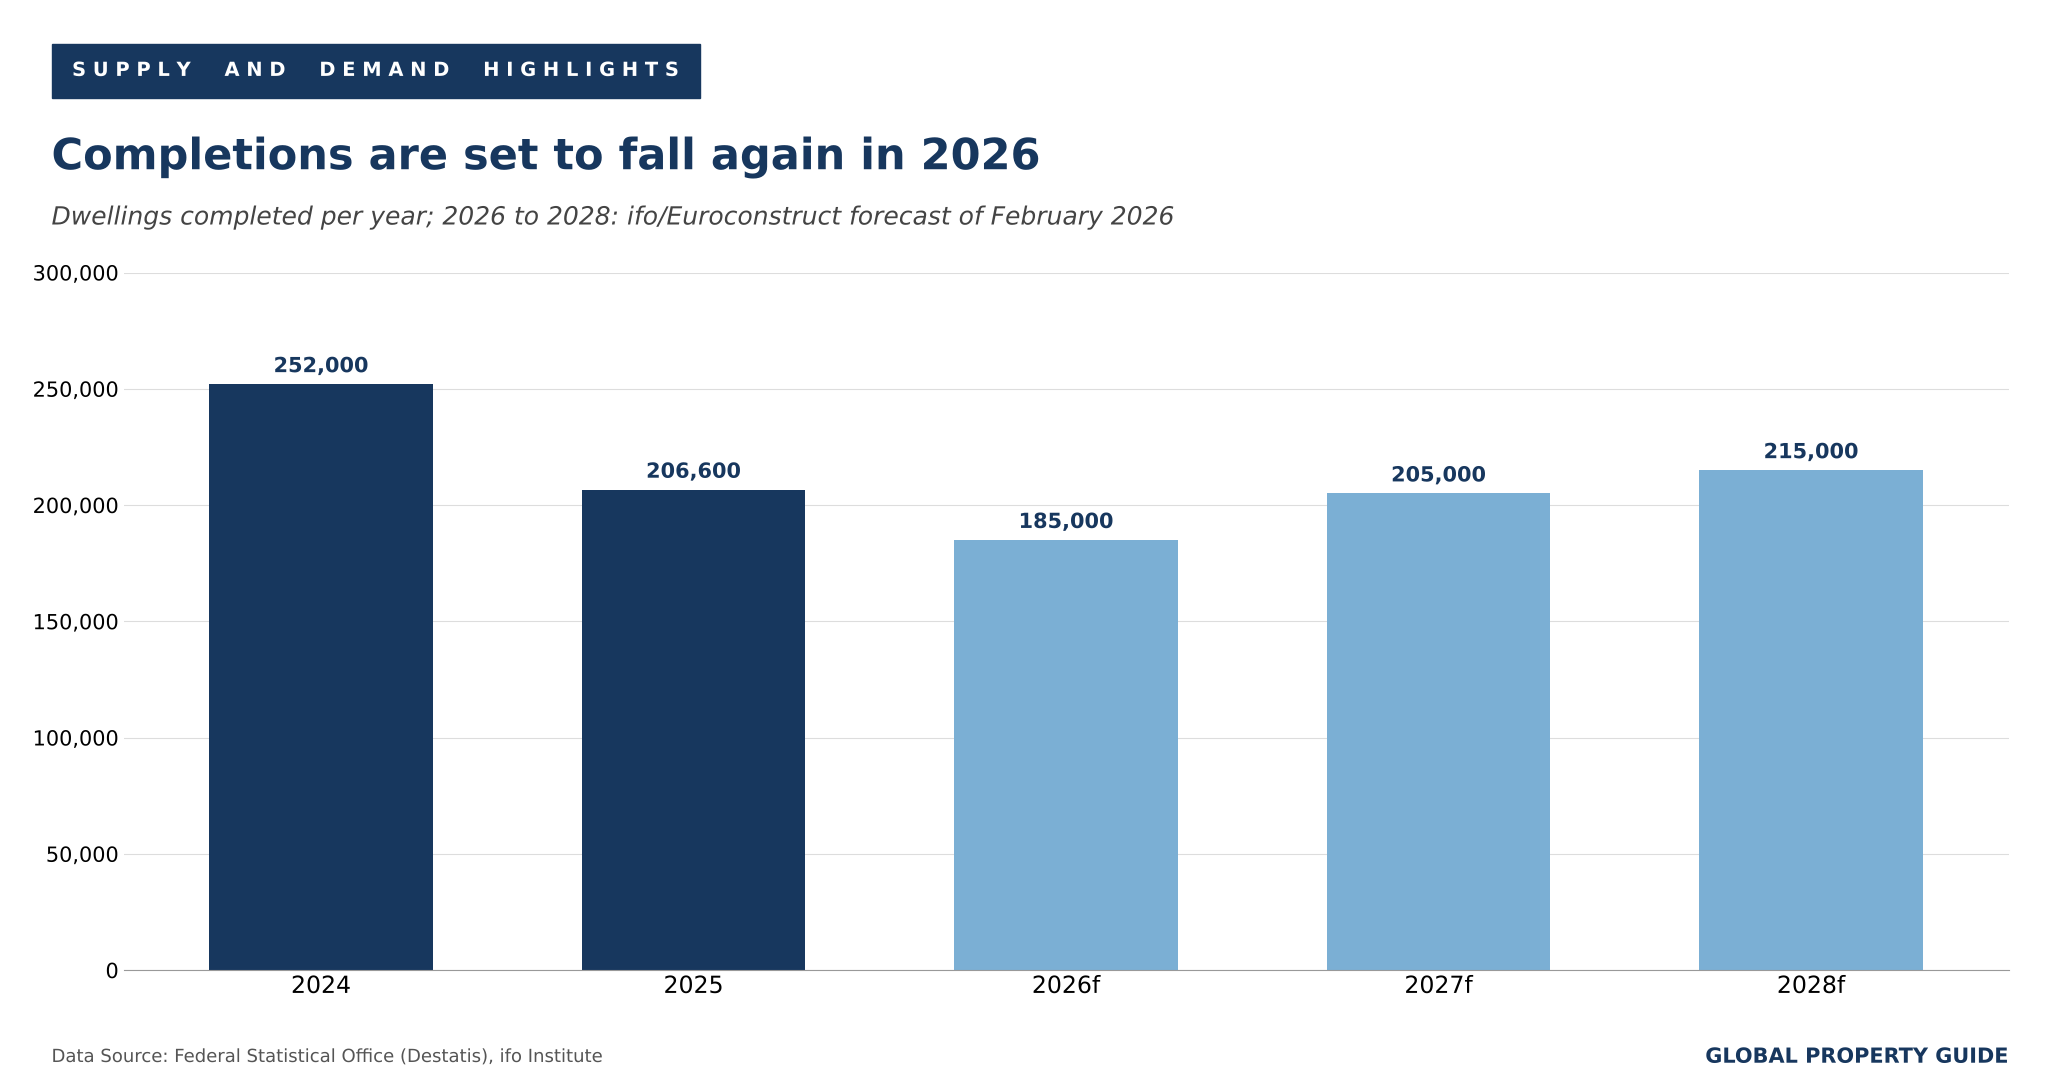
Germany is building far fewer homes than it needs. Only 206,600 dwellings were completed in 2025, 18.0% fewer than in 2024 and the lowest number since 2012, Destatis reported. Projects are also taking longer: on average, 27 months passed between a permit and completion, compared with 20 months in 2020. At the end of 2025, 760,700 dwellings had been approved but not yet completed, of which 307,200 were under construction.
The decline is not over. In February, the ifo Institute forecast, as part of the Euroconstruct research network, that completions would fall to about 185,000 in 2026, before recovering to 205,000 in 2027 and 215,000 in 2028. Since then, building costs have risen further: prices for building new homes were 5.5% higher in August 2026 than a year earlier, Destatis said, up from 5.0% in May.
Permits are rising strongly
The pipeline is starting to refill. Permits were issued for 126,300 dwellings in H1 2026, 15.1% more than a year earlier and the strongest first-half increase since 2016, Destatis reported. From January to August, 169,400 dwellings were approved, an increase of 12.1%. In 2025 as a whole, permits rose by 10.6% to 238,100.
Growth has slowed in recent months, however, and permits are still well below the levels of the early 2020s. Because projects take more than two years to complete, the rise in permits will not add much to supply before 2028. The government's "construction turbo" (Bau-Turbo), in force since 30 October 2025, lets municipalities approve housing more quickly, in some cases without a new development plan. Faster approvals do not solve the main problem, though: at current costs and interest rates, many projects do not pay.
Demand still far exceeds supply
The need for new homes remains large. The Federal Institute for Research on Building, Urban Affairs and Spatial Development (BBSR) estimates that Germany needs about 320,000 new dwellings a year until 2030. Completions in 2025 met only about two-thirds of that need, and the 185,000 expected in 2026 would meet less than 60%.
The shortage is most acute in the big cities. The BBSR estimates that the seven largest cities alone need about 60,000 new dwellings a year, about one-fifth of the national total, and that about 70% of new homes should be in apartment buildings. Germany's population fell slightly to about 83.5 million at the end of 2025, as lower net immigration no longer offset the natural decline, Destatis reported. But this has done little to ease pressure in the cities.
Vacancy is very low. The nationwide vacancy rate fell to 2.2% in 2024, below the 3% generally needed for a functioning market, and was much lower in the seven largest cities, BNP Paribas Real Estate found.
Rental Market: Rents and Rental Yields
Asking rents have picked up again
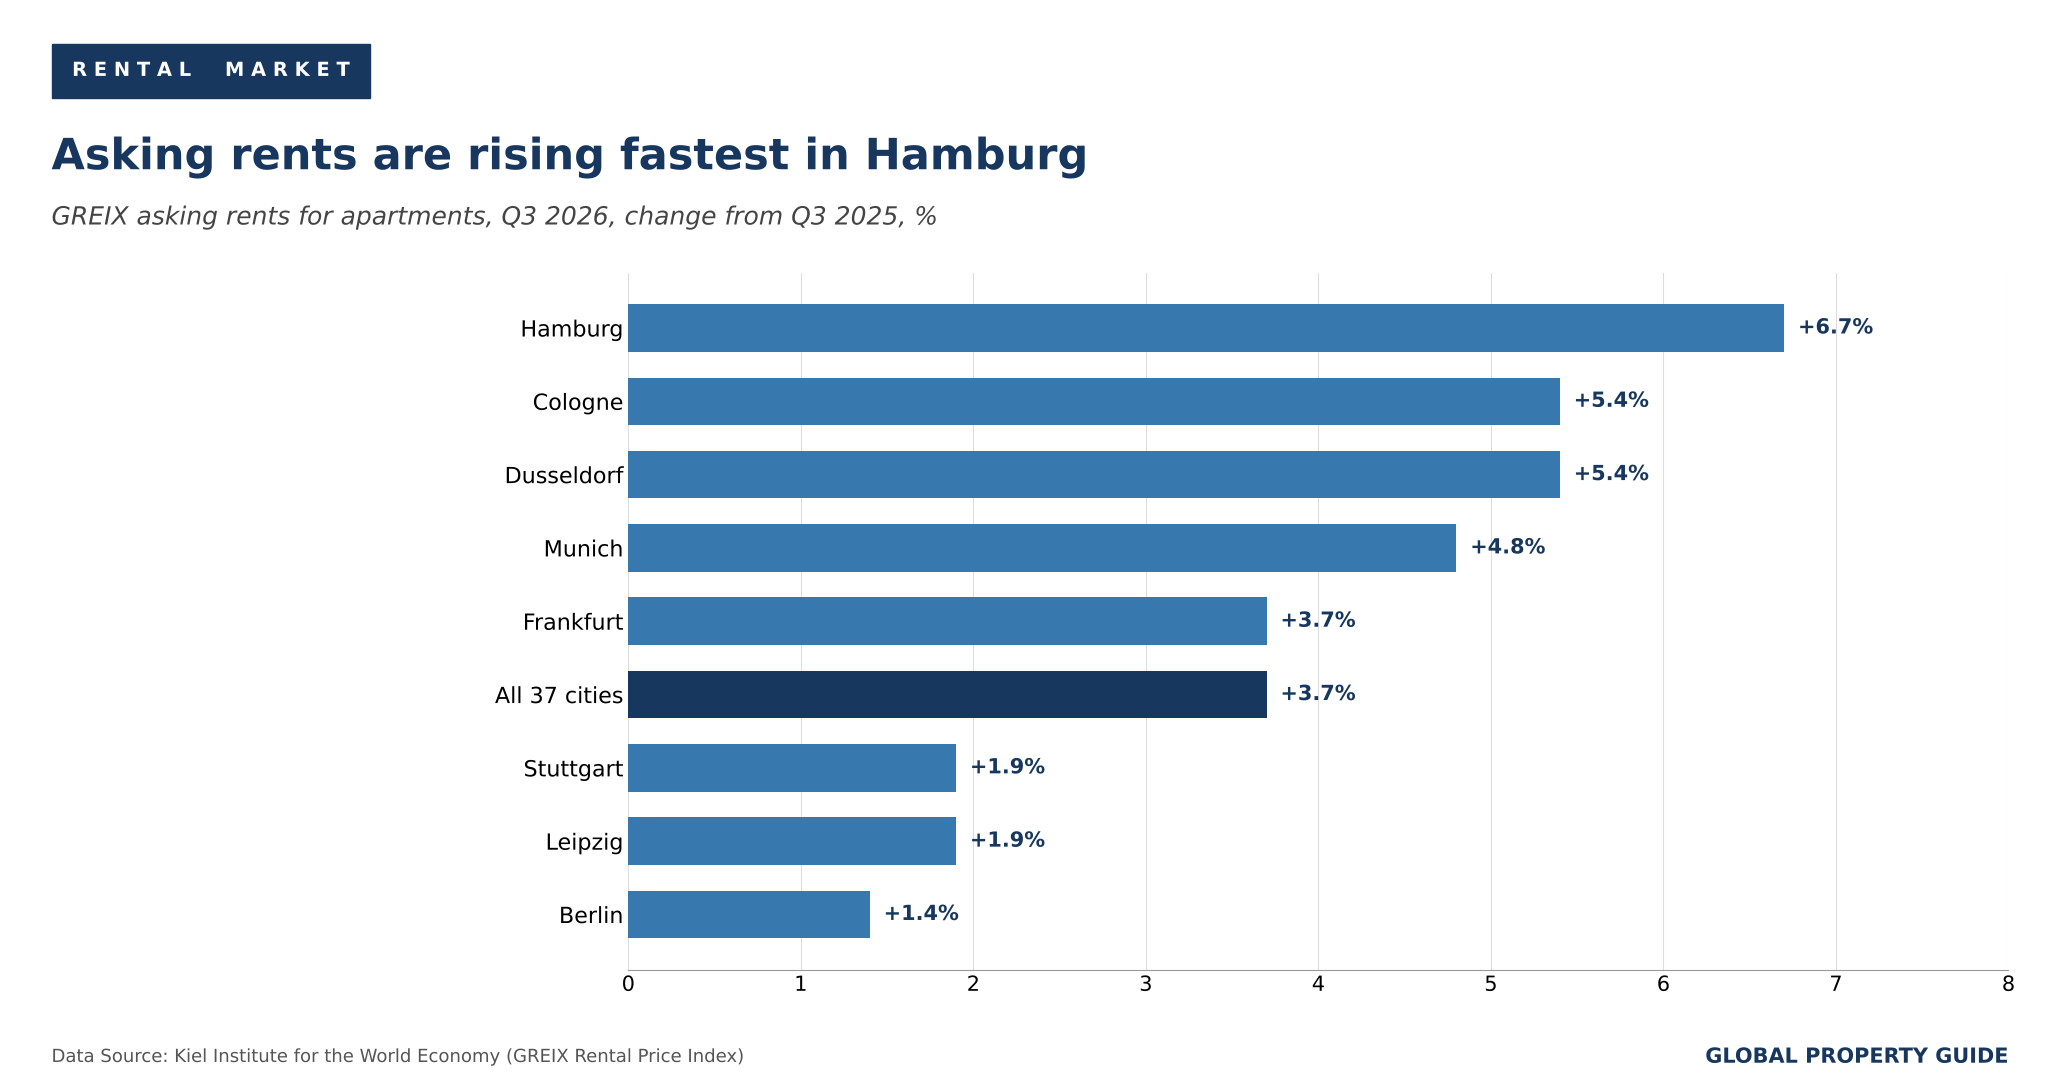
Rents continue to rise, and the pace picked up in the third quarter. Asking rents for apartments rose by 1.2% from Q2 2026 and by 3.7% from a year earlier, the Kiel Institute's GREIX rental index shows. "This is the strongest quarterly increase since the first quarter of 2025," the institute said. After inflation, rents rose by 0.7%. The average asking rent across the 37 cities and regions covered was EUR 14.6 (USD 16.1) per square meter per month.
Germany's rent price index:
Existing apartments, rather than new ones, are driving the increase. Rents for existing apartments rose by 3.7% from a year earlier, compared with 3.3% for new-build apartments. Among the big cities, Hamburg (+6.7%), Cologne (+5.4%) and Dusseldorf (+5.4%) had the fastest growth, and Berlin (+1.4%) the slowest.
Growth has slowed in the most expensive markets
JLL's data show that rent growth slowed sharply in the first half of the year. The median asking rent in the eight largest cities was EUR 17.98 (USD 19.87) per square meter in H1 2026, up 3.0% from a year earlier, compared with 6.8% growth a year before. Rents for new apartments rose by only 0.5%. "Willingness to pay at the upper end of the market is increasingly reaching its limits," said Soren Grobel, head of living research at JLL Germany.
Munich remains by far the most expensive city, at EUR 25.41 (USD 28.08) per square meter, more than twice the level in Leipzig. In Berlin, asking rents fell by 4.3%.
Median asking rents in the eight largest cities:
| City | EUR per sq. m. per month, H1 2026 |
USD per sq. m. per month, H1 2026 |
Change from H1 2025 |
| Munich | EUR 25.41 | USD 28.08 | 5.4% |
| Frankfurt | EUR 19.45 | USD 21.50 | 2.4% |
| Berlin | EUR 18.66 | USD 20.62 | -4.3% |
| Hamburg | EUR 18.63 | USD 20.59 | 4.7% |
| Stuttgart | EUR 17.33 | USD 19.15 | 2.4% |
| Cologne | EUR 17.01 | USD 18.80 | 4.5% |
| Dusseldorf | EUR 16.19 | USD 17.89 | 7.4% |
| Leipzig | EUR 11.19 | USD 12.37 | 1.6% |
| Note: Converted at EUR 1 = USD 1.1052, the ECB reference rate on 13 November 2026. | |||
| Data source: JLL. | |||
Most Germans rent
More than half of Germans rent their home. The share of the population living in rented homes rose from 48.1% in 2015 to 52.8% in 2025, Eurostat data show. Rents in existing contracts are rising much more slowly than asking rents. In October 2026, net rents excluding heating were 1.9% higher than a year earlier, Destatis said, well below overall inflation of 2.8%. The Bundesbank's transaction-weighted rent index rose by 3.4% in 2025, after 3.7% in 2024.
To limit rent increases, the federal government extended the rent brake (Mietpreisbremse) until the end of 2029. In tight markets, rents on new contracts may not be more than 10% above the local comparable rent.
Rental yields
Gross rental yields on apartments in Germany averaged 3.35% in Q3 2026, down from 3.42% in Q1 2026, Global Property Guide research shows. Yields were highest in Stuttgart (4.29%), Leipzig (4.11%) and Berlin (4.06%), and lowest in Munich (2.77%) and Hamburg (1.99%). With mortgage rates above 4%, buying to let in the big cities now rarely covers the cost of borrowing.
Mortgage Market and Interest Rates
The ECB has raised rates twice
In our May edition, the ECB's deposit facility rate stood at 2.00%, where it had been since June 2025. Since then, the ECB has raised rates twice in response to the energy shock caused by the war in the Middle East: in June, and again on 10 September 2026, when it took the deposit rate to 2.50%, its press release shows. It warned that "inflation is set to remain well above target for an extended period."
Germany's mortgage loan interest rates:
On 29 October, the ECB kept its rates unchanged. It noted that "financing conditions have tightened" since its previous meeting, and said it is "not pre-committing to a particular rate path." Its next decision is due on 17 December.
Mortgage rates are the highest since 2023
German mortgage rates have risen steadily this year. The average effective rate on new housing loans to households was 4.09% in September 2026, up from 3.72% in March and 3.74% a year earlier, provisional Bundesbank statistics show. It was the highest rate since at least the start of 2024. Including fees, the annual percentage rate of charge was 4.13%.
Loans fixed for more than 10 years, the most common type in Germany, cost 4.13% in September, up from 3.74% in March. Floating-rate loans and loans fixed for up to one year cost 4.51%. In its September update, the mortgage broker Interhyp reported that rates on 10-year loans had climbed to about 4.2%.
Average interest rates on new housing loans to households:
| Type of loan | Sep 2026 | Mar 2026 | Sep 2025 |
| All new housing loans | 4.09% | 3.72% | 3.74% |
| Floating rate and fixed up to 1 year | 4.51% | 4.07% | 4.16% |
| Fixed over 1 and up to 5 years | 4.03% | 3.63% | 3.58% |
| Fixed over 5 and up to 10 years | 3.91% | 3.60% | 3.60% |
| Fixed over 10 years | 4.13% | 3.74% | 3.79% |
| Note: September 2026 provisional. | |||
| Data source: Deutsche Bundesbank. | |||
Lending has stopped growing
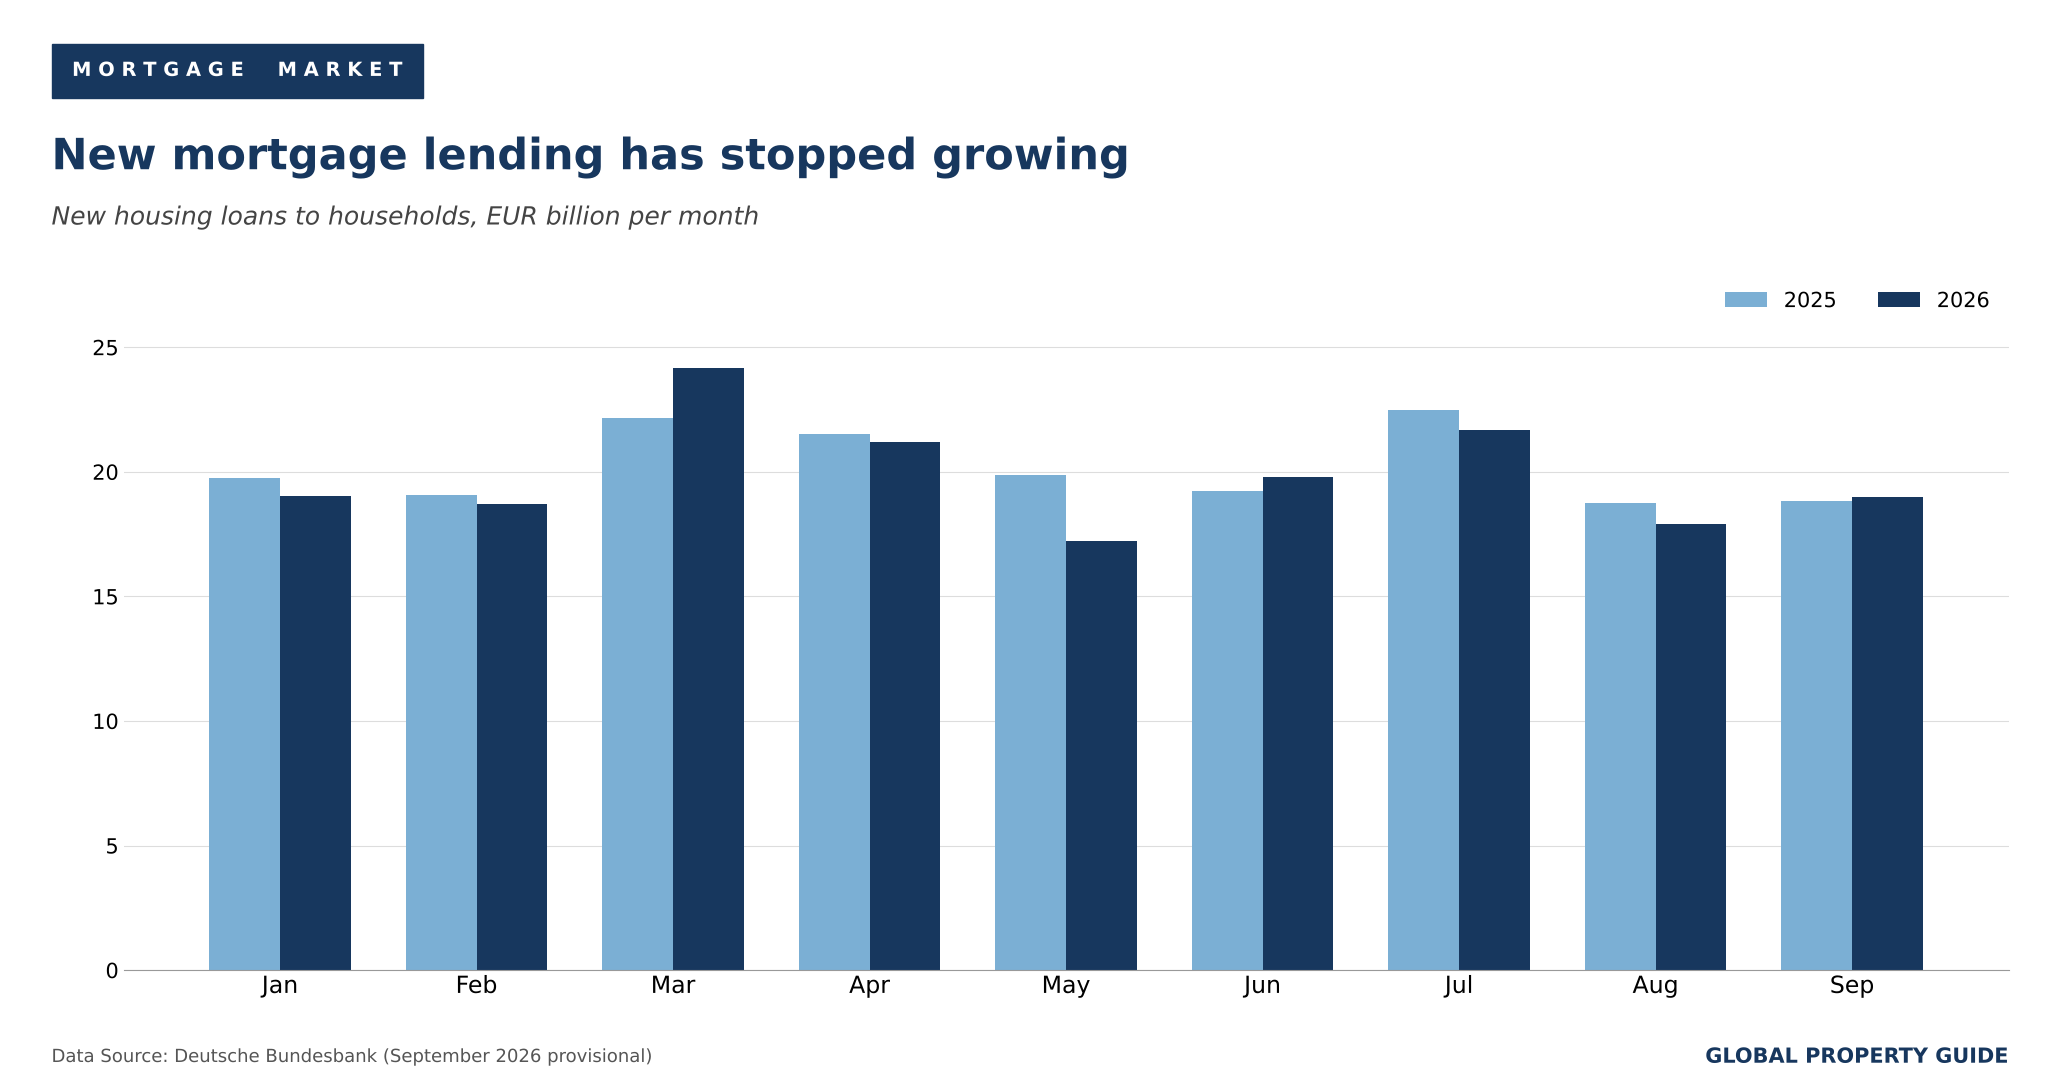
Higher rates are now holding back borrowing. Banks made EUR 178.6 billion (USD 197.4 billion) of new housing loans to households from January to September 2026, 1.6% less than in the same period of 2025, the Bundesbank figures show. In Q3, new lending was 2.5% lower than a year earlier. That is a sharp change from 2025, when new lending jumped by 21.4% to EUR 240.9 billion (USD 266.2 billion).
The higher cost of finance is also weighing on investors. The prime yield on apartment buildings in the seven largest cities rose by 20 basis points in Q3 to about 3.6%, the first rise since early 2024, CBRE reported. With the yield on 10-year German government bonds also above 3.6%, the extra return from residential property has disappeared.
Economic and Social Factors
Growth has picked up
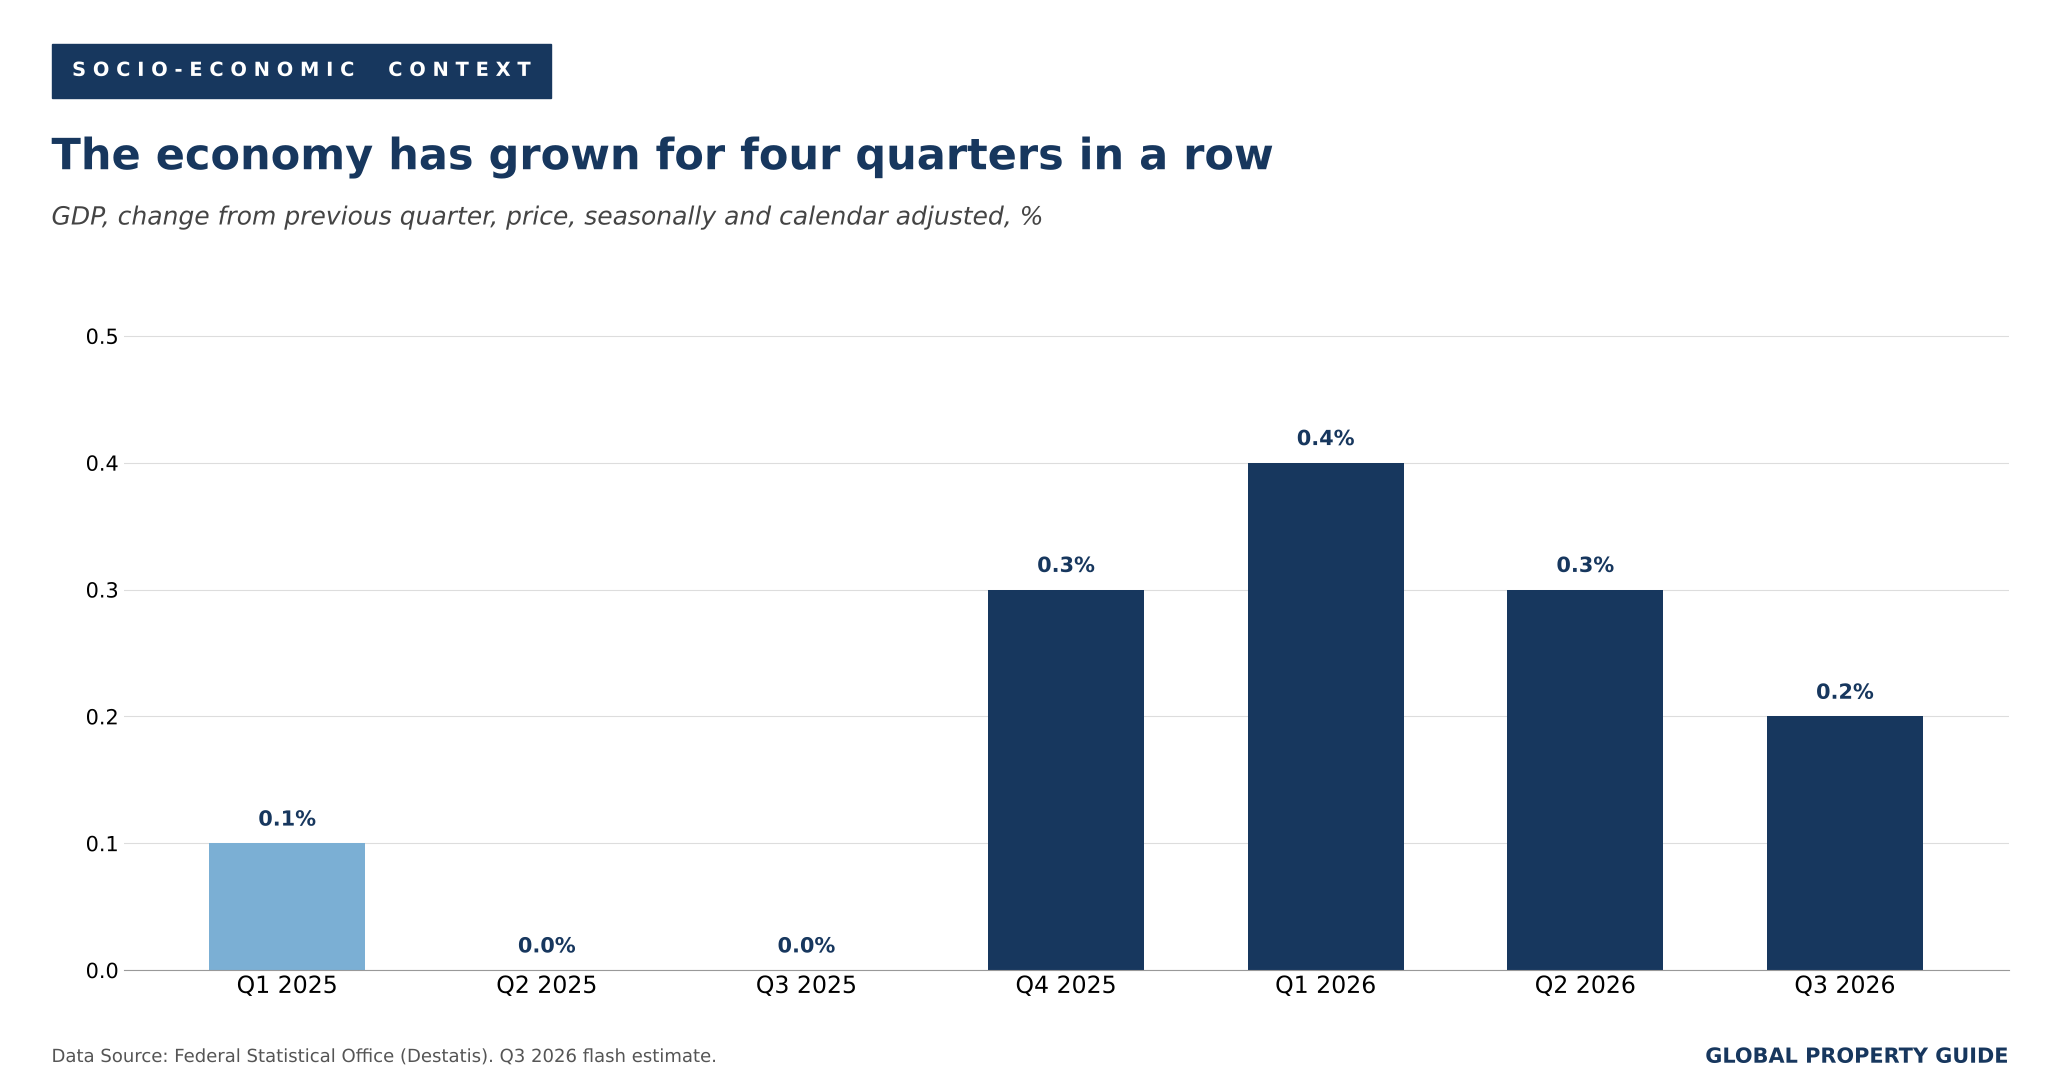
Germany's economy has gained some momentum this year. GDP rose by 0.2% in Q3 2026 from the previous quarter, after growth of 0.4% in Q1 and 0.3% in Q2, Destatis reported in its flash estimate. GDP was 1.3% higher than a year earlier. Household spending rose slightly, while investment fell and exports slowed after a strong first half.
In October, the International Monetary Fund (IMF) raised its forecast for German growth to 1.3% in 2026 and 1.1% in 2027, after just 0.2% in 2025. In May, the European Commission had expected growth of only 0.6% in 2026.
Inflation has risen with energy prices
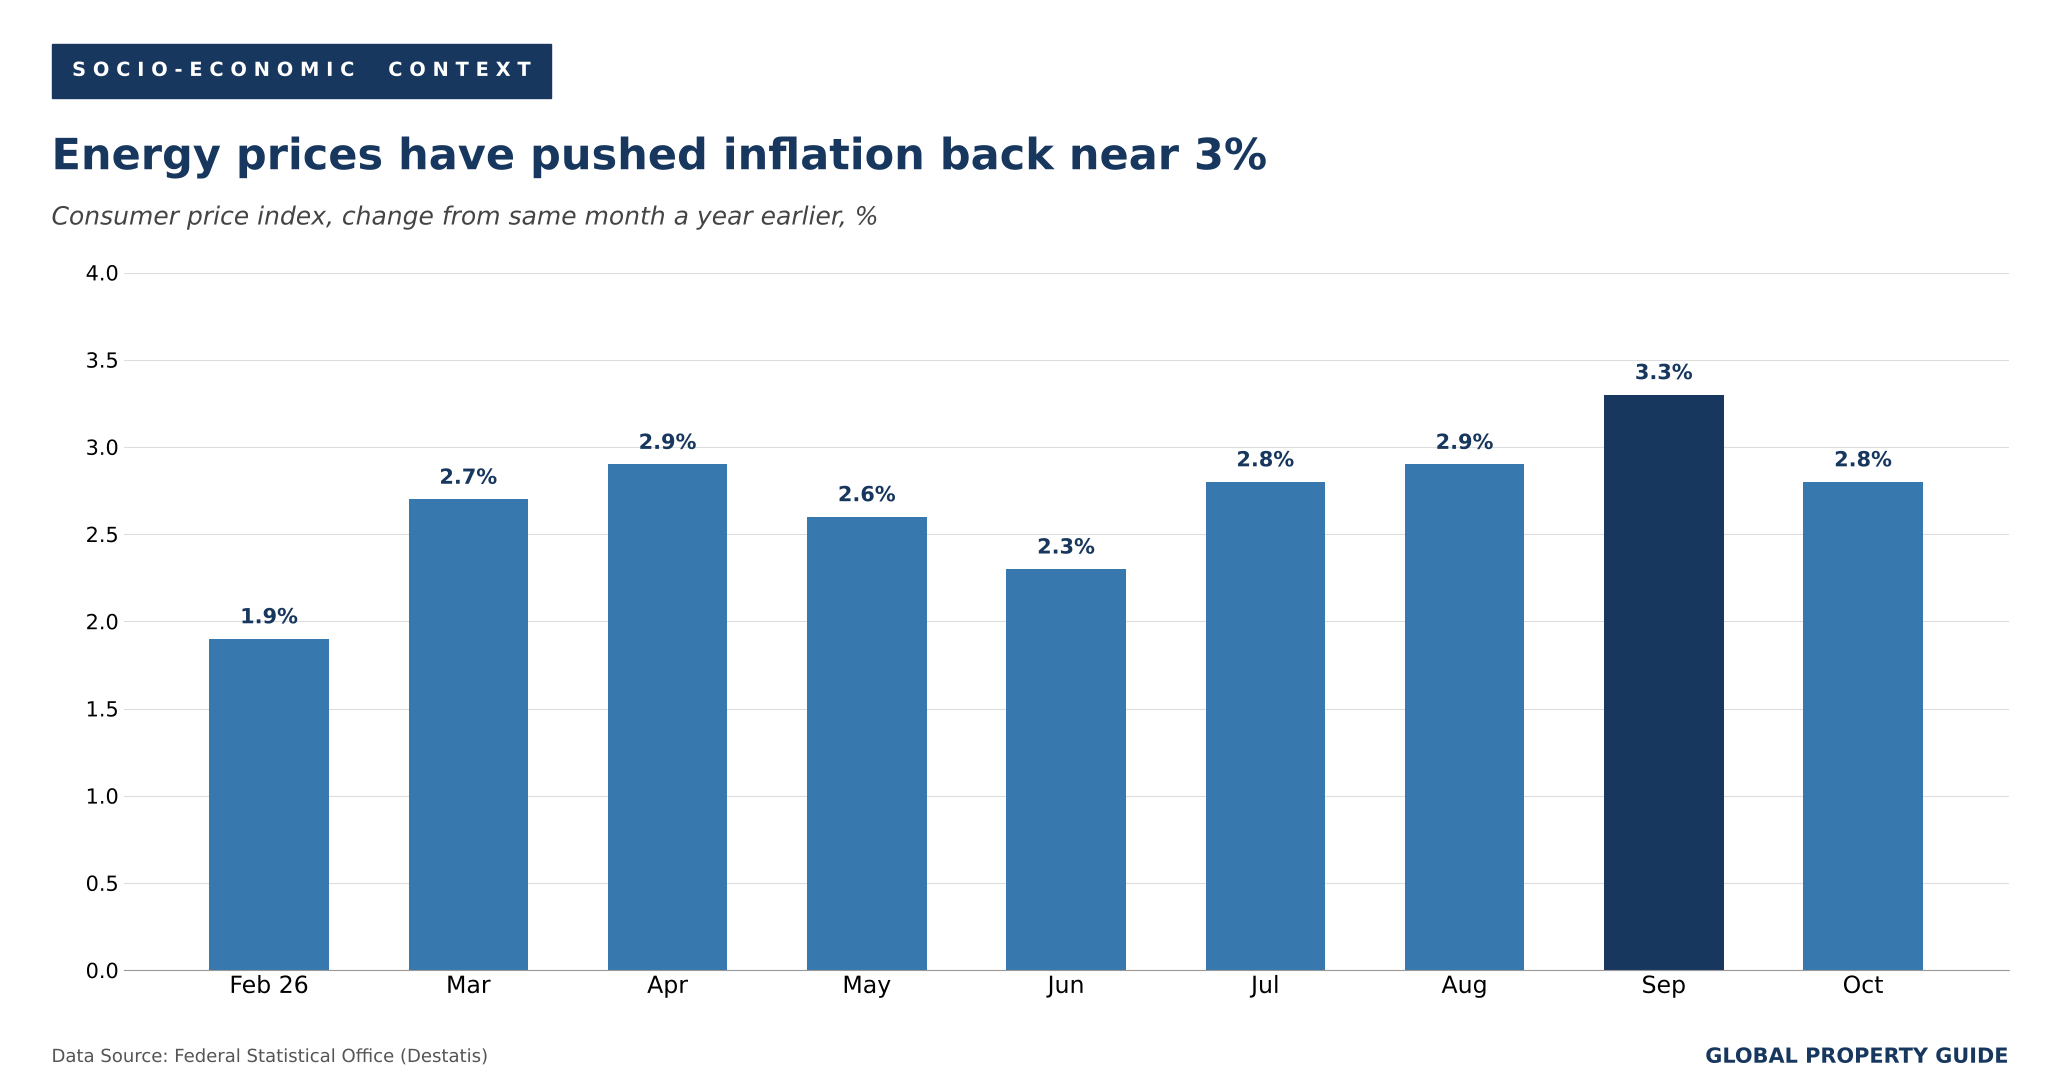
The energy shock has pushed inflation up. Consumer prices rose by 3.3% in the year to September 2026, the highest rate since December 2023, Destatis said. Inflation eased to 2.8% in October, helped by a new fuel discount, but energy prices were still 12.2% higher than a year earlier, the October release shows. Core inflation, excluding food and energy, was 2.1%.
The IMF expects inflation to average 2.7% in 2026 and to rise to 3.1% in 2027.
The labor market is weak
Growth has not yet reached the labor market. The adjusted unemployment rate was 4.1% in September 2026, slightly higher than a year earlier, and the number of people in work was 0.5% lower, Destatis reported.
Sources:
- Federal Statistical Office (Destatis)
- Prices of Residential Property in the 2nd Quarter of 2026: destatis.de
- Prices of Residential Property, 2nd Quarter of 2026, Full Release (DE): destatis.de
- Prices of Residential Property in the 1st Quarter of 2026: destatis.de
- 18.0% Fewer Completed Dwellings in 2025 (DE): destatis.de
- Building Permits for Dwellings in June 2026 (DE): destatis.de
- Construction Prices for Residential Buildings in August 2026 (DE): destatis.de
- Population at the End of 2025 (DE): destatis.de
- Inflation Rate at +3.3% in September 2026: destatis.de
- Inflation Rate at +2.8% in October 2026: destatis.de
- Inflation Rate at +2.8% in October 2026, Full Release (DE): destatis.de
- Gross Domestic Product in the 3rd Quarter of 2026: destatis.de
- Employment in September 2026: destatis.de
- Kiel Institute for the World Economy
- Apartment Prices Below Prior-Year Level for the First Time in More Than Two Years (GREIX Q3 2026): kielinstitut.de
- GREIX Rental Price Index Q3 2026: kielinstitut.de
- Deutsche Bundesbank
- Housing Loans to Households, Interest Rates and Volumes (DE): bundesbank.de
- System of Indicators for the German Residential Property Market: bundesbank.de
- European Central Bank (ECB)
- Monetary Policy Decisions, 10 September 2026: ecb.europa.eu
- Monetary Policy Decisions, 29 October 2026: ecb.europa.eu
- Euro Foreign Exchange Reference Rates, US Dollar: ecb.europa.eu
- JLL
- CBRE
- Germany Residential Market Q3 2026: cbre.com
- Interhyp
- Interest Rate Update September 2026 (DE): interhyp.de
- ifo Institute
- European Residential Construction Recovering, Germany Lagging Behind: ifo.de
- Federal Institute for Research on Building, Urban Affairs and Spatial Development (BBSR)
- Housing Demand Forecast to 2030 (DE): bbsr.bund.de
- Federal Ministry of Housing, Urban Development and Building
- Cabinet Approves "Construction Turbo" (DE): bmwsb.bund.de
- Press and Information Office of the Federal Government
- Rent Brake Extended (DE): bundesregierung.de
- BNP Paribas Real Estate
- Residential Report Germany: realestate.bnpparibas.de
- European Commission
- Economic Forecast for Germany, Spring 2026: economy-finance.ec.europa.eu
- Eurostat, Distribution of Population by Tenure Status: ec.europa.eu
- International Monetary Fund (IMF)
- World Economic Outlook, October 2026, Statistical Appendix Tables A: imf.org
- Fitch Ratings
- Fitch Affirms Germany at 'AAA'; Outlook Stable: fitchratings.com
- Global Property Guide
- Gross Rental Yields in Germany: globalpropertyguide.com