Hong Kong's Residential Property Market Analysis 2026
Hong Kong's housing recovery has hit a wall. House prices rose at their fastest pace in nearly eight years in the second quarter of 2026, but the rally stalled in July as a stock market correction and new mainland Chinese rules on outbound investment kept buyers away. In September, the Hong Kong Monetary Authority raised interest rates for the first time since 2023. Rents, meanwhile, are at a record high.
This extended overview from the Global Property Guide offers an in-depth analysis of Hong Kong's housing market, exploring its defining characteristics, recent market developments, and the long-term structural forces shaping the sector's trajectory.
Table of Contents
- Property Prices and Price Index
- Historic Perspective
- Property Demand Trends
- Property Supply Trends
- Rental Market: Rents and Rental Yields
- Mortgage Market and Interest Rates
- Economic and Social Factors
Property Prices and Price Index
In the second quarter of 2026, Hong Kong's residential property price index rose by 12.66% from a year earlier, according to the Rating and Valuation Department (RVD). It followed y-o-y increases of 10.21% in Q1 2026, 3.6% in Q4 2025 and 1.91% in Q3 2025, and a decline of 5.22% in Q2 2025. It was the strongest annual growth since Q3 2018.
Hong Kong's house price annual change:
When adjusted for inflation, house prices were up 10.45% y-o-y in Q2 2026. Quarter-on-quarter, prices rose by 2.87%.
The momentum has since faded. Prices fell by 0.8% in July, the first monthly decline since March 2025, and were broadly flat in August, when the index edged up just 0.06% to 320.5. Prices are up 6.98% in the first eight months of 2026, but remain 19.49% below their all-time peak of September 2021. The August figures are provisional.
Smaller homes led the upturn. By property class, the RVD price indices rose in Q2 2026 as compared to Q2 2025:
- Class A (less than 40 sq. m.): up 11.06%
- Class B (40 to 69.9 sq. m.): up 12.56%
- Class C (70 to 99.9 sq. m.): up 13.53%
- Class D (100 to 159.9 sq. m.): up 8.77%
- Class E (160 sq. m. and above): up 9.31%
Average selling prices on Hong Kong Island in Q2 2026:
| AVERAGE HOUSE PRICES, Q2 2026 | ||||||
| Property size | Hong Kong, HKD (USD) per sq. m. |
Kowloon, HKD (USD) per sq. m. |
New Territories, HKD (USD) per sq. m. |
Hong Kong, y-o-y % |
Kowloon, y-o-y % |
New Territories, y-o-y % |
| Less than 40 sq. m. | 149,699 (19,097) |
136,647 (17,432) |
124,925 (15,937) |
18.5 | 19.9 | 15.1 |
| 40 to 69.9 sq. m. | 154,402 (19,697) |
138,423 (17,659) |
116,991 (14,925) |
16.2 | 15.1 | 13.0 |
| 70 to 99.9 sq. m. | 186,959 (23,851) |
172,027 (21,946) |
129,698 (16,546) |
17.8 | 16.2 | 13.9 |
| 100 to 159.9 sq. m. | 218,081 (27,821) |
188,533 (24,052) |
116,977 (14,923) |
16.3 | 8.9 | 9.9 |
| 160 sq. m. and above | 238,708 (30,452) |
214,613* (27,379) |
98,916 (12,619) |
4.9 | -11.7* | 6.1 |
| Note: Secondary-market transactions only; Q2 2026 figures are provisional. *Fewer than 20 transactions. | ||||||
| Data source: Rating and Valuation Department (RVD). | ||||||
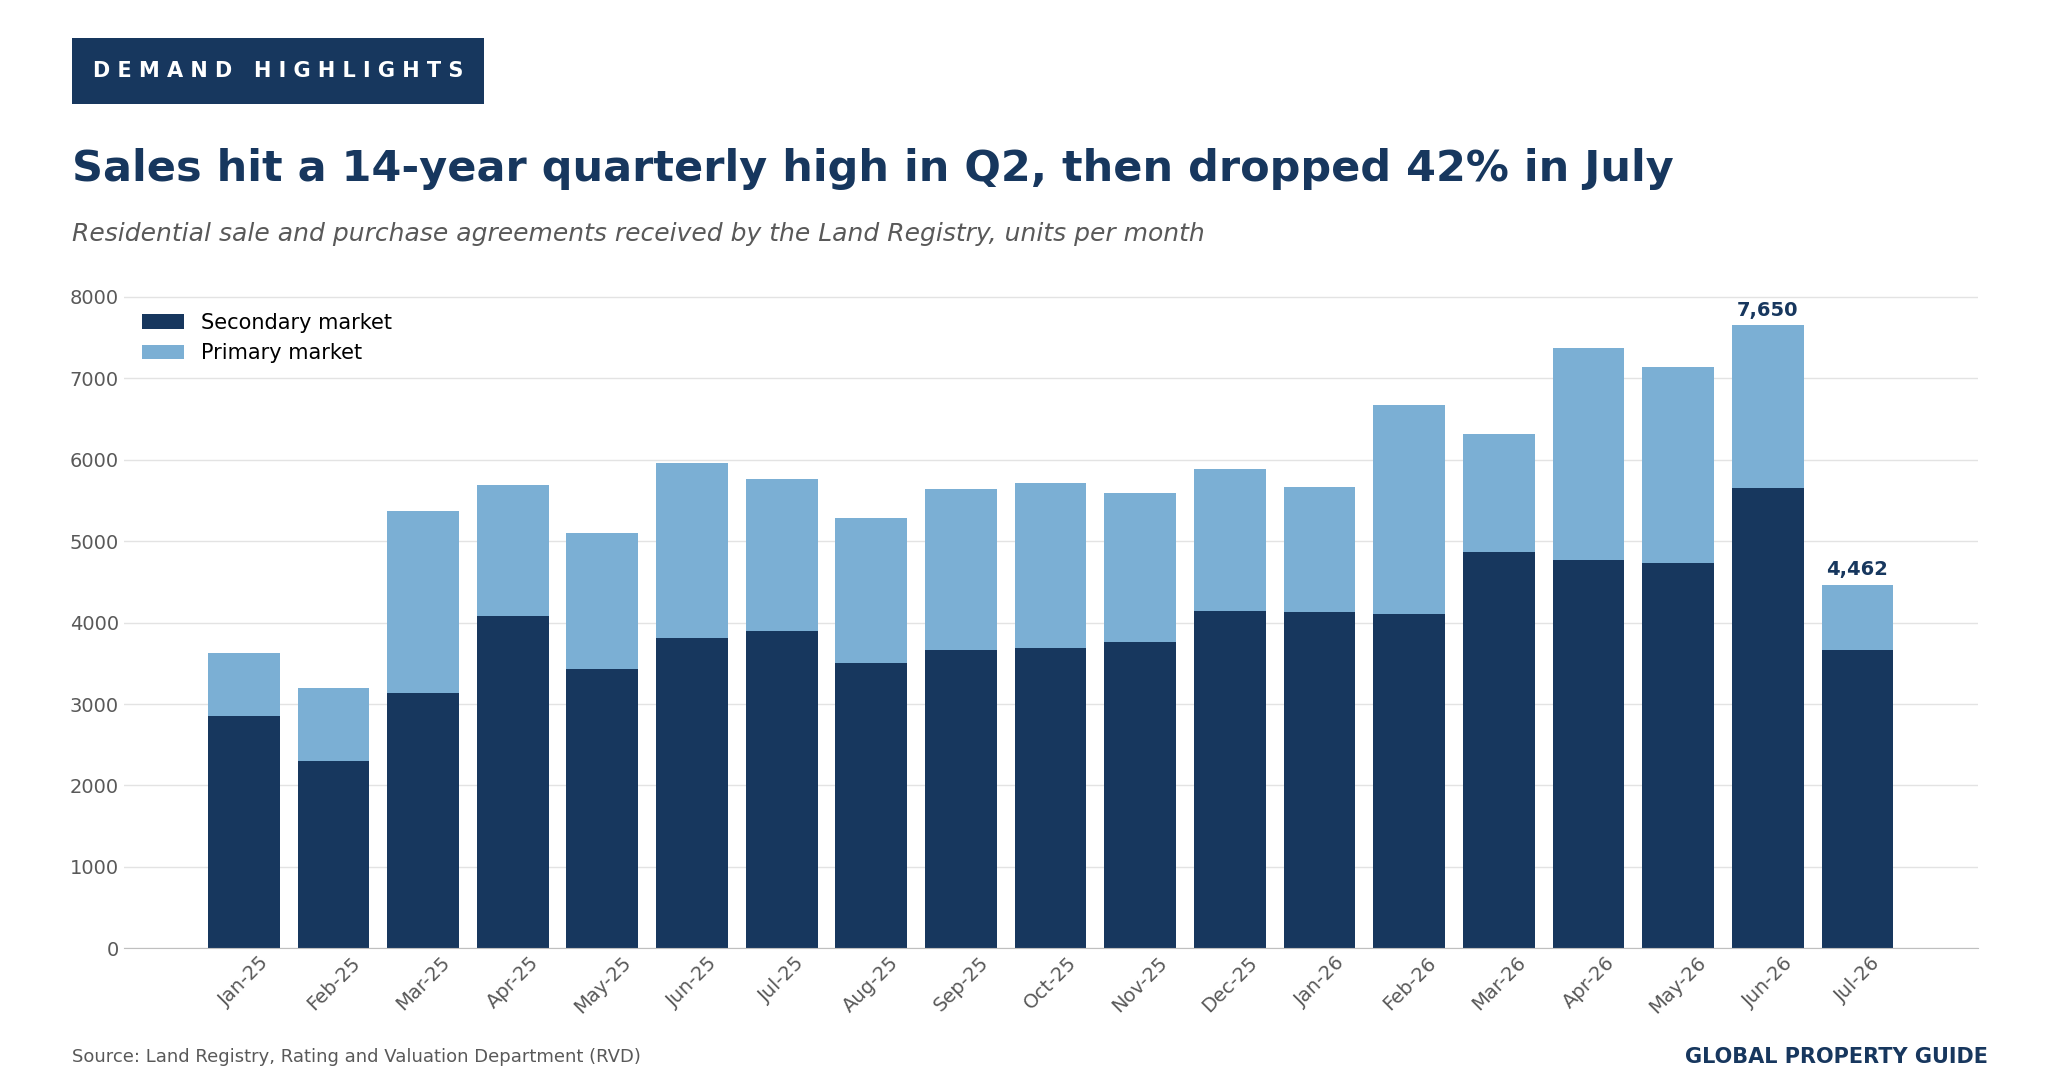
Demand surged in the first half. There were 40,810 residential sales in H1 2026, up 41% from a year earlier, and Q2 sales were the highest for any quarter in fourteen years. Then sales fell by 42% in July, to 4,462 units, as mainland Chinese buyers held back and the Hang Seng Index slipped.
Borrowing costs are now rising. On 17 September 2026, the Hong Kong Monetary Authority (HKMA) raised its base rate by 25 basis points to 4.25%, following the US Federal Reserve. Major banks kept their prime rates unchanged, but the one-month HIBOR, to which most mortgages are linked, has risen to around 3%.
The economy remains strong. Real GDP grew by 4.3% y-o-y in Q2 2026, and the government raised its full-year growth forecast to between 3.5% and 4.5%.
Note: All US dollar figures in this article use a single exchange rate, USD 1 = HKD 7.8387 (9 July 2026). Our May 2026 edition used several different conversion rates, ranging from about 7.77 to 7.84 Hong Kong dollars per US dollar, in the same article. It also stated the Fed's target range as 3.00% to 3.75% instead of 3.50% to 3.75%, and gave an inflation-adjusted quarterly price change of 1.69% for Q1 2026 that was inconsistent with official inflation data. These errors are corrected here. The Q1 2026 annual price change has also been revised by the RVD, from 9.79% to 10.21%.
Historic Perspective
Hong Kong remains the world's least affordable market as bubble risk edges up
Hong Kong's housing boom over the past decades has been driven by a combination of tight government controls on land development, historically low interest rates, and currency stability, amid a persistently limited land supply controlled by the government.
Hong Kong's currency peg to the US dollar kept borrowing costs near record lows for much of that period, fueling continued property demand.
From 2008 to 2013, Hong Kong's dwelling prices skyrocketed by 134% (95.7% inflation-adjusted), driven by a flood of money in the wake of the global financial crisis. After a brief slowdown, house prices surged again by 41.5% (35.5% inflation-adjusted) from H1 2016 to H1 2018.
The market slowed from late 2018 through 2019 amid macroeconomic uncertainties and social unrest, and struggled again in 2020 due to pandemic restrictions. In 2022, house prices plunged by 15% (-16.7% inflation-adjusted), followed by declines of 7% (-9.2% inflation-adjusted) in 2023 and 7.1% (-8.4% inflation-adjusted) in 2024. By March 2025, prices had fallen by more than 28% from their 2021 peak. In 2025, the market finally recovered, with prices rising by 3.6% (2.1% inflation-adjusted).
| HOUSE PRICE INDEX, Y-O-Y CHANGE (%) | ||
| Year | Nominal | Inflation-adjusted |
| 2009 | 28.5 | 26.5 |
| 2010 | 21.0 | 17.7 |
| 2011 | 11.1 | 5.1 |
| 2012 | 25.7 | 21.2 |
| 2013 | 7.7 | 3.3 |
| 2014 | 13.6 | 8.2 |
| 2015 | 2.4 | 0.1 |
| 2016 | 7.9 | 6.6 |
| 2017 | 14.7 | 12.8 |
| 2018 | 1.9 | -0.6 |
| 2019 | 5.5 | 2.6 |
| 2020 | 0.2 | 1.1 |
| 2021 | 3.7 | 1.3 |
| 2022 | -15.0 | -16.7 |
| 2023 | -7.0 | -9.2 |
| 2024 | -7.1 | -8.4 |
| 2025 | 3.6 | 2.1 |
| Note: December-on-December change. | ||
| Data source: Rating and Valuation Department (RVD). | ||
Despite the price falls from 2022 to 2024, Hong Kong's property market remains the least affordable in the world, according to the Demographia International Housing Affordability 2026 report. The median home price was 14.1 times the median household income in Q3 2025, down slightly from 14.4 a year earlier and well below the pre-pandemic level of 20.8 in 2019.
The UBS Global Real Estate Bubble Index 2026, published in September 2026, raised Hong Kong from low to moderate bubble risk. Real house prices in the city rose by around 10% over the past year, among the strongest increases of the cities surveyed. Hong Kong remains the least affordable city in the index, with about 15 years of average income needed to buy a 60 sq. m. flat near the city centre.
"Higher-for-longer financing costs are likely to cap house-price gains in the near term," said Matthias Holzhey, lead author of the UBS study.
Property Demand Trends
Sales hit a 14-year high in Q2, then slumped
In the second quarter of 2026, the number of residential property transactions rose by 32.2% y-o-y to 22,156 units, the highest quarterly total in fourteen years, based on Land Registry figures published by the RVD. Transaction value surged by 44.8% to HK$204.9 billion (US$26.14 billion).
In the first half of 2026, sales rose by 41% y-o-y to 40,810 units, while their value jumped by 59.5% to HK$366.9 billion (US$46.80 billion). This followed an 18.3% rise in the number of sales in 2025, to 62,832 units worth HK$519.8 billion (US$66.32 billion).
- Primary market sales rose by 34.4% y-o-y to 12,549 units in H1 2026. In Q2 alone, developers sold 6,997 units worth HK$85.9 billion (US$10.96 billion).
- Secondary market sales rose by 44.1% y-o-y to 28,261 units in H1 2026. In Q2, 15,159 units changed hands, worth HK$119.0 billion (US$15.18 billion).
Then the market cooled sharply. In July 2026, sales fell by 41.7% from June to 4,462 units, and were 22.6% lower than a year earlier. Transaction value fell by 44.6% month-on-month to HK$41.9 billion (US$5.34 billion). Primary sales dropped to just 796 units, 18% of the total.
Even so, sales in the first seven months of 2026 were still up 30.4% y-o-y, at 45,272 units.
Mainland Chinese buyers and the July outbound investment rules
Mainland Chinese buyers drove much of the rally. They spent a record of around HK$43 billion (US$5.49 billion) on Hong Kong property in Q1 2026, according to Midland Realty data, and JPMorgan estimates that they accounted for 29% of home sales by volume and 37% by value.
Two developments have since weighed on that demand. China's new rules on outbound investment took effect on 1 July 2026, tightening scrutiny of money moved offshore by mainland residents. Concern has also grown over how a 20% tax on some offshore income of mainland residents may be applied. At the same time, the Hang Seng Index fell by 7.7% in Q2 2026, according to the government.
Eddie Kwok of CBRE Hong Kong said in late August that further upside was likely to be limited after this year's gains, and that the market was likely to enter "a consolidation phase in the coming months," according to the South China Morning Post.
Cooling measures gone, top-end stamp duty raised
Hong Kong has removed almost all of its property cooling measures in recent years.
Under the 2026-27 Budget, the government raised the ad valorem stamp duty rate on residential property transactions valued above HK$100 million (US$12.76 million) from 4.25% to 6.5%, effective 26 February 2026. Authorities said the change would affect only around 0.3% of residential transactions. Also from March 2026, new regulatory standards for Basic Housing Units took effect, requiring subdivided flats to meet minimum standards such as windows and private sanitary facilities.
In September 2025, the government revised the New Capital Investment Entrant Scheme (New CIES), lowering the minimum residential property price eligible for investment from HK$50 million (US$6.38 million) to HK$30 million (US$3.83 million), and raising the maximum property investment that counts toward the scheme from HK$10 million (US$1.28 million) to HK$15 million (US$1.91 million).
In May 2025, the Stamp Duty (Amendment) Bill 2025 raised the maximum property value subject to the minimum stamp duty of HK$100 (US$13) from HK$3 million (US$382,717) to HK$4 million (US$510,289), for transactions on or after 26 February 2025.
In October 2024, the HKMA removed most countercyclical macroprudential measures for mortgages, standardizing the maximum loan-to-value ratio at 70% and raising the debt-servicing ratio cap to 50% for most residential mortgages.
Earlier, in February 2024, Hong Kong removed all extra stamp duties: the Buyer's Stamp Duty on non-permanent residents, the New Residential Stamp Duty on second-time buyers, and the Special Stamp Duty on homes resold within two years. This followed a partial easing in October 2023, the first relaxation of the cooling measures in more than a decade.
Earlier rounds of cooling measures
Before these relaxations, the government had introduced several rounds of cooling measures to curb speculation:
- In November 2010, the government imposed a 15% flip tax on properties resold within six months, and doubled stamp duties to 8.5% on properties worth HK$20 million (US$2.55 million) or more.
- In October 2012, it imposed a 15% extra tax on property purchases by foreigners.
- In February 2013, it doubled the stamp duty on all property transactions worth more than HK$2 million (US$255,144). This measure ended in May 2014.
- In February 2015, buyers of self-used residential properties valued under HK$7 million (US$893,005) were required to make larger down payments.
- In November 2016, stamp duties for all property transactions were raised to 15%, except for first-time buyers, who paid 4.25%.
- In May 2017, the HKMA limited bank lending to developers to 40% of a site's value, down from 50%.
- In June 2018, the government introduced a vacancy tax on unsold new homes left unoccupied six months after completion.
Property Supply Trends
Completions running behind forecast
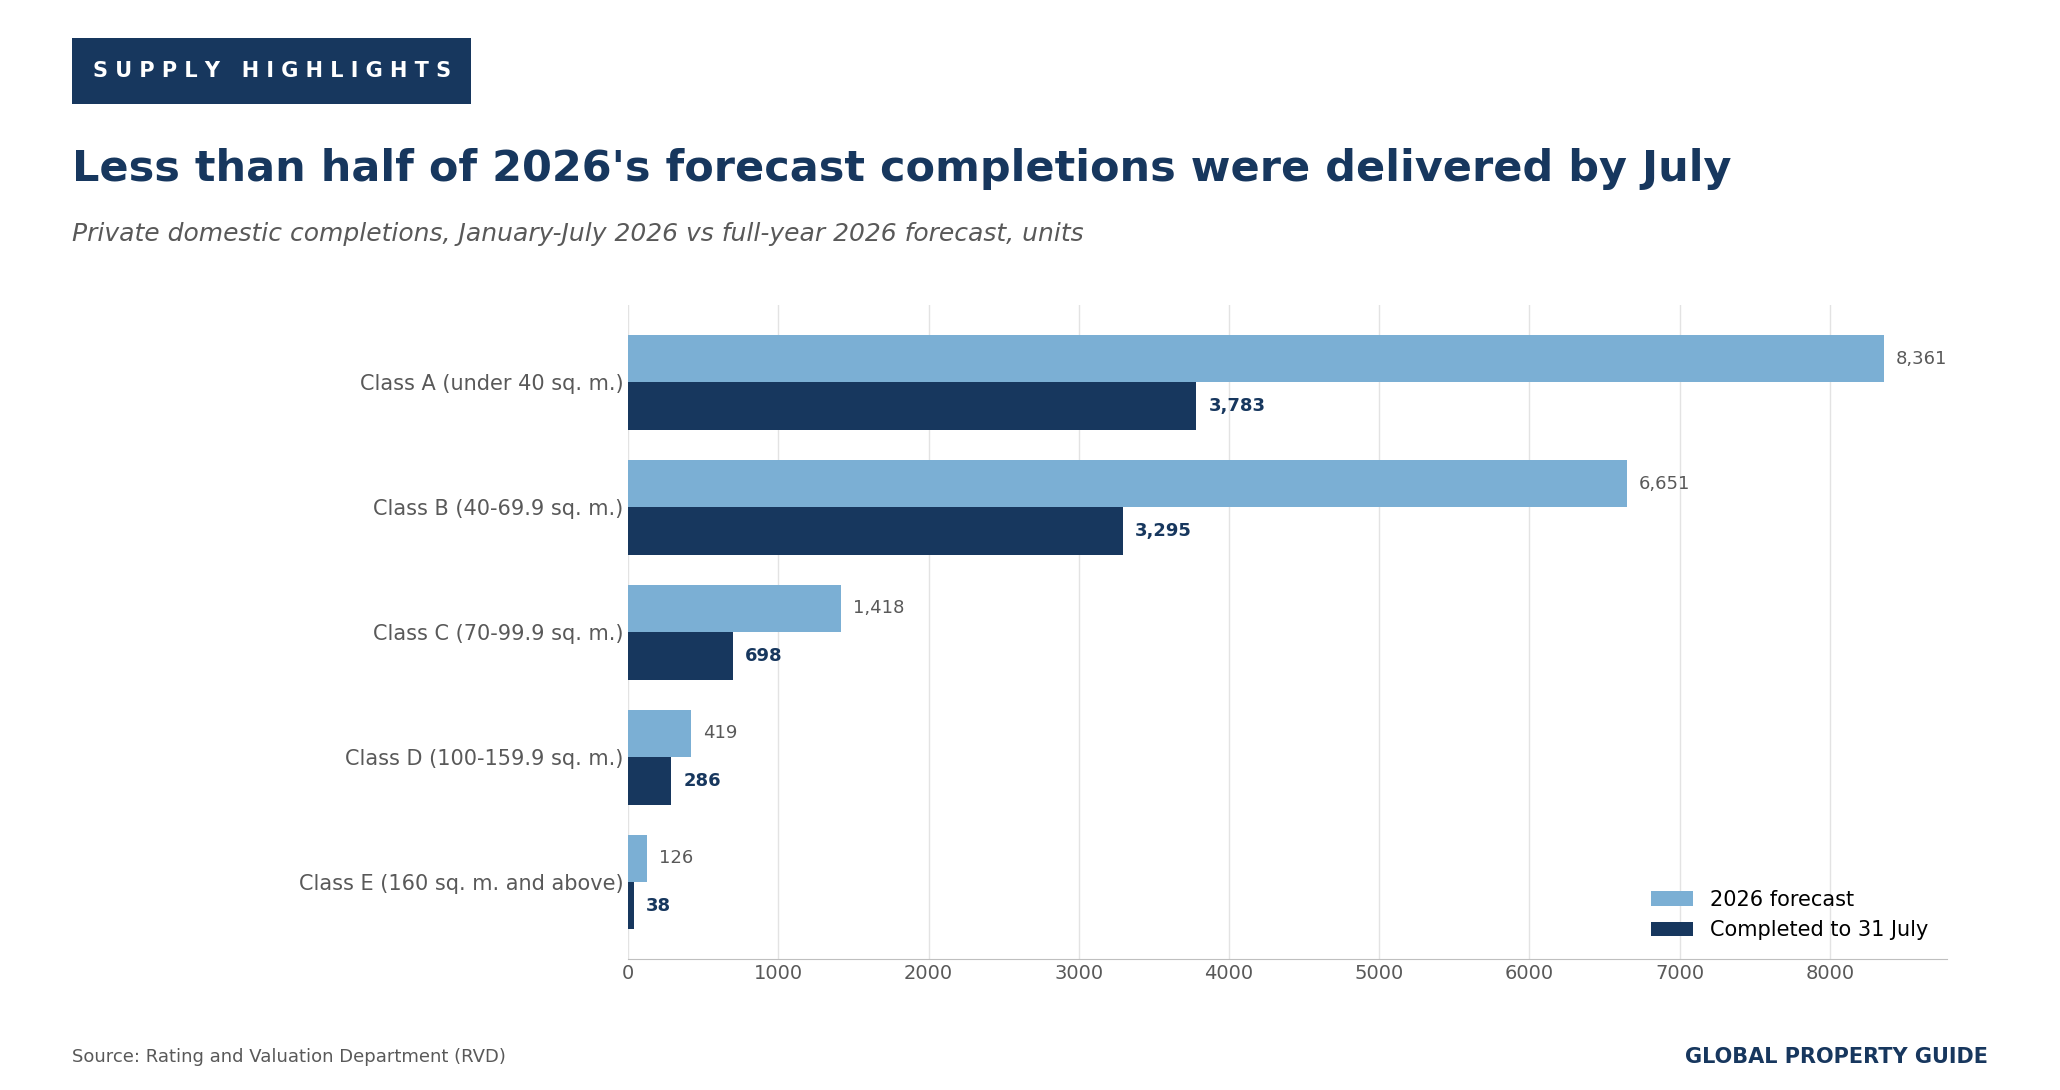
Residential completions totaled 8,100 units in the first seven months of 2026, only 48% of the 16,975 units the RVD forecast for the full year, according to the RVD. The New Territories accounted for 62% of the new units, and 47% were small flats of less than 40 sq. m.
By property class, completions from January to July 2026 were:
- Class A (less than 40 sq. m.): 3,783 units, against a full-year forecast of 8,361
- Class B (40 to 69.9 sq. m.): 3,295 units, against a forecast of 6,651
- Class C (70 to 99.9 sq. m.): 698 units, against a forecast of 1,418
- Class D (100 to 159.9 sq. m.): 286 units, against a forecast of 419
- Class E (160 sq. m. and above): 38 units, against a forecast of 126
In 2025, residential completions fell by 24% y-o-y to 18,448 units, after a 75.1% increase in 2024. Class A units made up 9,859 of the total, Class B 6,565, Class C 1,245, Class D 614, and Class E 165.
The stock of private housing rose by 1.3% to 1,309,265 units in 2025, according to the RVD. Class A flats numbered 427,993, Class B 624,325, Class C 156,182, Class D 71,551 and Class E 29,214.
Including public housing, the total stock of flats was 3,106,000 units in 2025, up 1.6% from 3,056,000 units a year earlier, according to the Hong Kong in Figures 2026 report. Of these, 1,344,000 units were public permanent housing, and 1,762,000 were private housing.
Tackling Hong Kong's long-standing housing shortage
In its Long Term Housing Strategy (LTHS) Annual Progress Report 2025, the government set a 10-year housing supply target of 420,000 units for 2026-27 to 2035-36, in line with projected demand of 419,100 units. The target is split 70:30 between public and private housing, giving 294,000 public units and 126,000 private units. Of the public units, 176,000 are to be public rental or Green Form flats and 118,000 subsidised sale flats.
The Housing Bureau has set four directions for housing policy: encouraging residents to move up the housing ladder, making better use of existing public housing, improving the cost-effectiveness of public housing construction, and implementing the regulatory regime for Basic Housing Units.
Two large projects could add substantially to the housing stock over the coming decades. The Northern Metropolis, next to Shenzhen, would add more than 900,000 homes over two decades, and Lantau Vision Tomorrow would add more than 200,000 homes on reclaimed islands near the airport, according to Demographia.
The government also launched a HK$26.4 billion (US$3.37 billion) Light Public Housing programme in 2023 to build about 30,000 temporary flats over five years, as an interim option for households waiting for public rental housing.
Rental Market: Rents and Rental Yields
Rents at a record high
Hong Kong rents have kept rising even as prices stalled. The RVD rental index rose by 1.64% month-on-month to a record 210.3 in August 2026, its tenth consecutive monthly increase, according to the RVD. Rents were up 4.89% in the first eight months of the year.
Hong Kong's rent price index:
In Q2 2026, the rental index was 4.78% higher than a year earlier. Rents for mid-sized and large flats rose fastest:
- Class A (less than 40 sq. m.): up 3.33% y-o-y
- Class B (40 to 69.9 sq. m.): up 4.96% y-o-y
- Class C (70 to 99.9 sq. m.): up 7.25% y-o-y
- Class D (100 to 159.9 sq. m.): up 7.87% y-o-y
- Class E (160 sq. m. and above): up 5.47% y-o-y
| AVERAGE RENTS, Q2 2026 | ||||||
| Property size | Hong Kong, HKD (USD) per sq. m. per month |
Kowloon, HKD (USD) per sq. m. per month |
New Territories, HKD (USD) per sq. m. per month |
Hong Kong, y-o-y % |
Kowloon, y-o-y % |
New Territories, y-o-y % |
| Less than 40 sq. m. | 514 (66) |
447 (57) |
350 (45) |
5.8 | 5.2 | 3.6 |
| 40 to 69.9 sq. m. | 432 (55) |
393 (50) |
288 (37) |
5.9 | 7.1 | 4.0 |
| 70 to 99.9 sq. m. | 463 (59) |
426 (54) |
290 (37) |
6.4 | 11.8 | 3.9 |
| 100 to 159.9 sq. m. | 465 (59) |
411 (52) |
265 (34) |
8.6 | 12.6 | 8.6 |
| 160 sq. m. and above | 449 (57) |
536* (68) |
249 (32) |
-1.8 | 50.1* | 14.2 |
| Note: Q2 2026 figures are provisional. *Fewer than 20 transactions. | ||||||
| Data source: Rating and Valuation Department (RVD). | ||||||
Rental yields are compressing
Hong Kong's rental yields remain very low by international standards. Hong Kong is not a typical market: like Monaco and Singapore, it is a place where the wealthy hold apartments as part of a diversified asset strategy, and such markets tend to have lower yields.
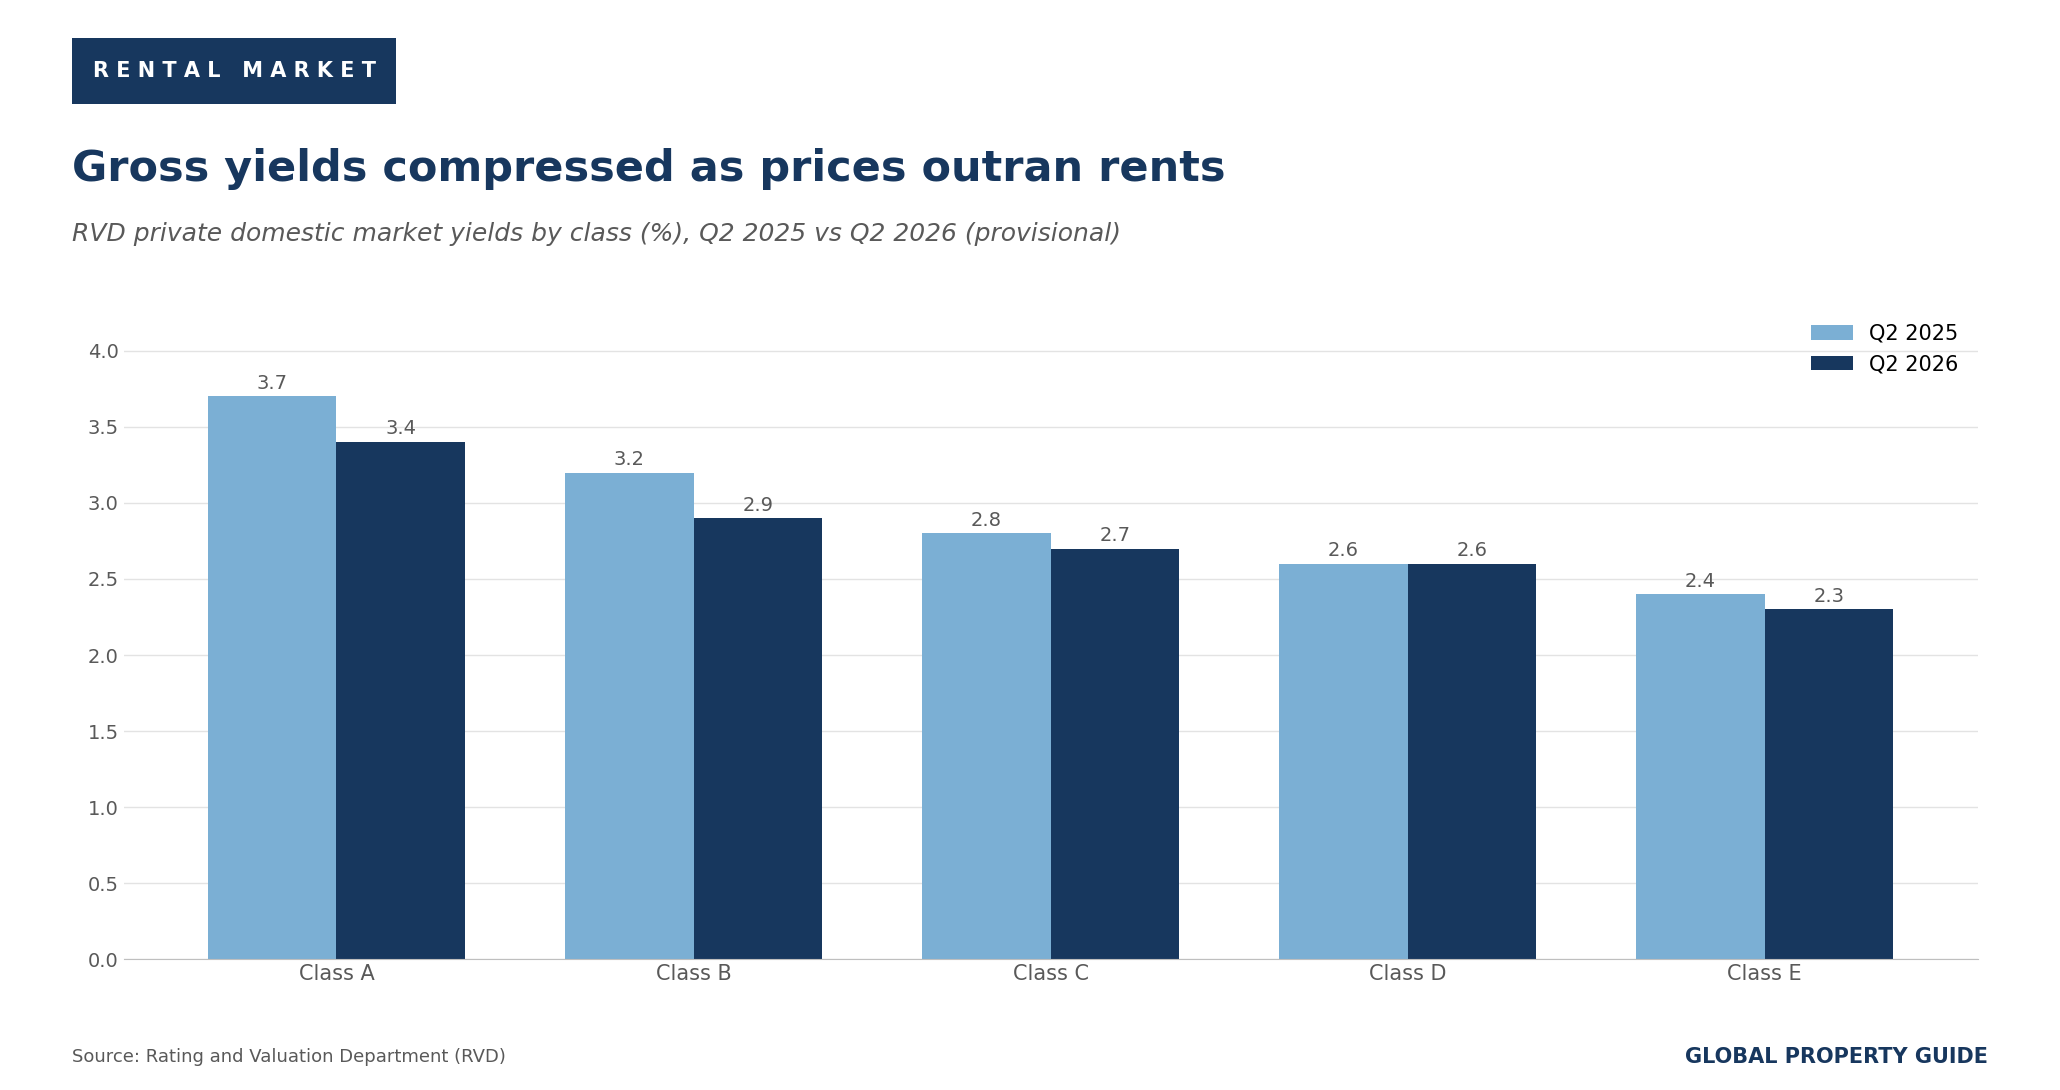
With prices rising faster than rents over the past year, yields have tightened further. RVD market yields in Q2 2026 were:
- Class A (less than 40 sq. m.): 3.4%, down from 3.7% a year earlier
- Class B (40 to 69.9 sq. m.): 2.9%, down from 3.2%
- Class C (70 to 99.9 sq. m.): 2.7%, down from 2.8%
- Class D (100 to 159.9 sq. m.): 2.6%, unchanged
- Class E (160 sq. m. and above): 2.3%, down from 2.4%
Research by the Global Property Guide found an average gross rental yield of 3.55% in Hong Kong in Q1 2026, down from 3.9% in Q2 2025. By major area in Q1 2026:
- New Territories: yields ranged from 2.66% to 4.51%, with an average of 3.52%.
- Kowloon: yields ranged from 2.14% to 4.82%, with an average of 3.6%.
- Hong Kong Island: yields ranged from 3.32% to 4.14%, with an average of 3.69%.
- Outlying Islands: yields ranged from 3.32% to 3.46%, with an average of 3.39%.
Mortgage Market and Interest Rates
First rate hike since 2023
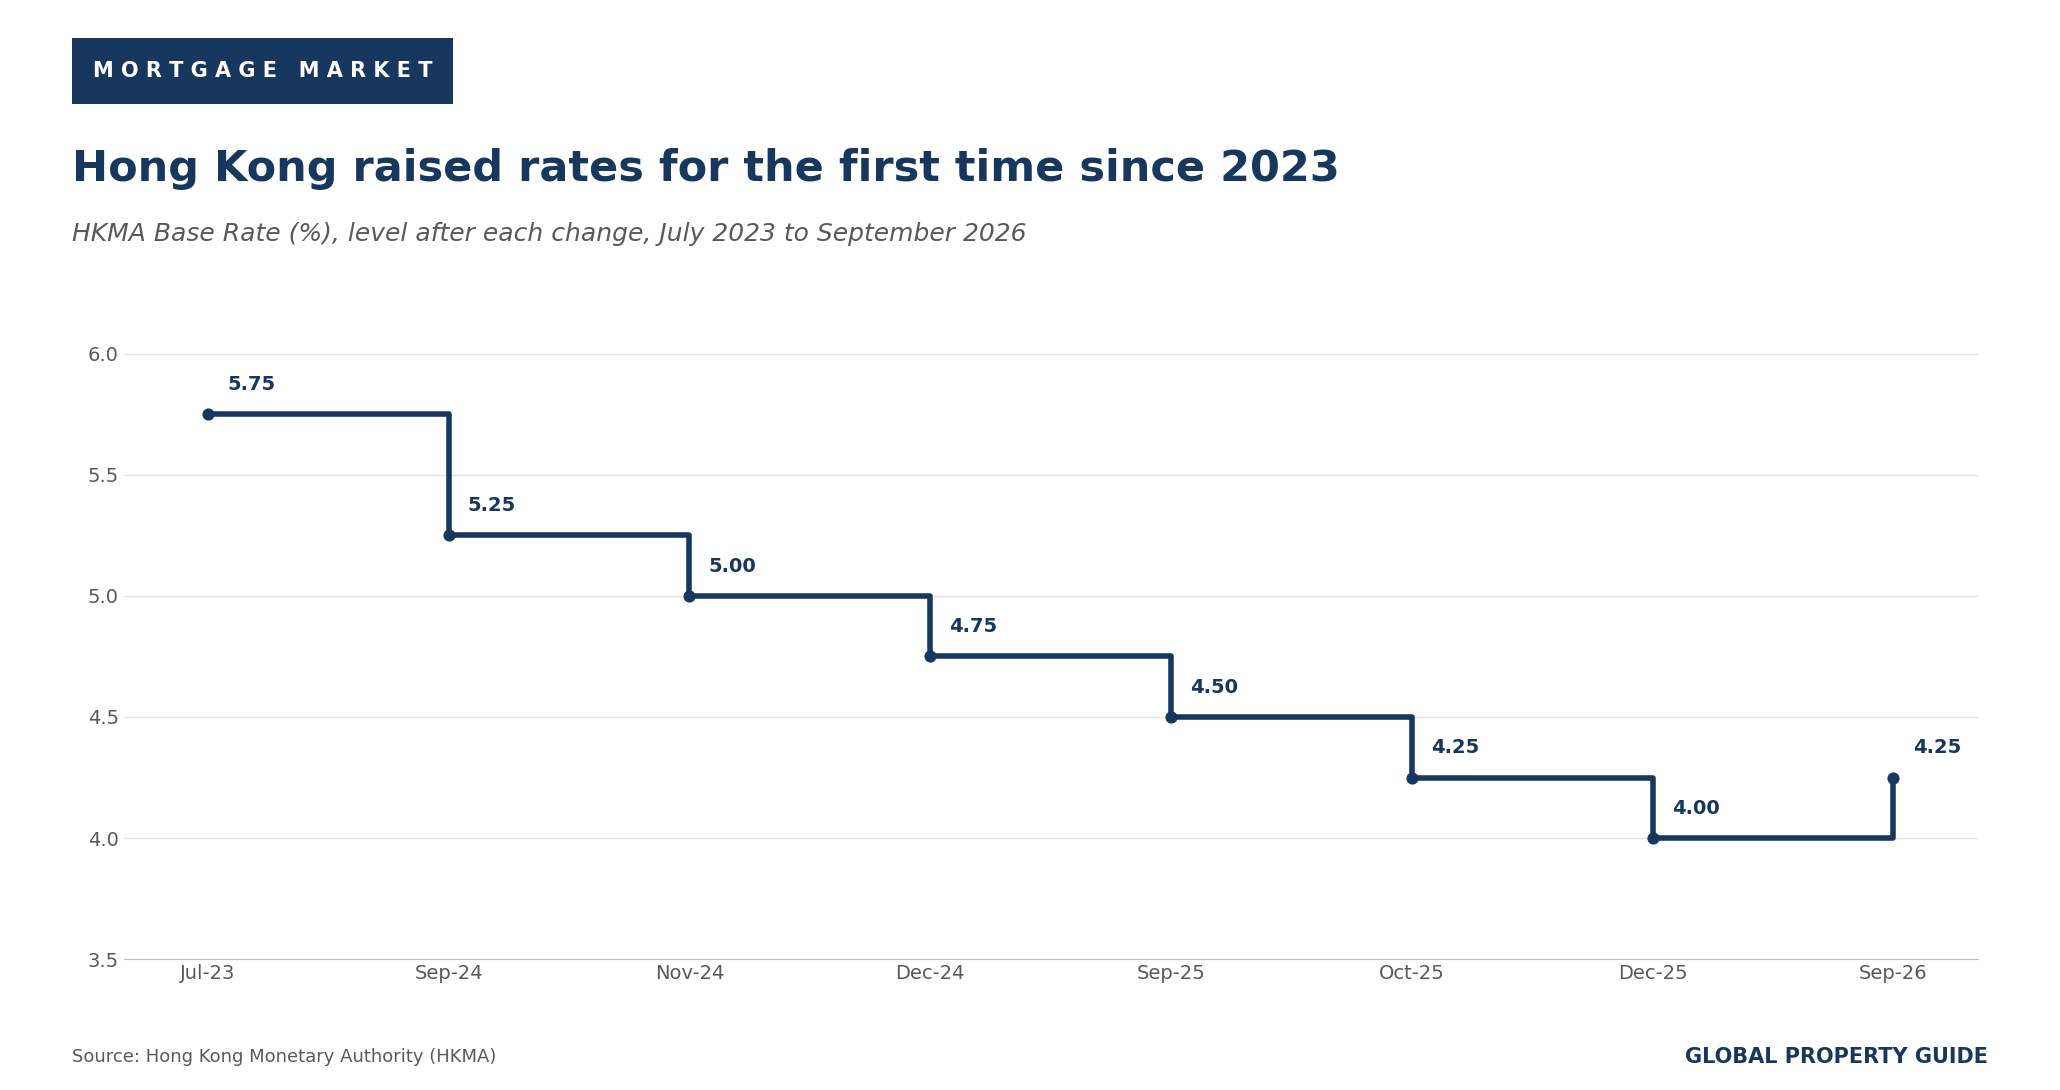
On 17 September 2026, the HKMA raised its base rate by 25 basis points to 4.25%, a day after the US Federal Reserve lifted its target range to 3.75% to 4.00%. It was Hong Kong's first rate increase since July 2023.
Hong Kong's mortgage loan interest rates:
Because the Hong Kong dollar has been pegged to the US dollar since 1983, the HKMA sets its base rate by formula at 50 basis points above the lower end of the Fed's target range, or at the average of the overnight and one-month HIBORs if that is higher. Before the hike, the base rate had stood at 4.00% since December 2025, when the Fed's range was 3.50% to 3.75%. It had been cut six times from September 2024 to December 2025, from 5.75%.
Major banks did not pass the increase on. HSBC and Bank of China (Hong Kong) kept their prime lending rates at 5.00%, and Standard Chartered kept its rate at 5.25%, according to market reports.
Most new mortgages are priced off the one-month HIBOR rather than the prime rate. The one-month HIBOR rose to 2.99048% on 25 September 2026, according to Public Bank (Hong Kong), up from 2.44238% at the end of April. The share of new mortgages priced with reference to HIBOR fell from 70% in June to 61% in July.
Mortgage lending cooled in July
In July 2026, the number of mortgage applications fell by 24% month-on-month to 9,212, and the value of new mortgage loans approved fell by 11.4% to HK$44.8 billion (US$5.72 billion), according to the HKMA's residential mortgage survey. This followed a strong June, when applications reached 12,117 and approvals reached HK$50.6 billion.
Of the July approvals, HK$13.3 billion financed primary market purchases, HK$24.2 billion secondary market purchases, and HK$7.3 billion refinancing.
The value of outstanding mortgage loans rose by 0.4% month-on-month to HK$1,963.5 billion (US$250.49 billion) at the end of July. The delinquency ratio stood at a low 0.11%.
The recovery in prices has sharply reduced negative equity. The number of mortgages in negative equity fell by 61.9% to 4,356 at the end of June 2026, from 11,424 at the end of March, and their value fell by 64.4% to HK$19.6 billion (US$2.50 billion), according to the HKMA.
Fixed-rate mortgage scheme
The Hong Kong Mortgage Corporation (HKMC) offers fixed-rate mortgages for 10, 15 and 20 years, with a maximum loan of HK$10 million (US$1.28 million). The scheme began as a pilot in 2020 and was made permanent in November 2021. At the end of the fixed-rate period, borrowers can re-fix their rate or switch to a floating-rate loan. The HKMC announces its fixed rates monthly.
| FIXED-RATE MORTGAGE SCHEME RATES WHEN MADE PERMANENT (NOVEMBER 2021 TO JANUARY 2022) | ||
| Fixed-rate period | Fixed interest rate | Prepayment penalty (% of amount prepaid) |
| 10-year | 1.99% | Year 1: 3%, Year 2: 2%, Year 3: 1% |
| 15-year | 2.09% | Year 1: 3%, Year 2: 2%, Year 3: 1% |
| 20-year | 2.19% | Year 1: 3%, Year 2: 2%, Year 3: 1% |
| Data source: HKMC. | ||
Economic and Social Factors
Growth slowed in Q2, but the forecast was raised
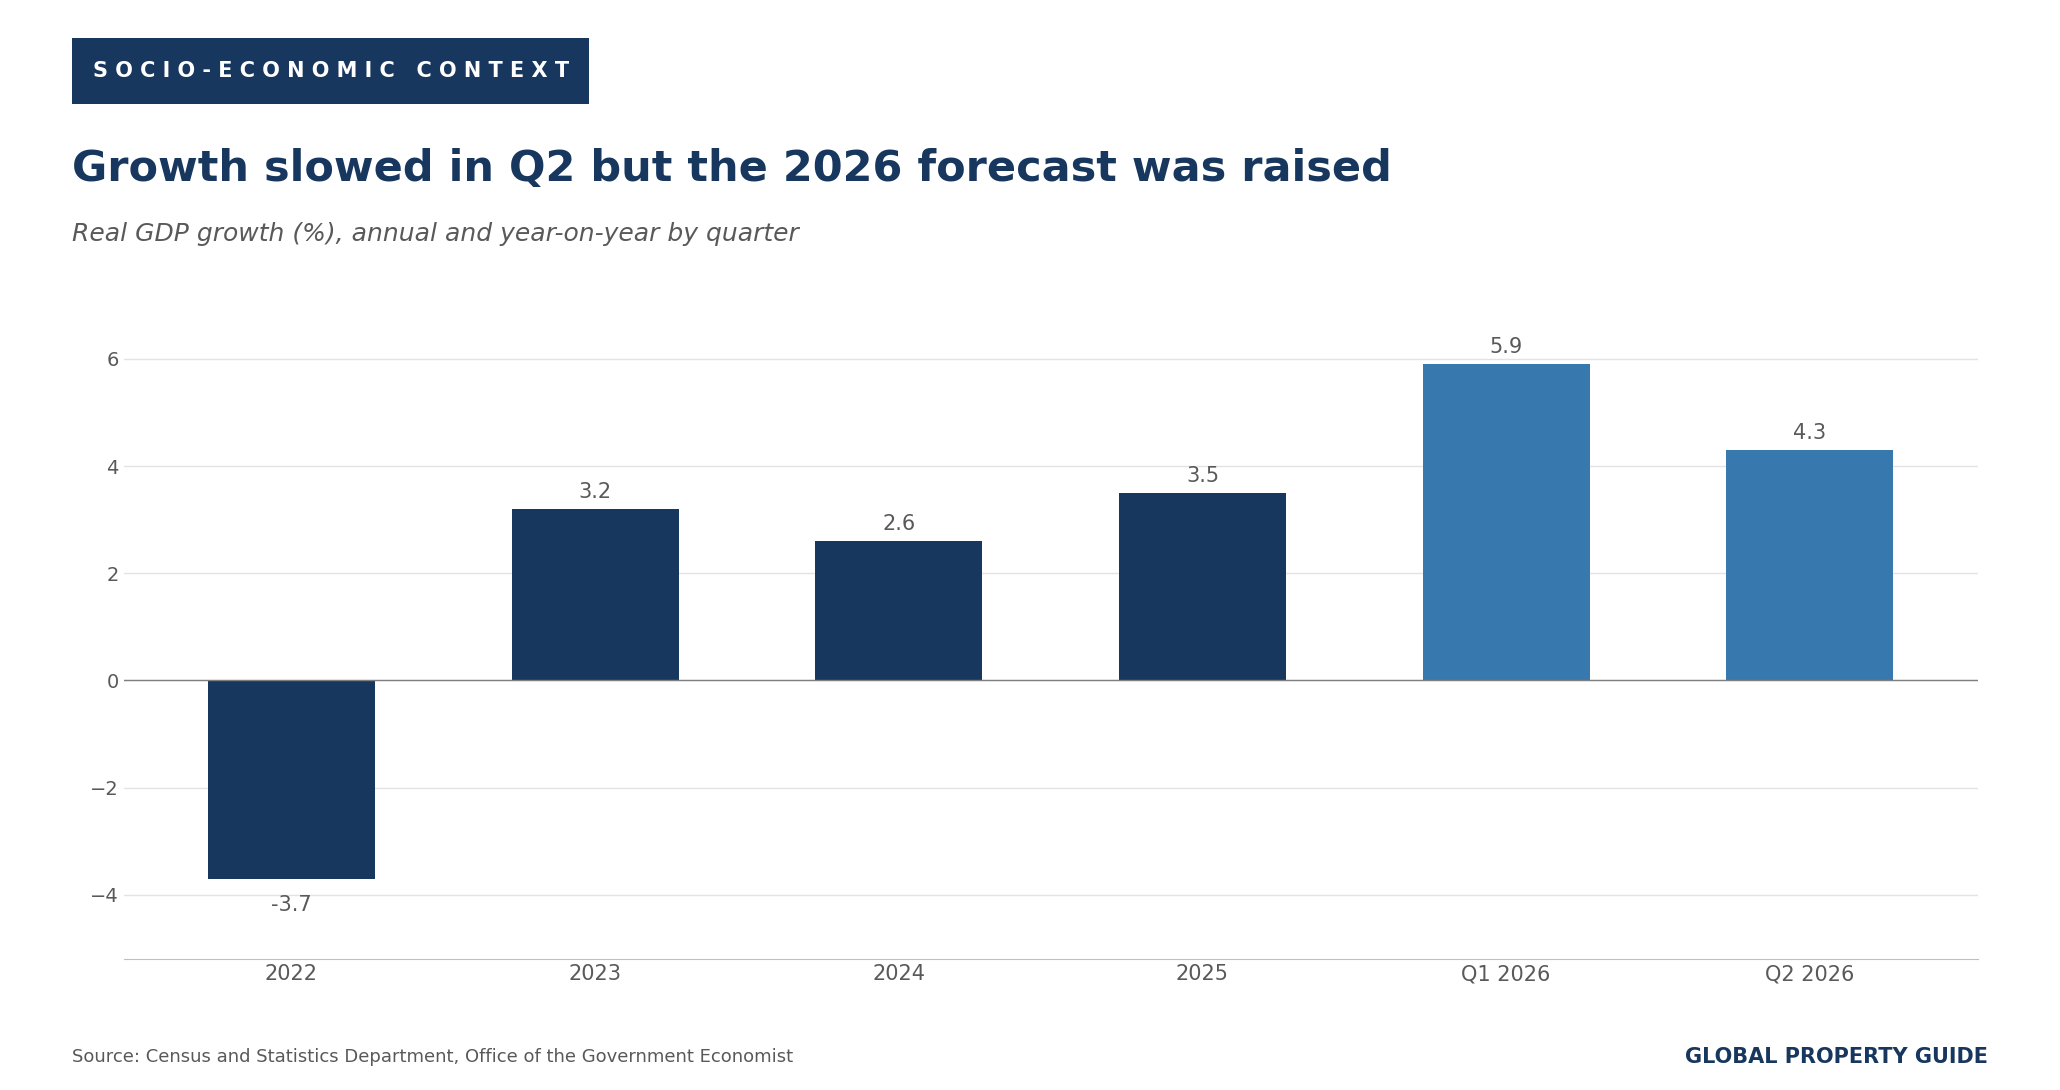
Hong Kong's economy grew by 4.3% y-o-y in Q2 2026, following 5.9% growth in Q1, according to the government. It was the fourteenth consecutive quarter of y-o-y growth. For the first half, GDP grew by 5.1%, the strongest half-year in nearly five years. On a seasonally adjusted quarterly basis, however, GDP fell by 0.6% in Q2, the first quarterly decline since Q3 2022.
In the second quarter of 2026:
- Goods exports surged by 28.9% y-o-y in real terms, up from 23.8% in Q1, driven by global demand for AI-related electronics.
- Services exports rose by 3.4%.
- Private consumption grew by 2.8%, down from 4.9% in Q1.
- Investment rose by 4.4%, down from 18.3% in Q1.
The government raised its 2026 growth forecast to between 3.5% and 4.5%, from 2.5% to 3.5% previously. The economy grew by 3.5% in 2025, 2.6% in 2024 and 3.2% in 2023, after contracting by 3.7% in 2022.
Inflation moderate, unemployment edging up
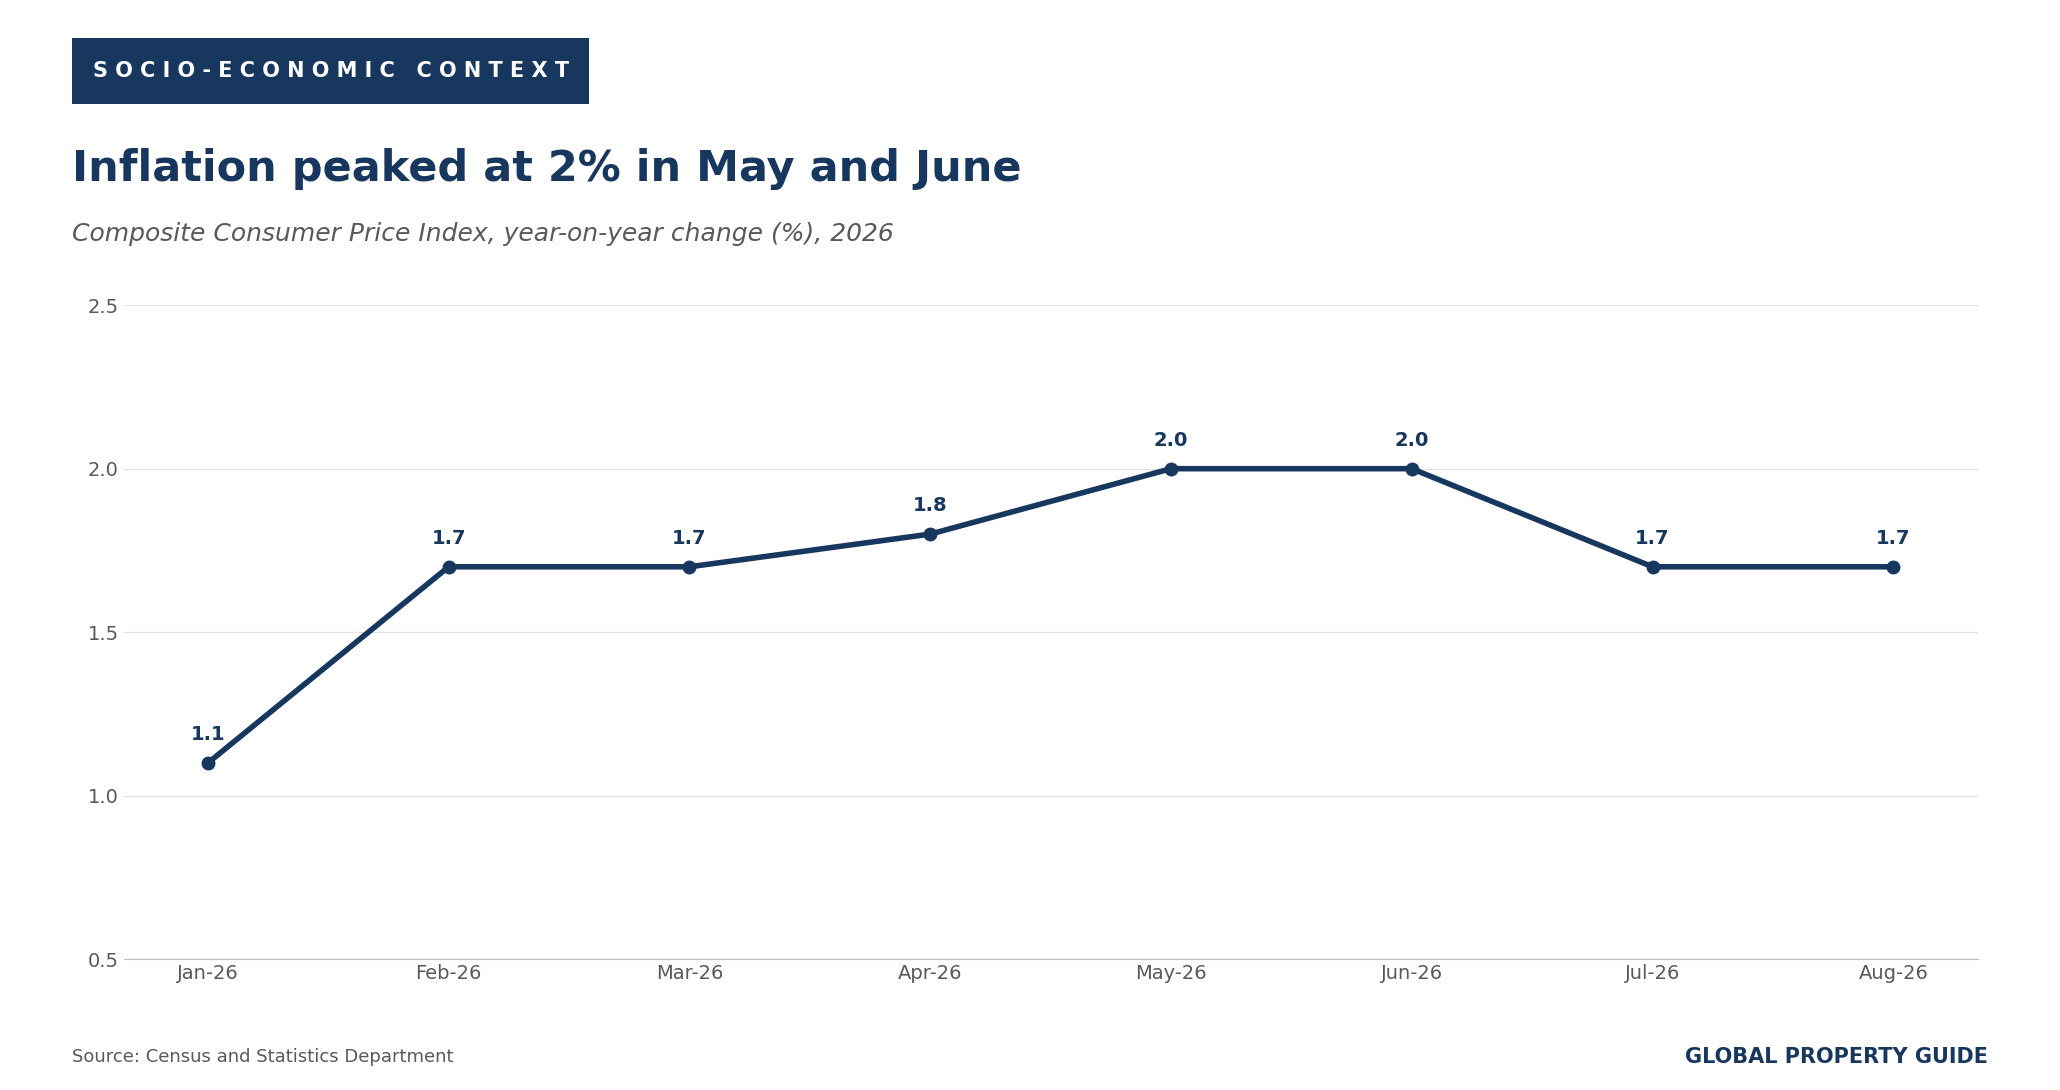
Inflation was 1.7% in August 2026, unchanged from July and down from a peak of 2.0% in May and June, according to the Census and Statistics Department. Utility and transport prices rose fastest, reflecting higher oil prices. The government expects headline inflation of 2.6% for 2026 as a whole. Inflation averaged 1.7% in 2024 and 1.4% in 2025.
The seasonally adjusted unemployment rate rose to 3.8% in June to August 2026, from 3.7% in the previous five periods, according to official data. The number of unemployed people rose to 153,900.
Tourism continues to recover
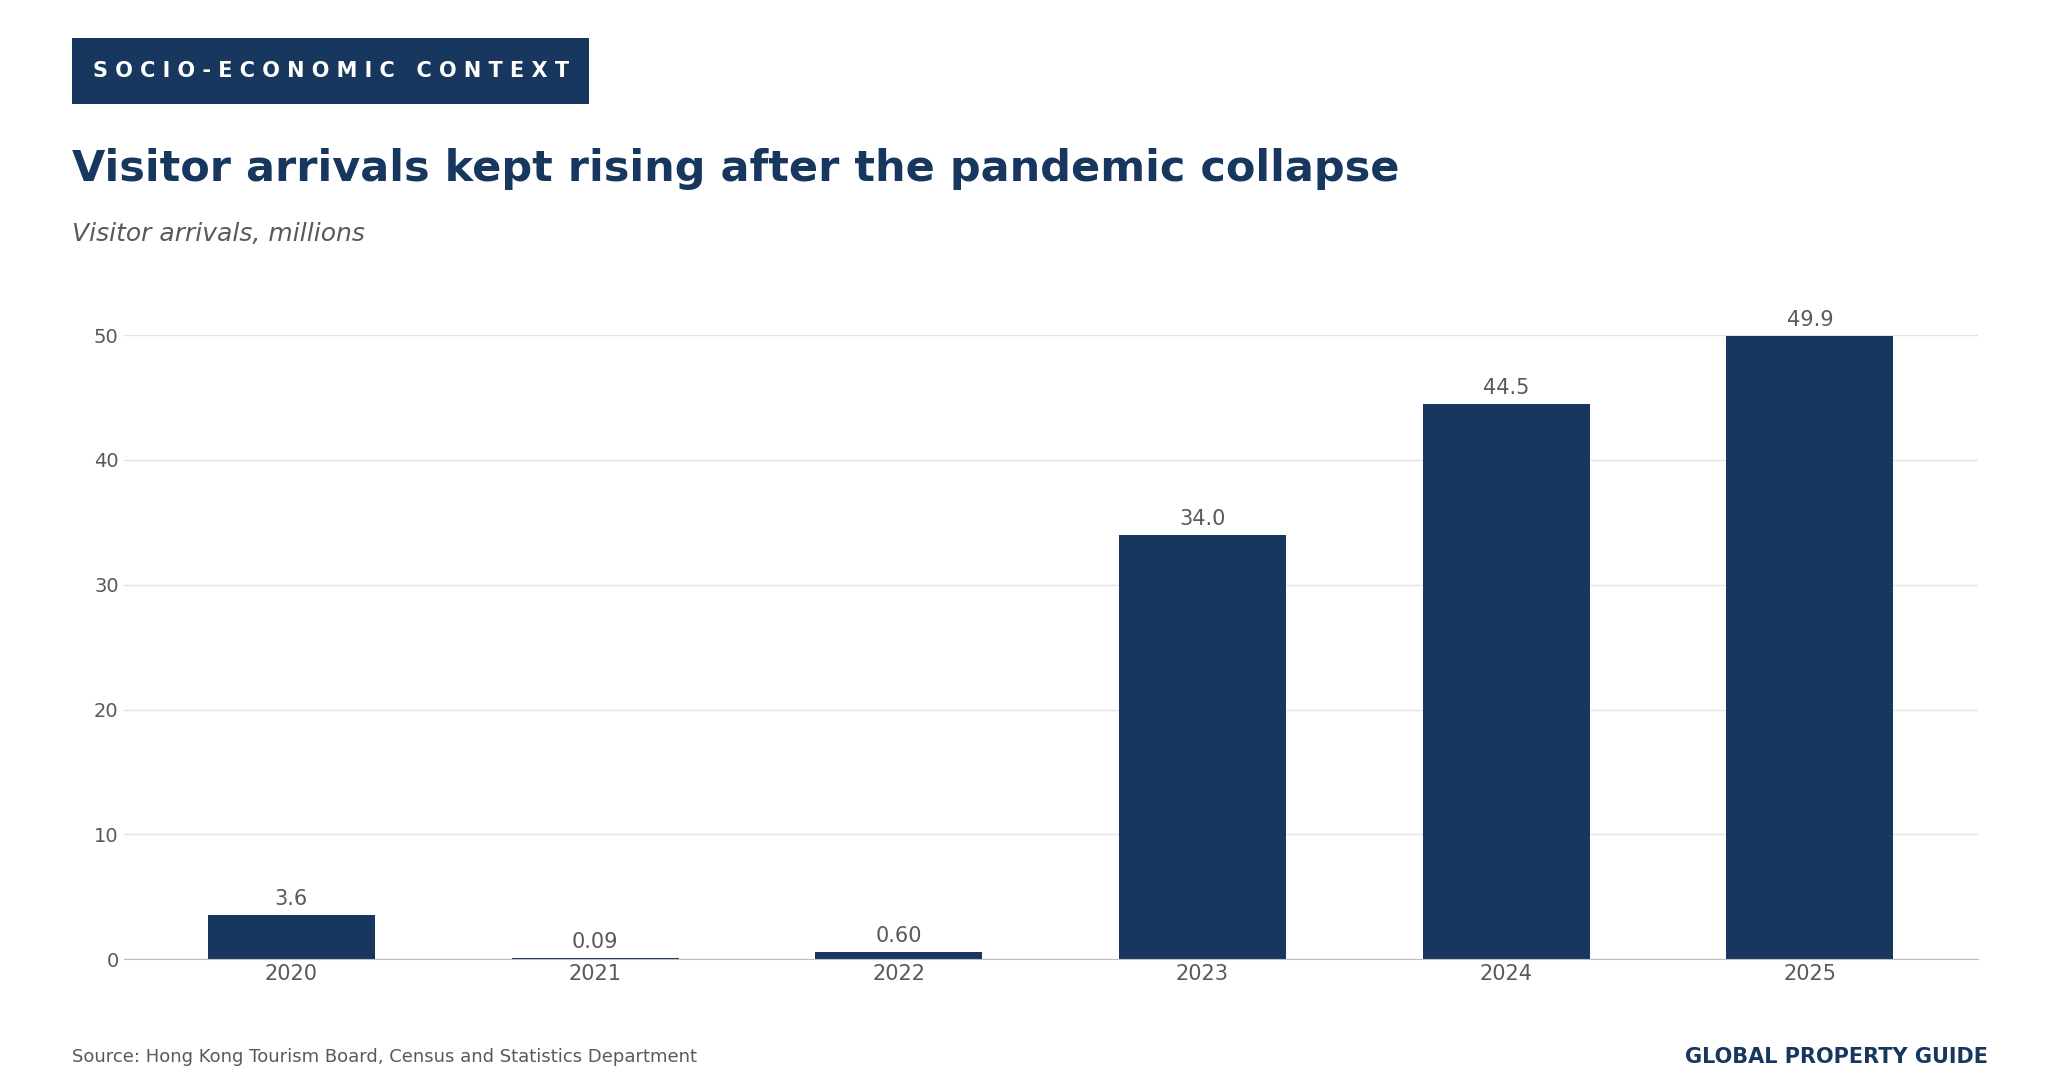
Hong Kong welcomed 36.67 million visitors in the first eight months of 2026, up 11% from a year earlier, according to the Hong Kong Tourism Board. August arrivals of 5.46 million were the highest monthly total since the pandemic. In the first half, visitors from Mainland China rose by 16% to 20.56 million.
In 2025, visitor arrivals rose by 12.1% to 49.9 million, still about 23% below the record 65.1 million in 2018.
Sources:
- Property Market Statistics (Rating and Valuation Department): rvd.gov.hk
- Hong Kong Property Review Monthly Supplement, September 2026 (Rating and Valuation Department): rvd.gov.hk
- Private Domestic Price Indices by Class, Monthly (Rating and Valuation Department): rvd.gov.hk
- HK home prices edge up in August, rent hits new high (The Standard): thestandard.com.hk
- Hong Kong home prices edge higher in August as rents hit a record (Dimsum Daily): dimsumdaily.hk
- Hong Kong remains the world's most expensive housing market (Time Out Hong Kong): timeout.com
- UBS Global Real Estate Bubble Index 2026 (UBS): ubs.com
- Demographia International Housing Affordability 2025 Edition (Chapman University): chapman.edu
- Chinese Curbs Risk Derailing Record Hong Kong Home-Buying Spree (Bloomberg): bloomberg.com
- Hong Kong home prices end 13-month upswing (South China Morning Post): scmp.com
- On Sale or Transfer of Immovable Property in Hong Kong (GovHK): gov.hk
- New measures, New Capital Investment Entrant Scheme (InvestHK): newcies.gov.hk
- LegCo passes stamp duty bill to ease burden on HK low-end home buyers (China Daily): chinadailyhk.com
- Countercyclical macroprudential measures for property mortgage loans (HKSAR Government): info.gov.hk
- Hong Kong Budget 2024: Extra stamp duties axed (Hong Kong Free Press): hongkongfp.com
- Hong Kong slashes stamp duties, easing property curbs for the first time in over 10 years (CNBC): cnbc.com
- Hong Kong in Figures 2026 Edition (Census and Statistics Department): censtatd.gov.hk
- Long Term Housing Strategy Annual Progress Report 2025 (HKSAR Government): info.gov.hk
- Gross rental yields in Hong Kong (Global Property Guide): globalpropertyguide.com
- Adjustment of Base Rate, 17 September 2026 (Hong Kong Monetary Authority): hkma.gov.hk
- HKMA at 4.25%: Why Hong Kong Banks Kept Prime Rates Unchanged (EBC Financial Group): ebc.com
- HIBOR (Public Bank, Hong Kong): publicbank.com.hk
- Residential Mortgage Survey Results for July 2026 (Rica Mortgage, reproducing HKMA): ricamortgage.com
- Residential mortgage loans in negative equity: End of June 2026 (HKSAR Government): info.gov.hk
- Permanent Offer of Fixed-rate Mortgage Scheme (Hong Kong Monetary Authority): hkma.gov.hk
- Fixed Rate Mortgage Scheme (Hong Kong Mortgage Corporation): hkmc.com.hk
- Economic performance in second quarter of 2026 (HKSAR Government): info.gov.hk
- Consumer Price Indices for August 2026 (Census and Statistics Department): censtatd.gov.hk
- Hong Kong's jobless rate rises to 3.8 percent (The Standard): thestandard.com.hk
- Hong Kong visitor arrivals, first eight months of 2026 (The Standard): thestandard.com.hk