China's Residential Property Market Analysis 2026
China has begun to dismantle the presale model that financed two decades of housing construction. The August data show the price decline narrowing in the four tier-1 cities, unsold inventory falling, and resale volumes overtaking new-home sales, but national prices are still lower than a year ago.
This extended overview from Global Property Guide covers key aspects of the Chinese housing market and takes a closer look at its most recent developments and long-term trends.
Table of Contents
- Property Prices and Price Index
- Historic Perspective
- Property Demand Trends
- Property Supply Trends
- Rental Market: Rents and Rental Yields
- Mortgage Market and Interest Rates
- Economic and Social Factors
Property Prices and Price Index
The most important change since our May 2026 edition is not a price reading but a change to how Chinese homes are sold. On 28 August, the Ministry of Housing and Urban-Rural Development (MOHURD), the Ministry of Natural Resources and the National Financial Regulatory Administration (NFRA) jointly directed local governments to prioritize sales of completed homes on newly sold residential land and on previously sold plots without construction planning permits. Where presales continue, each building must reach structural completion before units can be marketed, and buyers' funds must be held in regulated accounts. On the same day, the People's Bank of China (PBOC) and the NFRA ruled that mortgages on presold homes may be disbursed only after a project's completion is registered, and raised the maximum mortgage term from 30 to 40 years.
China's house price annual change:
Our previous edition described policy support as gradual and focused on demand. The August package goes further: it moves construction risk from homebuyers to developers and banks. Projects that already held construction permits on 28 August keep the old rules, so the effect on supply will build over several years rather than months.
Prices have not yet turned. The Index of Selected Residential Property Prices, compiled by the Bank for International Settlements (BIS) from National Bureau of Statistics of China (NBS) data on existing homes in 70 cities, fell 6.30% year-on-year in Q1 2026, a wider decline than the 5.74% recorded in Q4 2025. Adjusted for inflation, prices fell 7.07%.
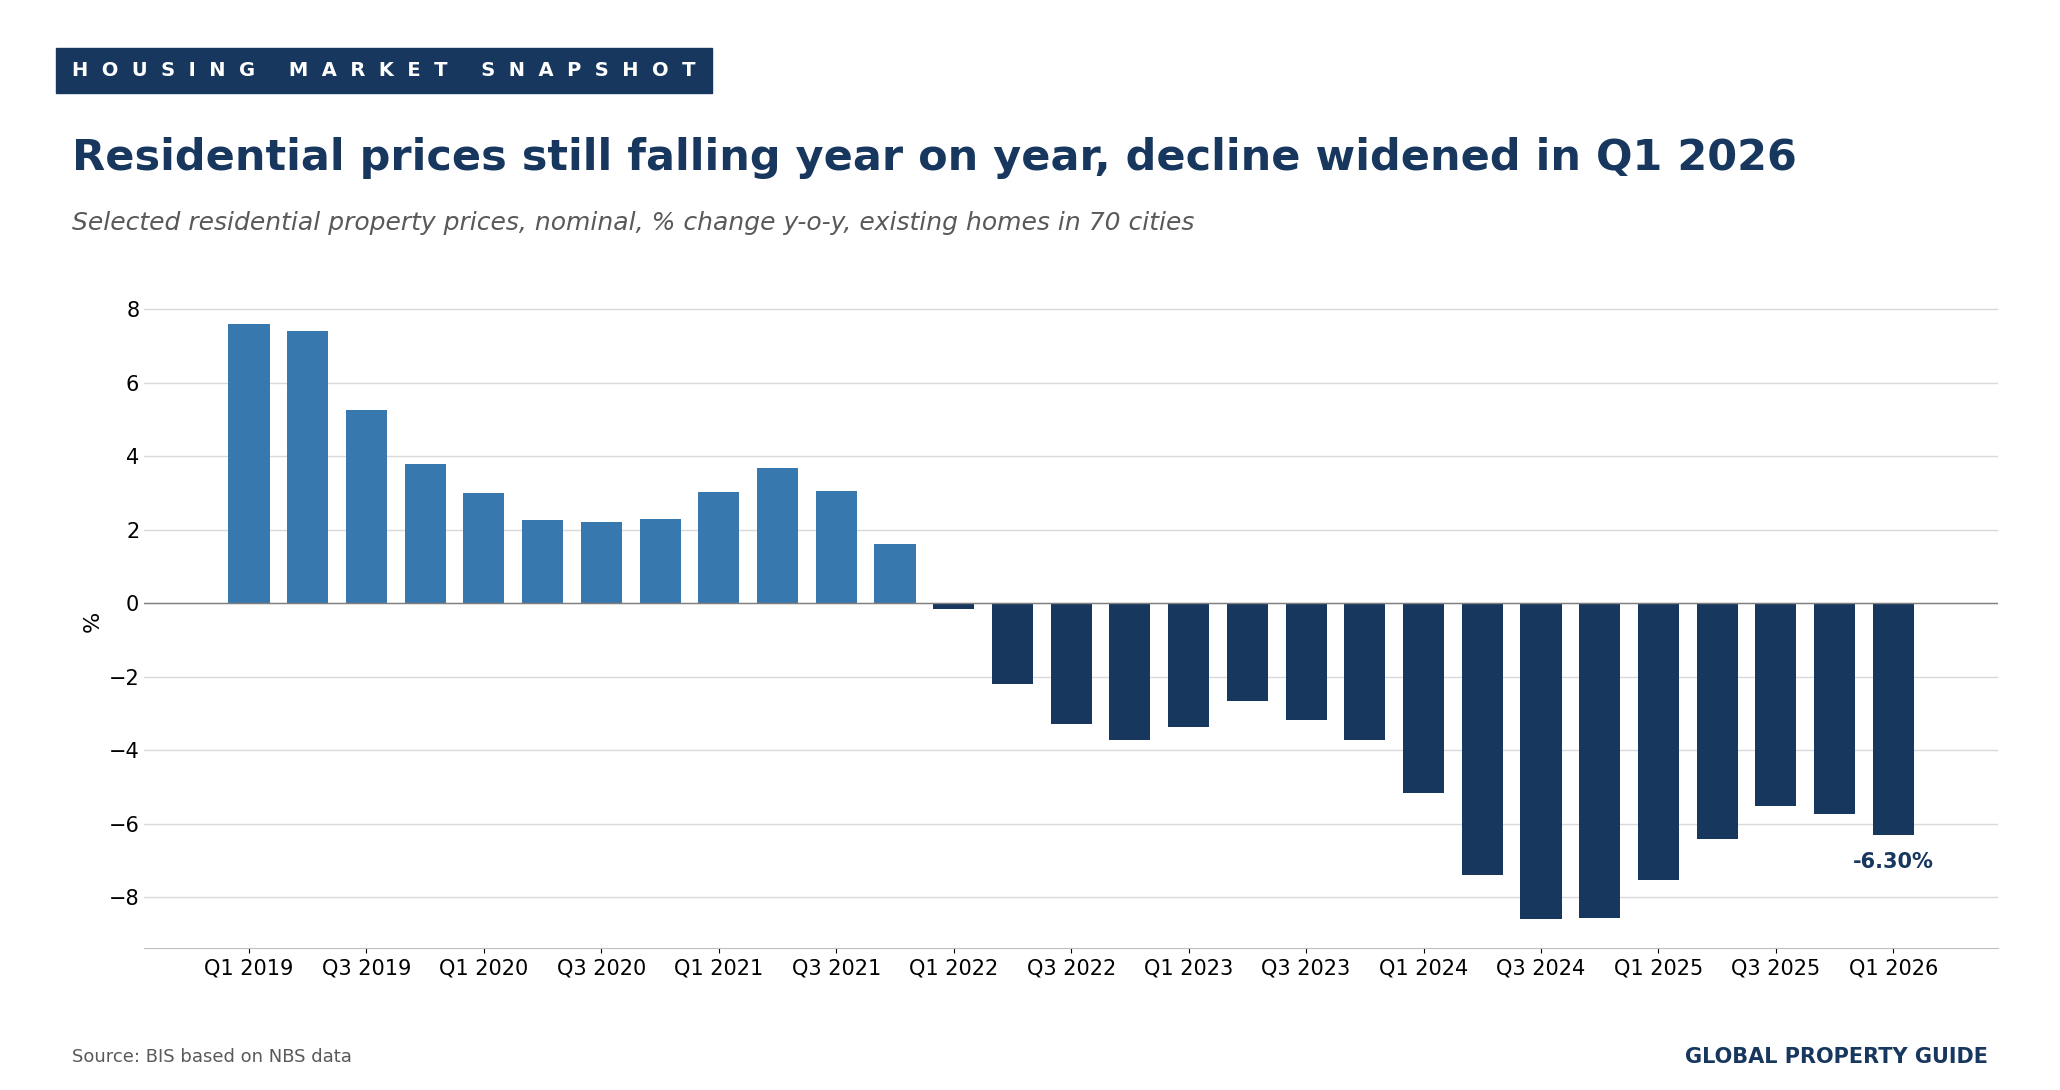
More recent city-level data point to narrowing declines, led by the largest cities. In August 2026, new-home prices in the four tier-1 cities rose 0.1% month-on-month and were 0.9% lower than a year earlier. Second-hand prices in the same cities fell 2.7% year-on-year, a considerably smaller decline than the 6.8% we reported for April. Shanghai remains the only tier-1 city where new-home prices are higher than a year ago. Beijing is the exception on the other side: it was the only tier-1 city where both new and second-hand prices fell month-on-month in August.
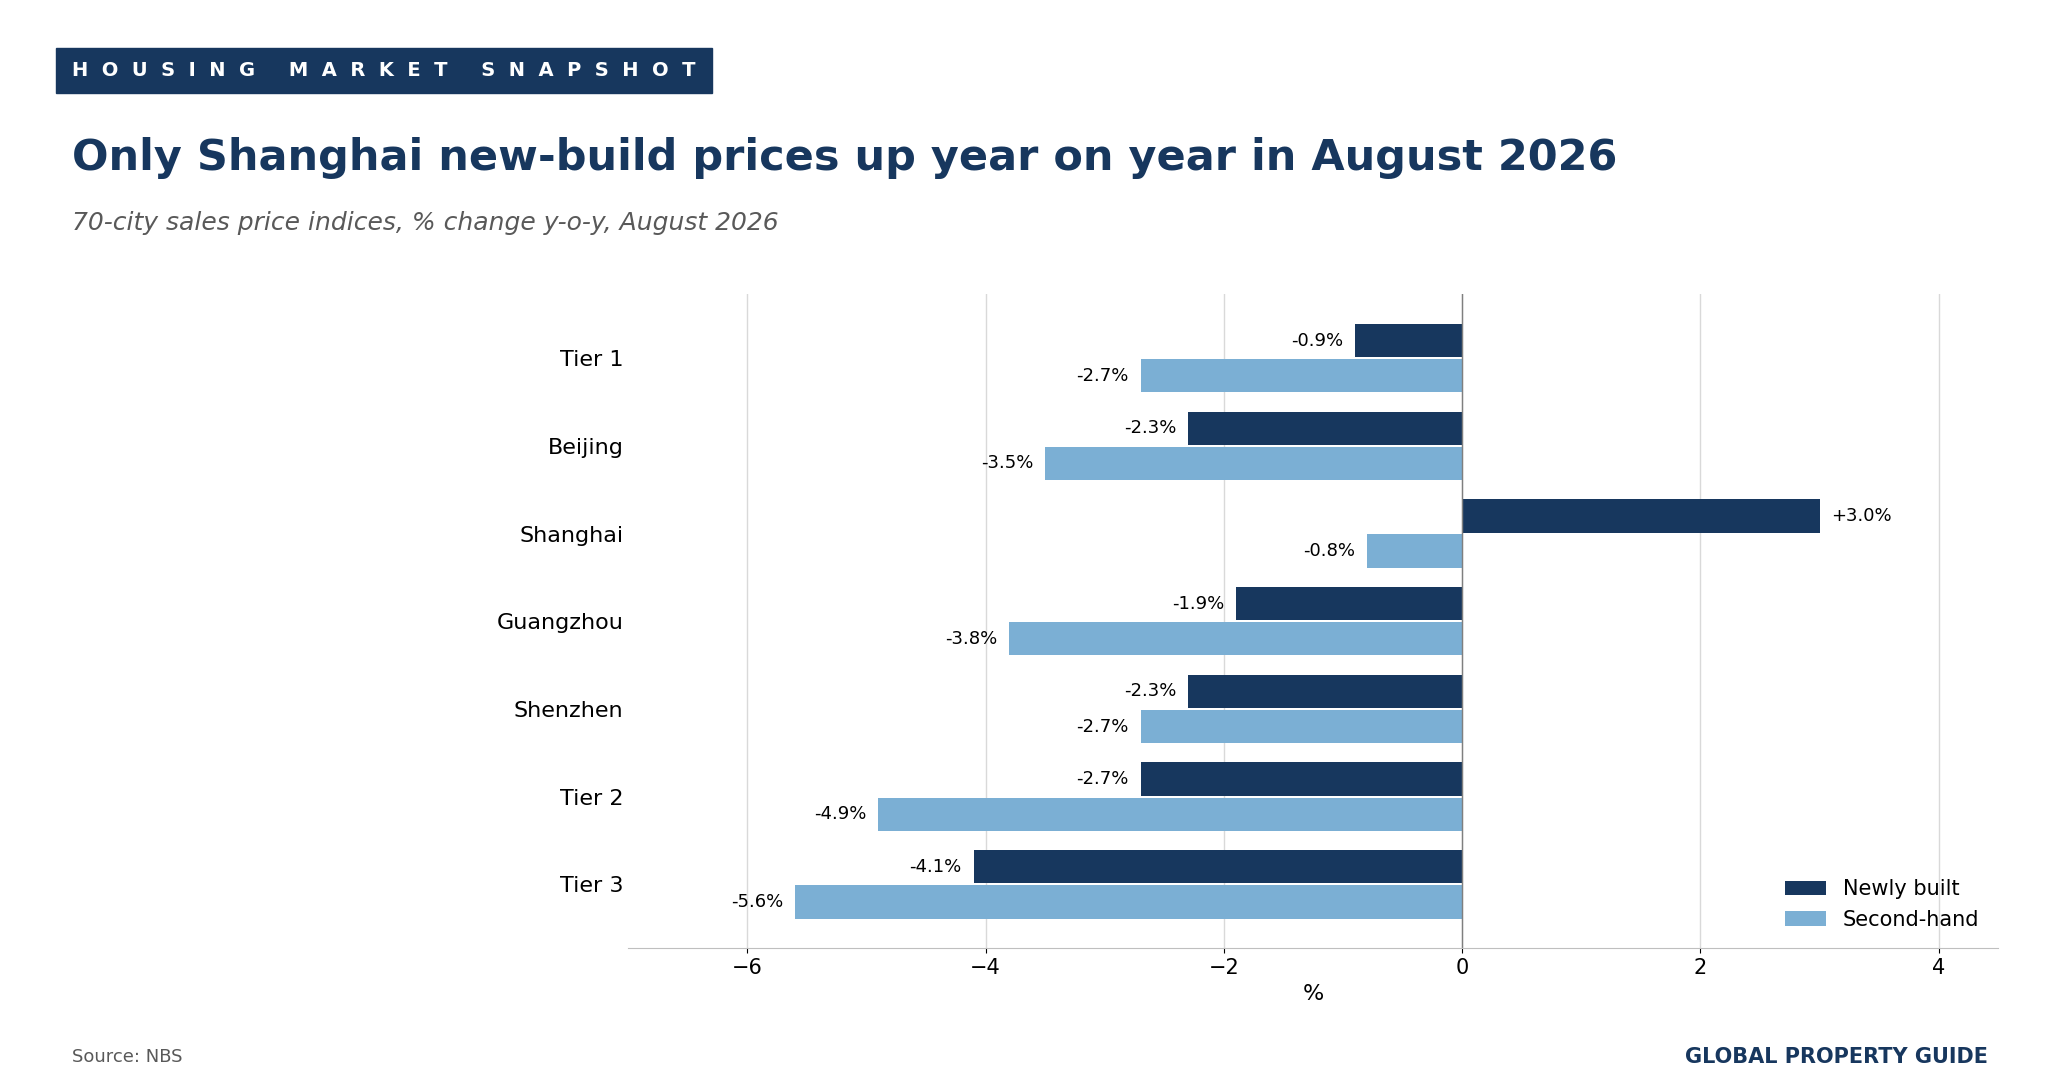
Outside the tier-1 cities, the correction is still broad. Only 21 of the 70 cities recorded flat or rising new-home prices month-on-month in August, two fewer than in July, and only eight saw flat or rising second-hand prices.
Private-sector data from the China Real Estate Index System (CREIS) show the same split between new-build and resale homes. In August 2026, the average price of new homes across 100 cities stood at RMB 17,255 (USD 2,562) per square meter, up 2.04% year-on-year, while second-hand homes averaged RMB 12,527 (USD 1,860) per square meter, down 7.08%. CREIS attributes the rise in new-home prices to launches of higher-quality projects in Shanghai, Hangzhou, Chengdu and Tianjin, which lift the average without implying like-for-like price growth.
| Average new-home prices in tier-1 cities, August 2026 | |||
| City | Newly built, RMB/sq. m. | Newly built, USD/sq. m. | MoM (%) |
| Shanghai | 65,058 | 9,658 | 0.53 |
| Shenzhen | 53,674 | 7,968 | 0.00 |
| Beijing | 47,313 | 7,024 | 0.25 |
| Guangzhou | 25,463 | 3,780 | 0.13 |
| Note: Exchange rate: USD 1 = RMB 6.7361 (August 2026 average, Federal Reserve H.10). Second-hand price levels by city were not available for this edition. | |||
| Data Source: CREIS. | |||
Early signs suggest the August package has lifted activity in the biggest cities. New-home transactions in the four tier-1 cities in the first week of September were reported roughly 42% higher than a year earlier, with Shanghai up 81%. However, the first land auctions in Beijing and Shanghai after the reform drew fewer bidders than expected, as developers adjust to longer funding cycles.
Outlook
Forecasters expect the price correction to last longer than previously thought. The latest Reuters quarterly poll, conducted from 17 to 27 August before the policy package was announced, projects a 3.4% fall in home prices in 2026, broadly unchanged from the previous poll, and a further 0.3% fall in 2027. The earlier poll had expected prices to stabilize in 2027. The next test of the reform comes in October, when National Day holiday sales and September price data will show whether the early pickup in tier-1 cities spreads more widely.
Historic Perspective
From Property Boom to a New Sales Model
For more than a decade, real estate played an outsized role in China's economy, household wealth and local government finances. Rising prices, limited alternative investments for households, heavy developer borrowing, and local governments' dependence on land sales supported a high-volume development model funded largely by buyers' presale deposits and mortgages.
The turning point came in 2020, when the authorities introduced the "Three Red Lines" policy to curb developer borrowing. The tightening exposed the sector's dependence on debt and presales. China Evergrande Group's collapse in 2021 became the most visible sign of the crisis, and mortgage boycotts by buyers of unfinished homes in 2022 damaged confidence in presales.
Existing-home prices peaked in Q3 2021. By Q1 2026, the BIS index had fallen about 22% from that peak, returning to roughly its mid-2016 level.
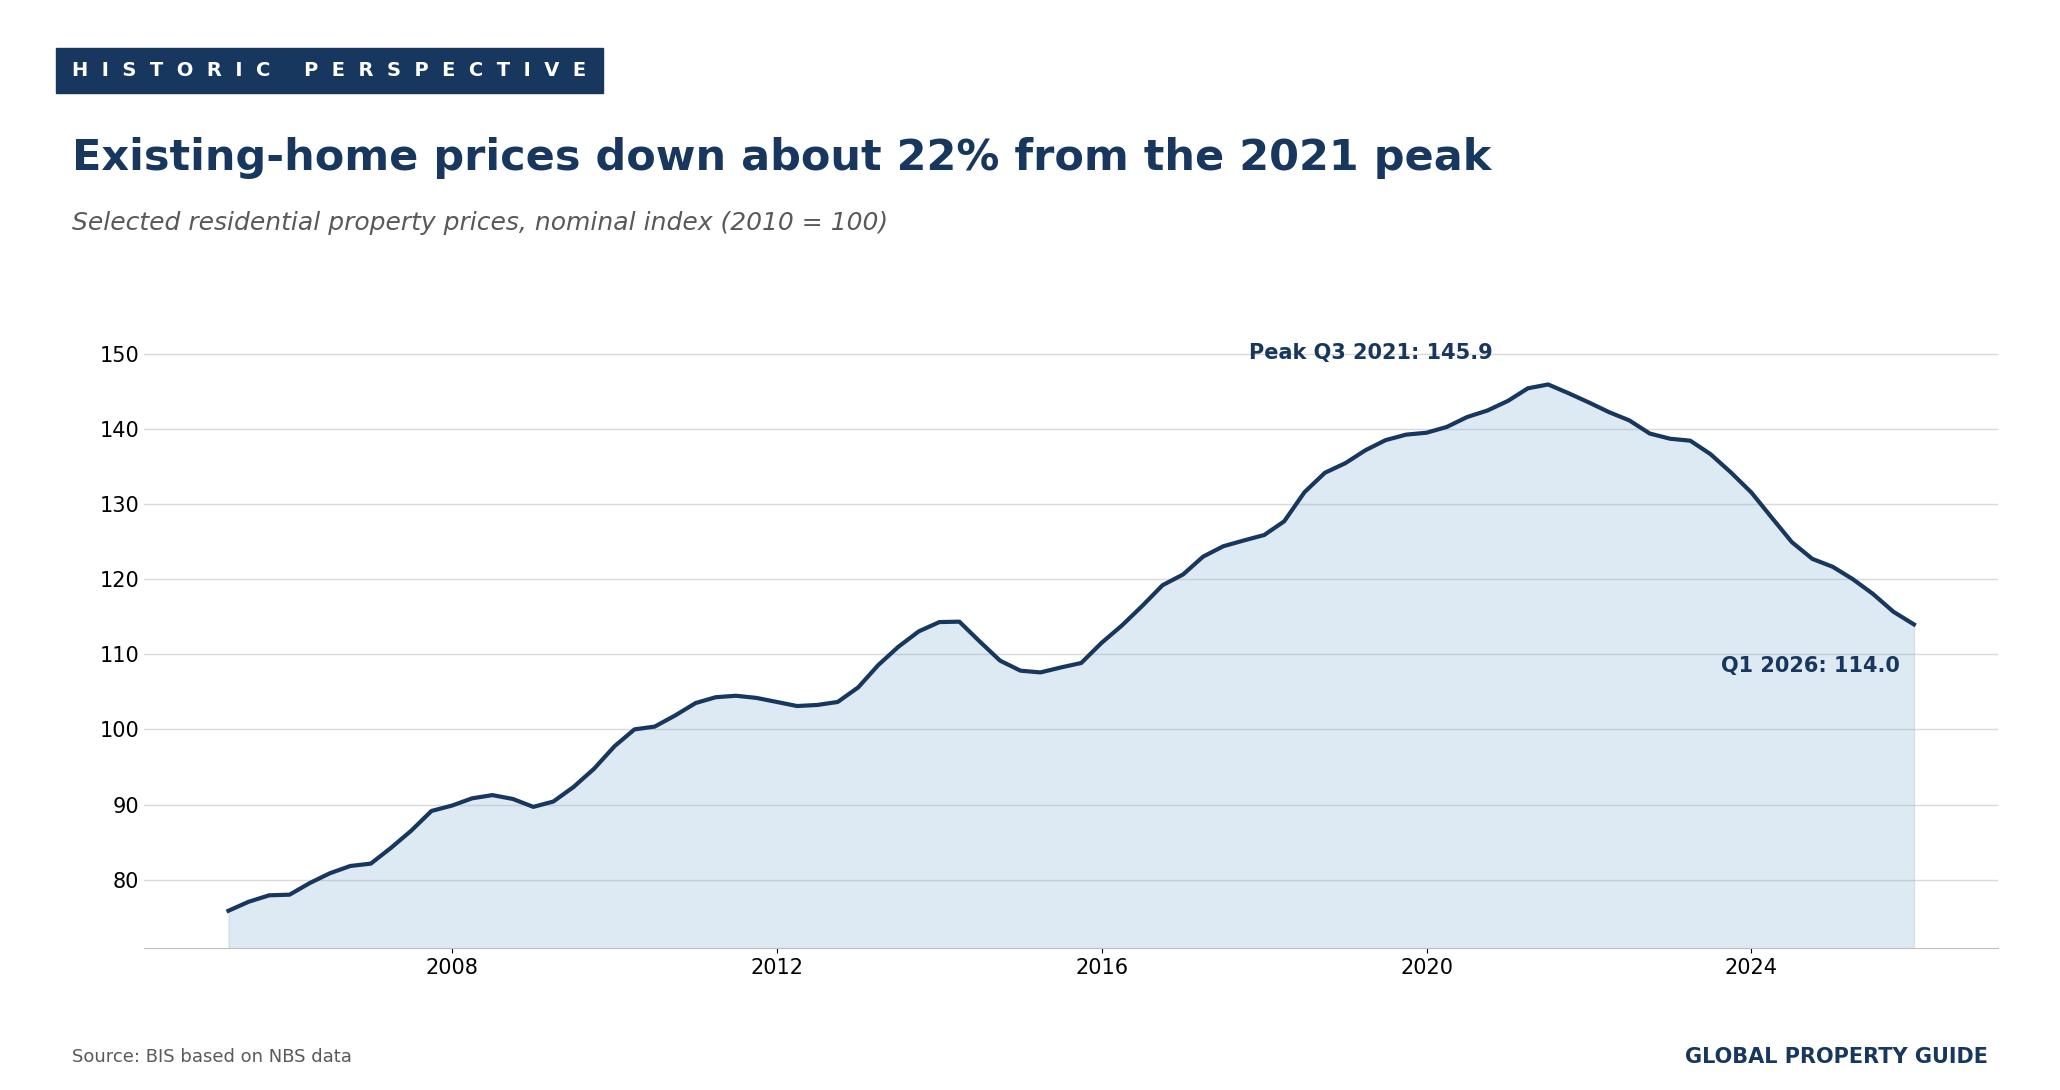
Policy support expanded through 2024 and 2025, with lower mortgage rates, reduced down payments, looser purchase restrictions, "whitelist" financing to complete unfinished projects, and programs to convert unsold homes into subsidized housing. The August 2026 reform is different in kind. Instead of trying to revive the old sales cycle, it changes the model itself, so that buyers increasingly pay for homes they can inspect rather than for homes still to be built.
Property Demand Trends
Resale Market Overtakes New-Home Sales
New-home sales continued to decline in 2026, though the fall in sales value has eased since the first quarter. In January to August, residential floor space sold fell 13.0% year-on-year to 415.03 million square meters, while residential sales value fell 13.1% to RMB 4.18 trillion (USD 620 billion). In Q1 2026, sales value had been down 18.5%.
Second-hand transactions moved the other way. MOHURD data show 549.23 million square meters of second-hand homes changed hands through online-signed contracts in January to August, 10.6% more than a year earlier. That is 134.20 million square meters, or 32%, more than the 415.03 million square meters of new homes sold over the same period, so second-hand homes now account for about 57% of combined residential transaction area. NBS spokesperson Fu Linghui described overall transaction volumes as improving.
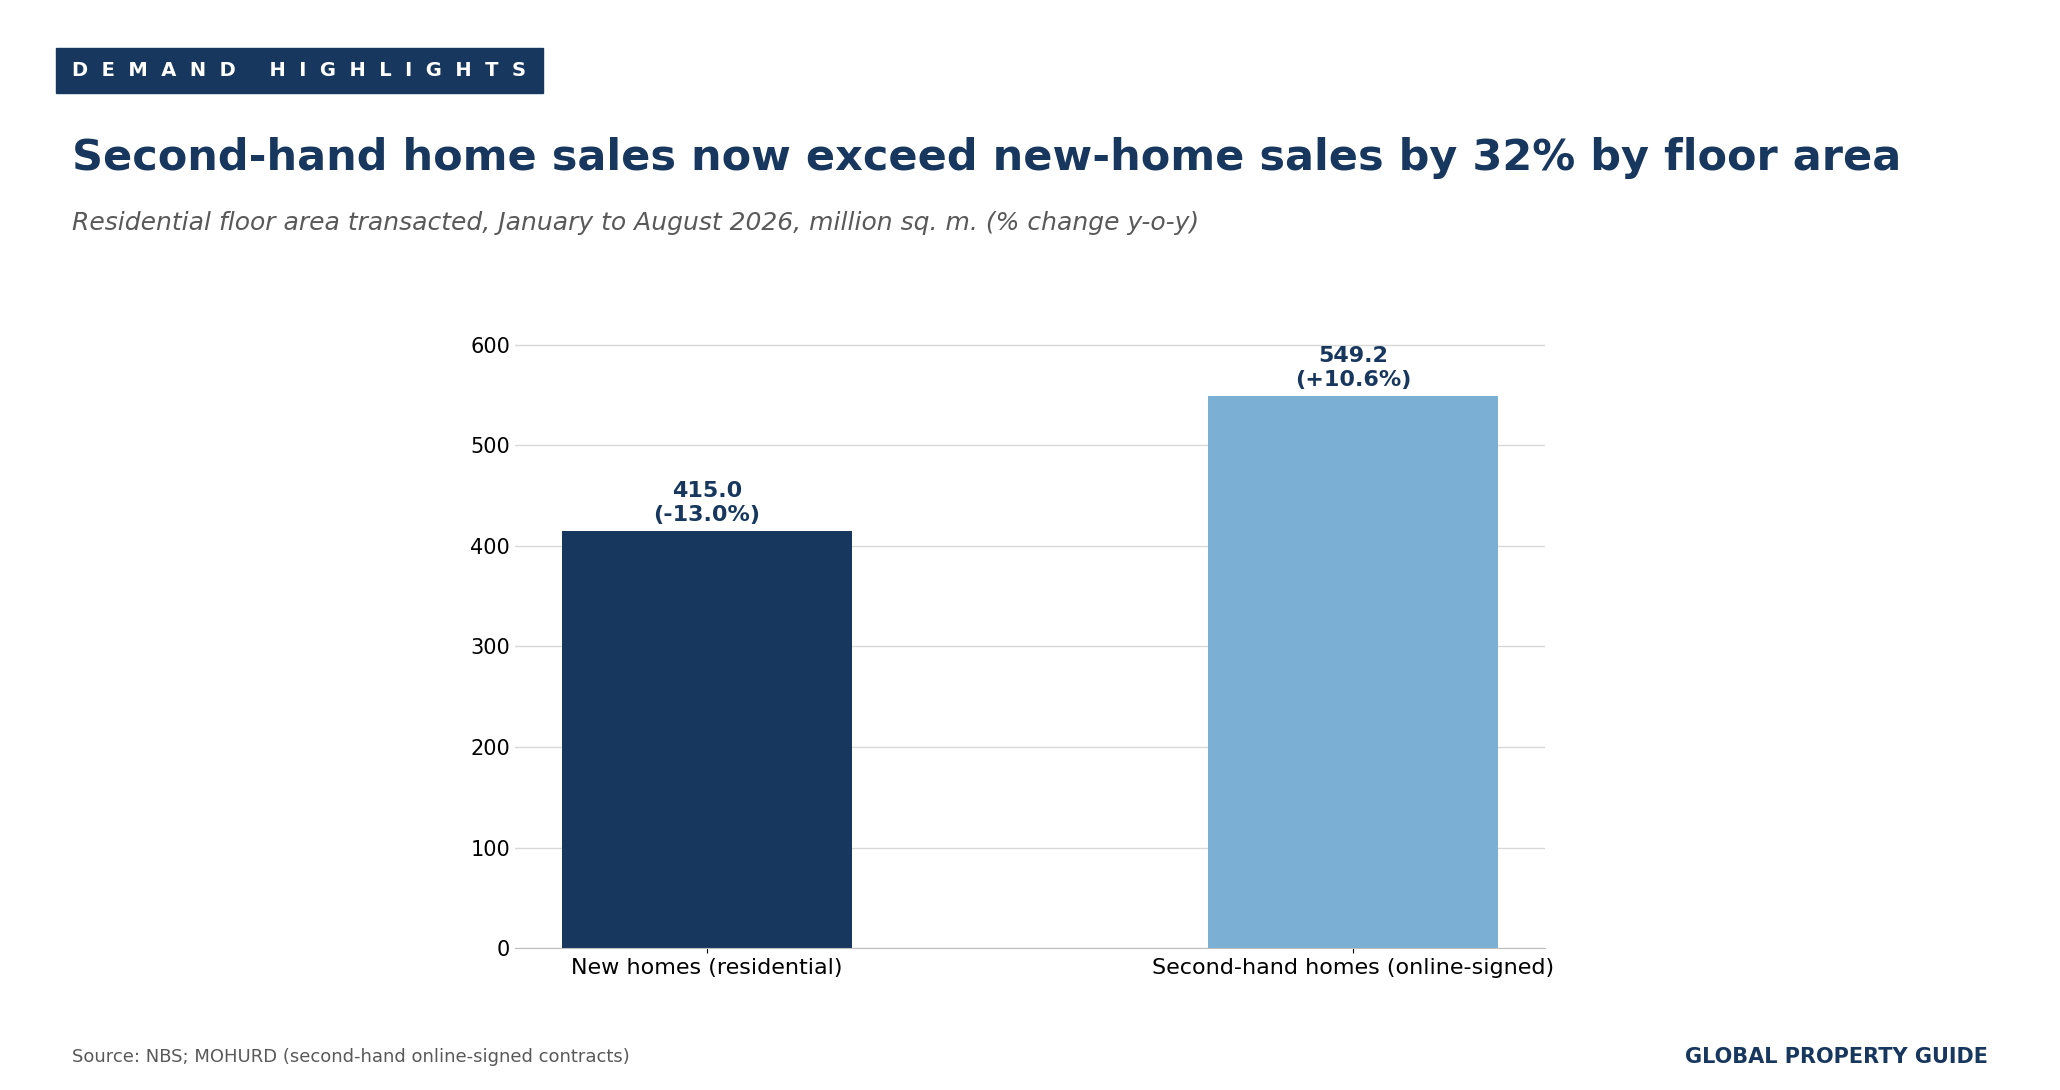
The shift reflects buyers' preference for homes that already exist and can be inspected, which the August reform is designed to extend to the new-home market. It also reflects pricing: resale sellers have cut prices to find buyers. According to the 58 Anjuke research institute, resale is still trading volume for price, with new listings in 100 cities up 8.3% year-on-year.
Early Response to the Reform
Transactions picked up in the largest cities in the first weeks of September, the traditional start of the autumn sales season. In Beijing, about 3,300 second-hand homes were sold in the first week of September, 26.1% more than a year earlier, and new-home sales rose 31.2% by floor area. In Shanghai, 2,481 second-hand homes were registered over the weekend of 12 to 13 September, including 1,319 on the Saturday alone, the highest daily total in about two months. These are early readings from a low base in the largest cities, and they do not yet show a nationwide recovery in housing demand.
Correction to our May 2026 edition: that edition declared two exchange rates (USD 1 = RMB 6.8417 for prices and RMB 6.8371 for rents) but converted trillion-yuan figures at an undeclared rate of about 6.92. As a result, the 2025 sales value, the S&P and Fitch forecasts, and the housing loan stock were understated in US dollar terms; the loan stock by about USD 67 billion. This edition uses a single exchange rate throughout: USD 1 = RMB 6.7361, the August 2026 average published by the Federal Reserve.
Property Supply Trends
Construction Contracts as Inventory Starts to Fall
The construction pipeline is still shrinking fast. In January to August 2026, residential new starts fell 25.4% year-on-year to 218.40 million square meters, and residential completions also fell 25.4%, to 147.98 million square meters. Both declines are steeper than in Q1, when starts were down 22.0% and completions 26.5%. Residential investment fell 19.7% year-on-year to RMB 3.70 trillion (USD 550 billion).
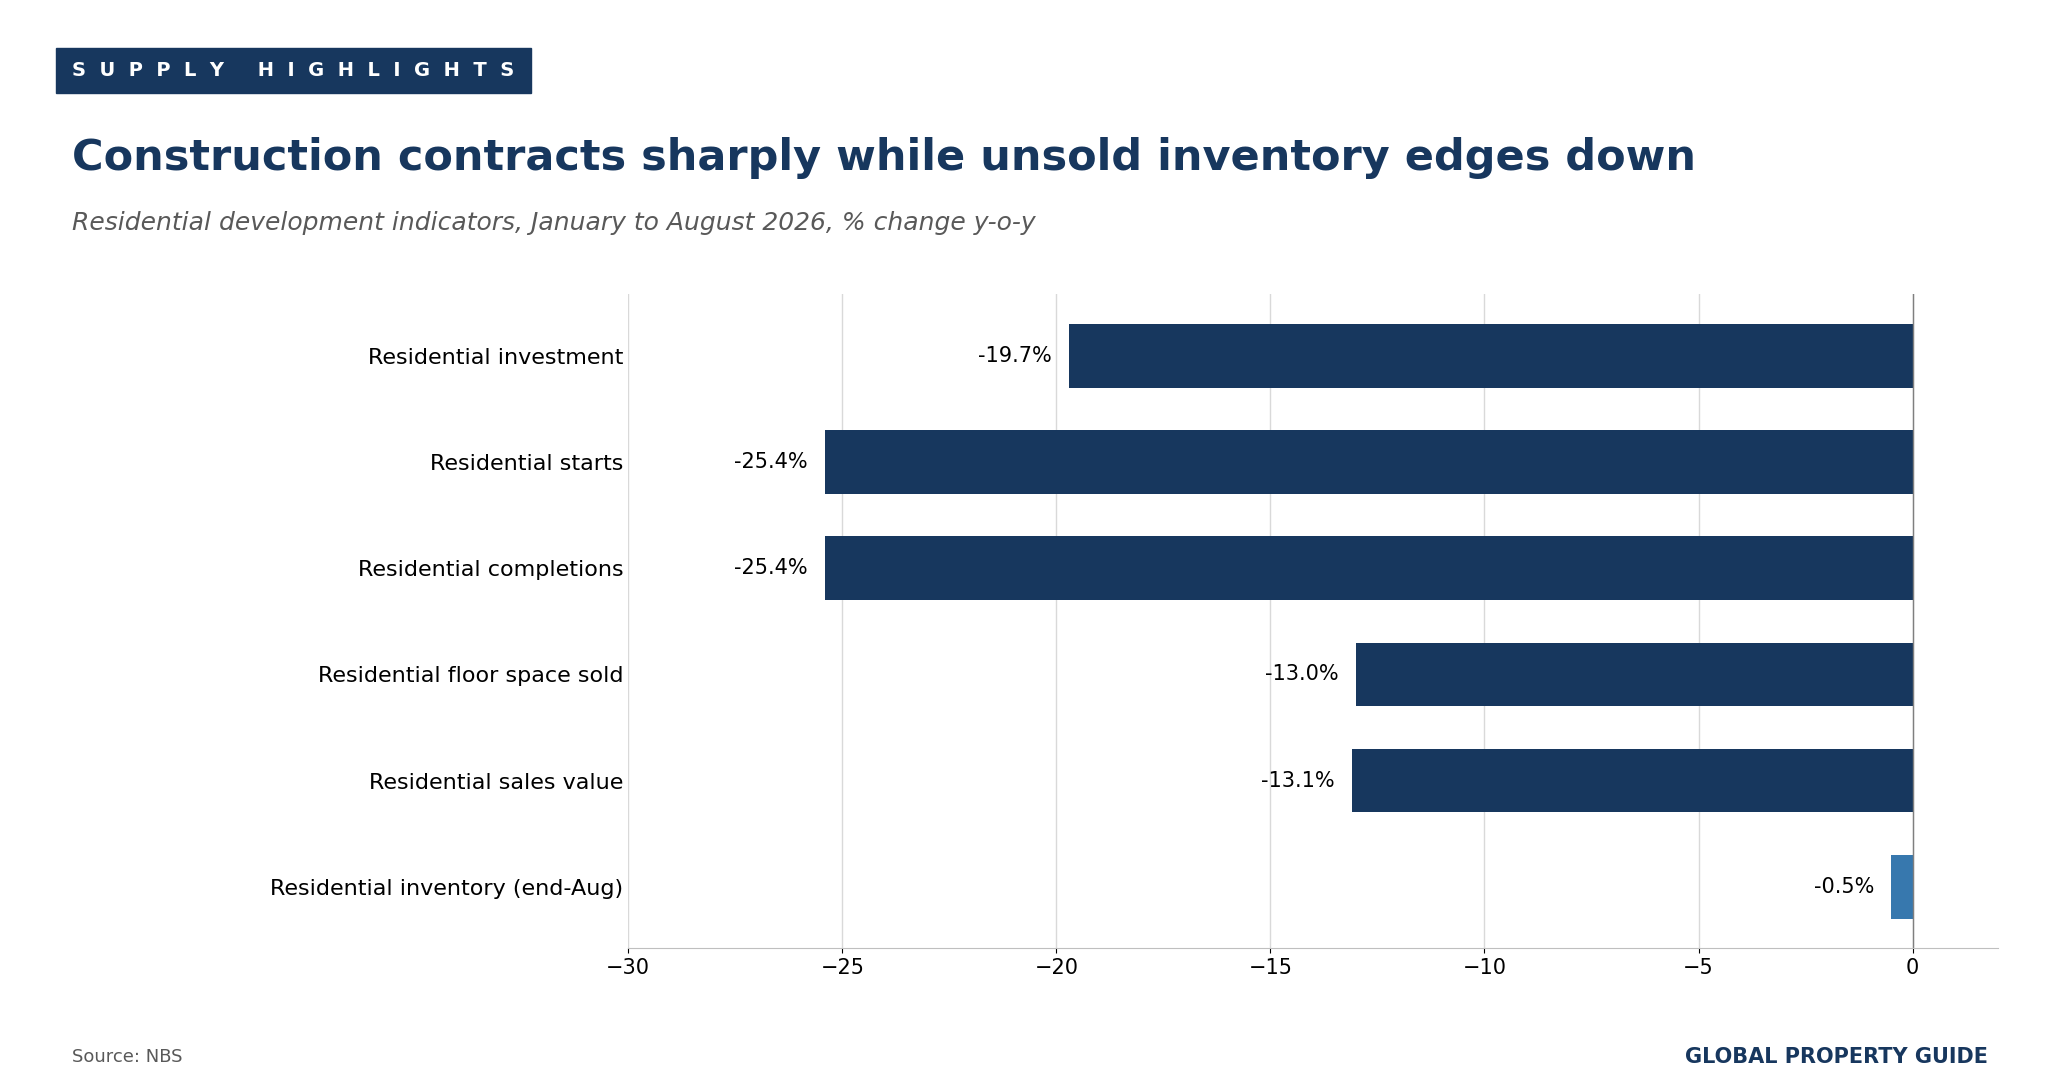
Inventory has changed direction. Unsold completed residential floor space stood at 400.83 million square meters at the end of August, 0.5% lower than a year earlier and 6.3% below the 427.71 million square meters recorded in March. Our previous edition reported inventory still rising in March.
Developer Funding Under Pressure
The reform will lengthen the time developers wait for buyers' money. Presales can typically start six to 12 months into a project, while completion takes two to three years, so delaying mortgage disbursement until completion creates a funding gap that developers and banks must cover. To help fill it, the guidelines allow development loans of up to five years for presale projects and seven years for completed-home projects.
State-backed developers with stronger balance sheets are generally expected to gain market share, while private developers that still depend on presales face tighter cash flow.
Rental Market: Rents and Rental Yields
Tier-1 Rents Recover as National Rents Stabilize
Rents are close to stabilizing nationally. The rent of rental housing component of the consumer price index (CPI) fell 0.6% year-on-year in August 2026, the same rate as in April. Rents have not risen year-on-year since early 2024.
China's rent price index:
Asking rents show a clearer picture in the biggest cities. According to CREIS, the average monthly rent across 50 cities was RMB 34.02 (USD 5.05) per square meter in August 2026, down 2.45% year-on-year. That is the smallest annual decline since September 2024, and annual declines have narrowed every month since March. Tier-1 rents rose month-on-month for a sixth consecutive month.
| Average monthly rents in tier-1 cities, August 2026 | |||
| City | Average rent per sq. m. (RMB) |
Average rent per sq. m. (USD) |
YoY change (%) |
| Shanghai | 84.39 | 12.53 | 1.25 |
| Shenzhen | 83.05 | 12.33 | -0.11 |
| Beijing | 81.99 | 12.17 | -3.33 |
| Guangzhou | 47.56 | 7.06 | -2.46 |
| Note: Exchange rate: USD 1 = RMB 6.7361 (August 2026 average, Federal Reserve H.10). | |||
| Data Source: CREIS. | |||
Shanghai is again the outlier. Rents there are now 1.25% higher than a year ago, whereas our previous edition reported falling rents in all of the largest cities. Shanghai's month-on-month rent growth led all 50 cities for a fifth consecutive month, while Beijing and Guangzhou rents slipped in August as graduate demand faded. CREIS expects rents in September to fluctuate within a narrow range.
Policy Support for Rental Housing
Rental housing remains a policy priority, particularly as a use for the existing housing stock. China's first administrative regulation for the rental market, a housing rental ordinance, took effect in September 2025 and gives more weight to institutional landlords. In 2026, the authorities extended preferential tax policies for public rental housing until the end of 2027 and guided local governments to widen access to public rental housing for migrant workers and new urban residents. Gross rental yields for China are available on our China price history page.
Mortgage Market and Interest Rates
Rate Cuts on Hold, Loan Terms Extended
The easing our previous edition expected has not happened. The one-year loan prime rate (LPR) stayed at 3.0% and the over-five-year LPR, the reference for most mortgages, at 3.5% at the 20 September fixing, unchanged for 16 consecutive months since the May 2025 cut. Higher energy prices and tighter policy abroad have limited the room for cuts: the US Federal Reserve raised its rates in September.
China's mortgage loan interest rates:
The weighted average interest rate on new mortgages, reported quarterly by the PBOC, was 3.05% in June 2026, down only 0.01 percentage points from both March and a year earlier. Official data put the August rate at about 3.1%, unchanged from a year earlier.
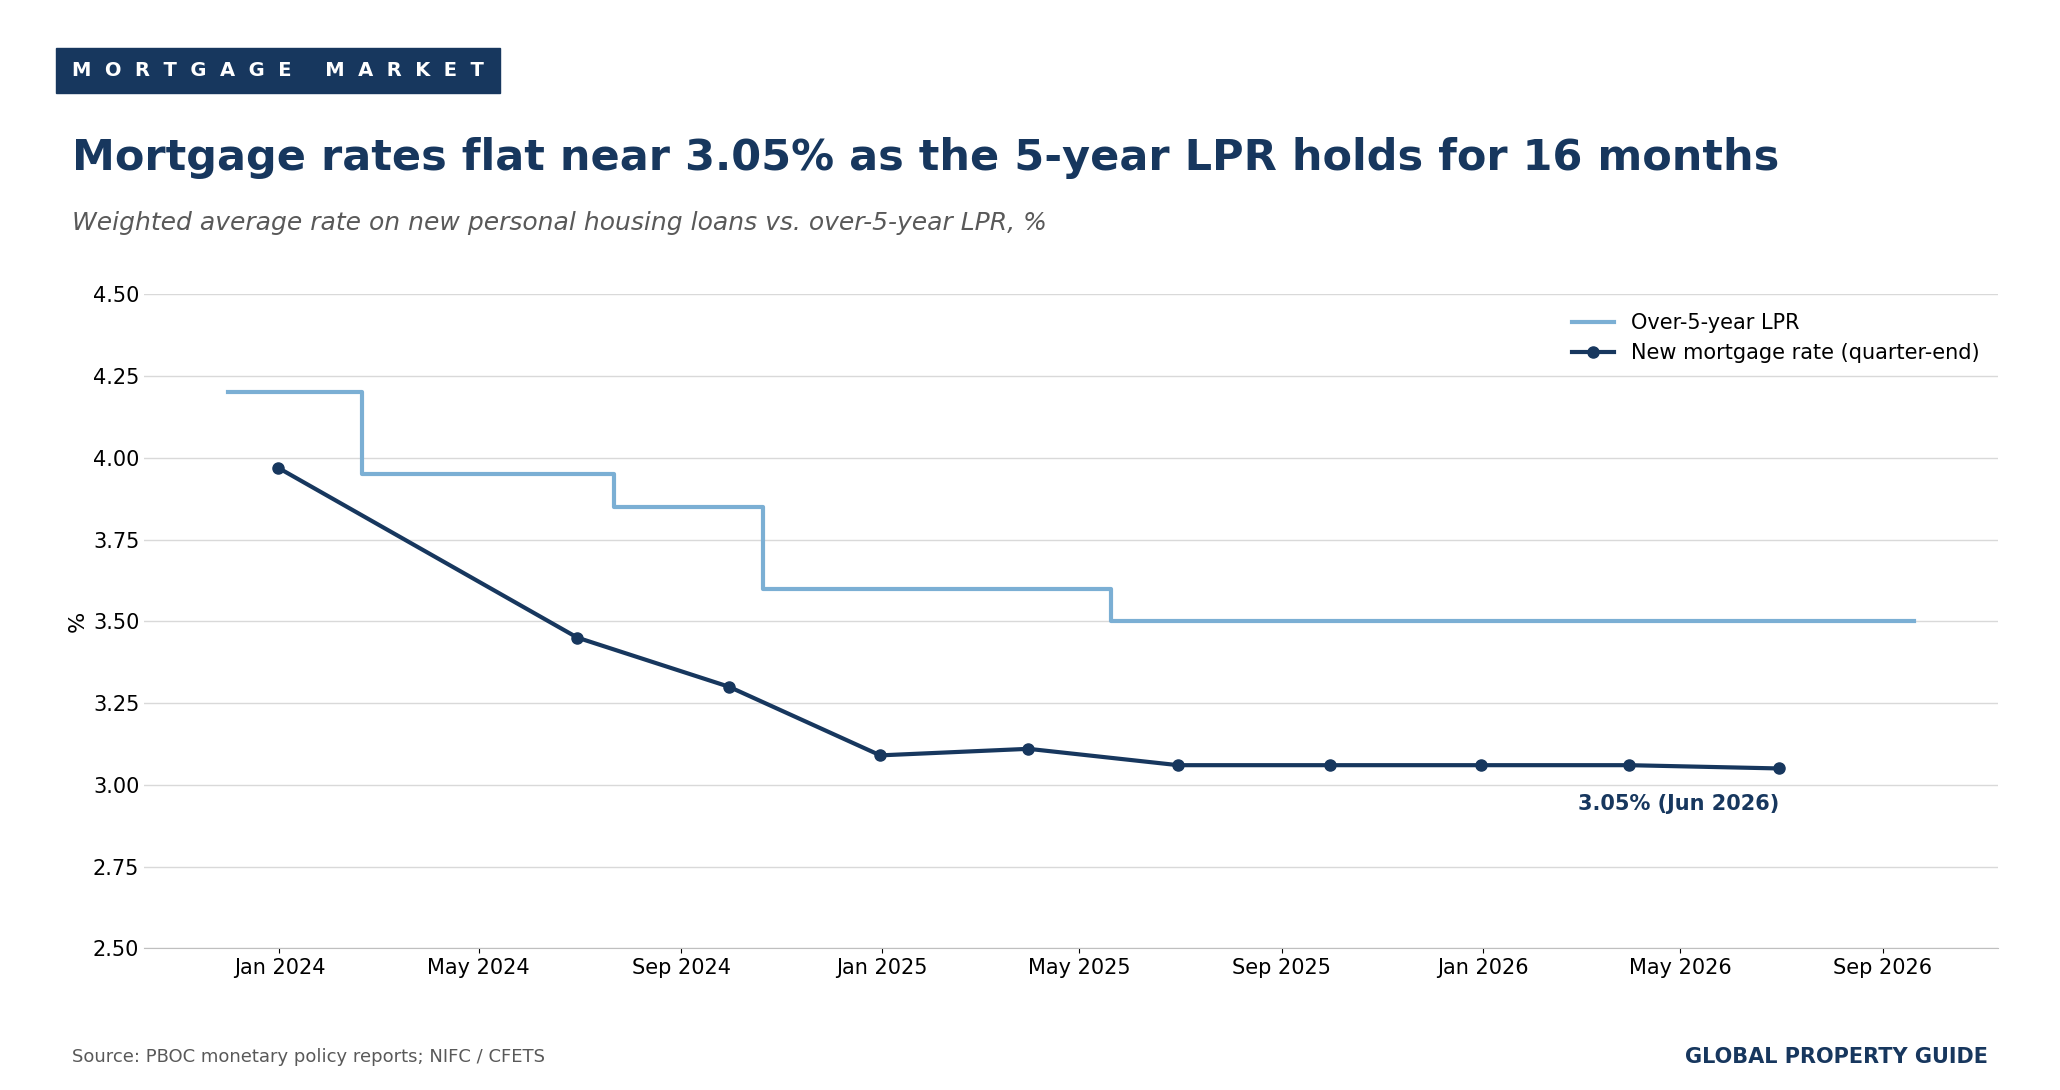
Instead of rate cuts, the authorities have turned to loan terms. Raising the maximum mortgage term to 40 years lowers monthly repayments for new borrowers, and delaying disbursement on presold homes means buyers no longer pay interest on homes that have not been delivered.
Housing Loans Keep Shrinking
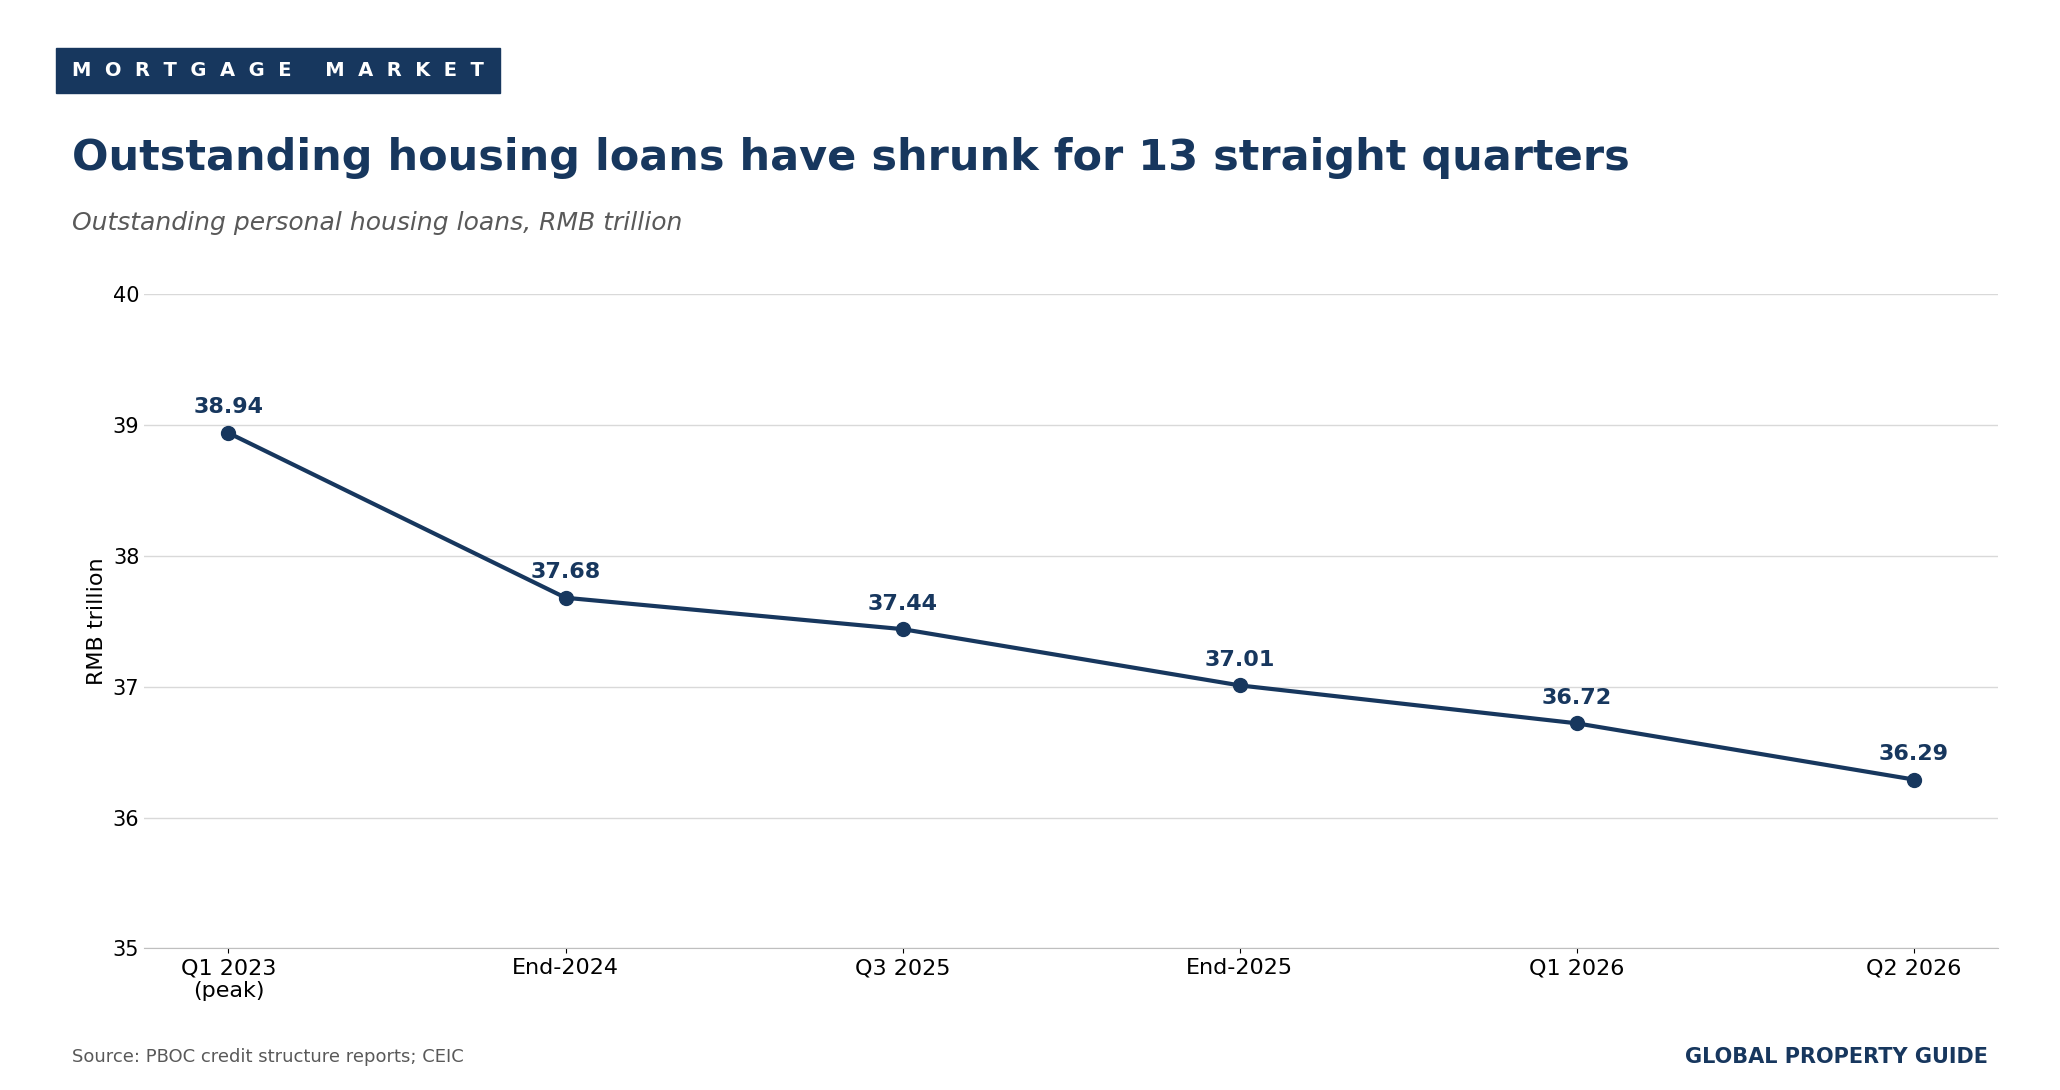
Mortgage lending has yet to recover. Outstanding personal housing loans fell to RMB 36.29 trillion (USD 5.39 trillion) at the end of Q2 2026, 3.8% lower than a year earlier, after a decline of RMB 716 billion in the first half. The stock has now fallen year-on-year for 13 consecutive quarters and is about 6.8% below its Q1 2023 peak of RMB 38.94 trillion, as new lending stays weak and households pay down existing loans.
Correction to our May 2026 edition: we reported that the new mortgage rate in December 2025 was 0.39 percentage points lower than a year earlier and 1.05 points lower than two years earlier. Those were the changes for June 2025. For December 2025, the PBOC reported a rate of 3.06%, 0.03 points lower than a year earlier and 0.91 points lower than two years earlier.
Economic and Social Factors
Growth Slows as Inflation Returns
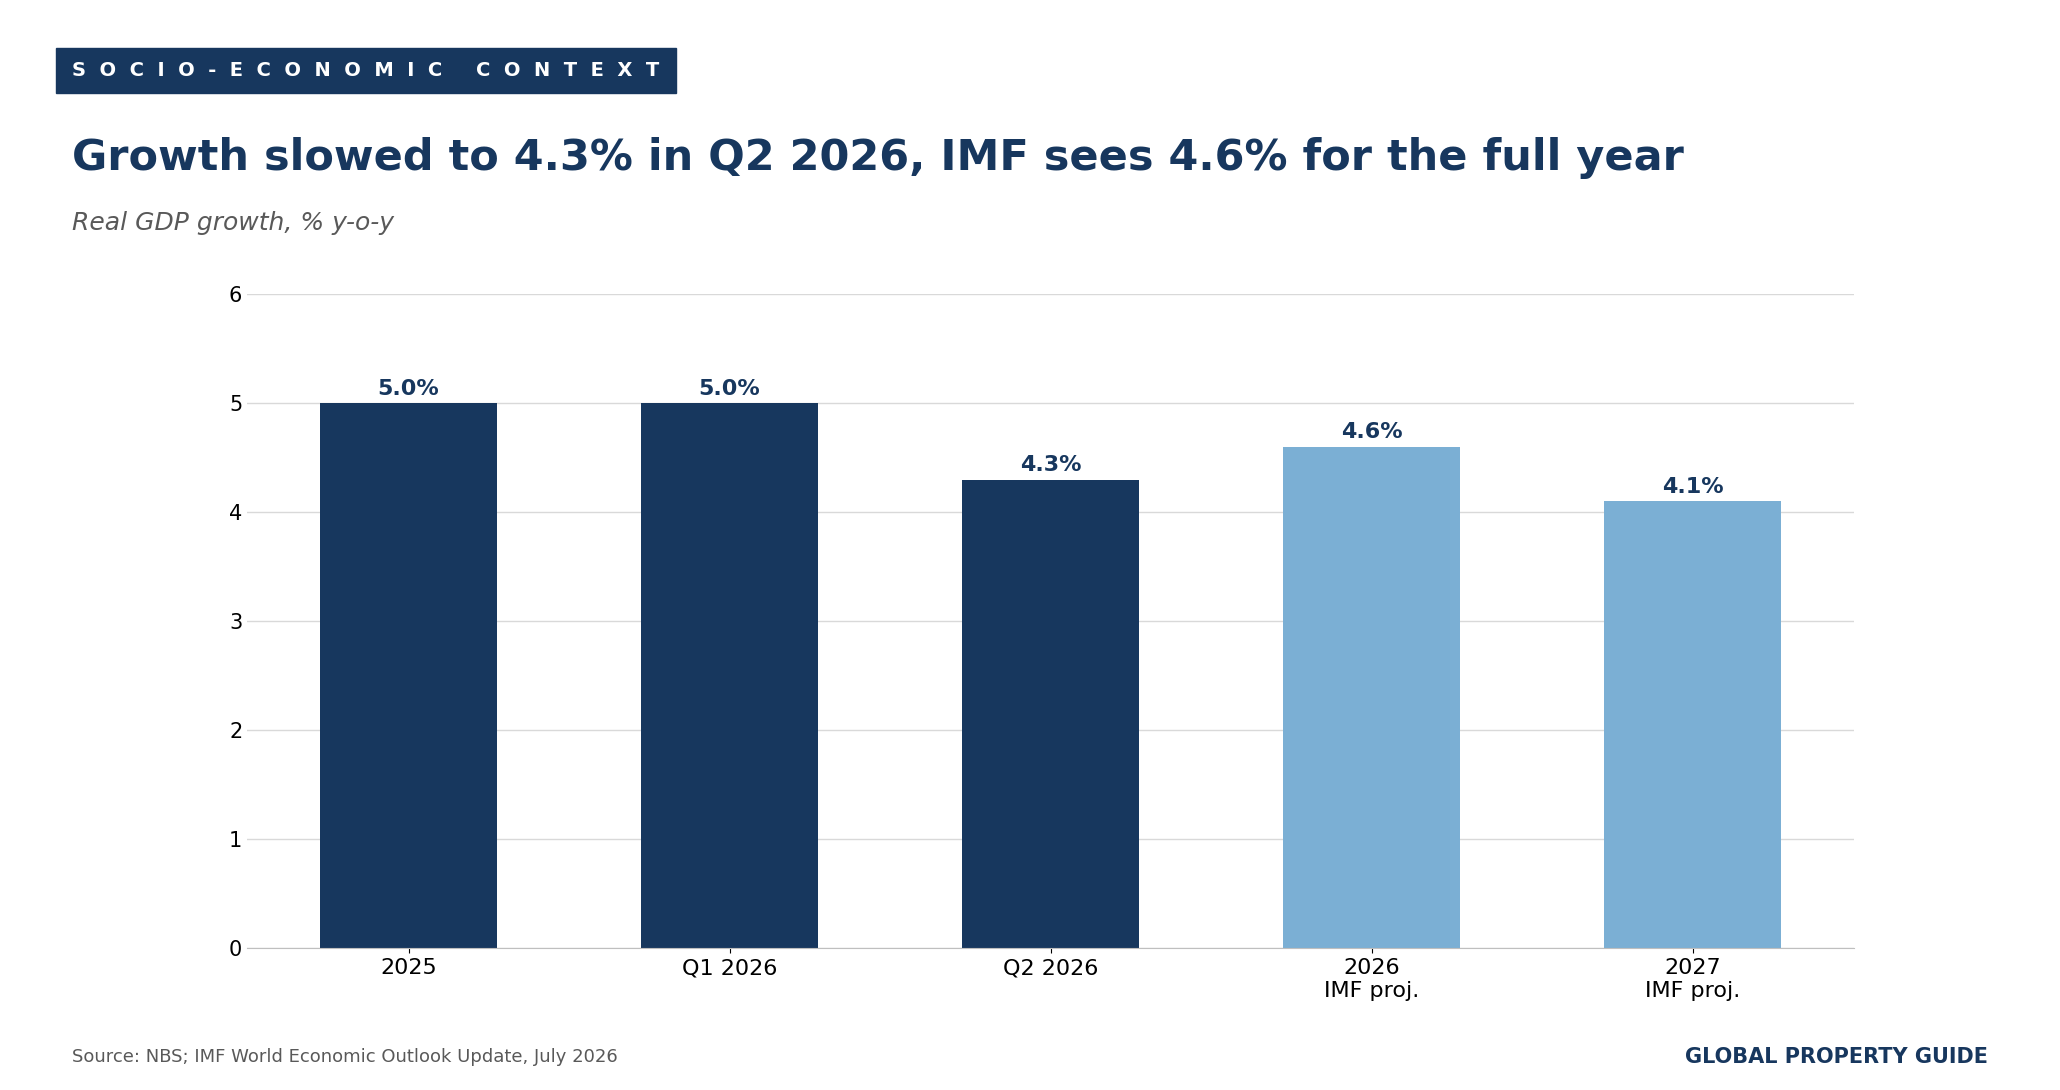
Growth slowed in the second quarter. China's economy grew 4.3% year-on-year in Q2 2026, after 5.0% in Q1, bringing first-half growth to 4.7%, within the government's 2026 target of 4.5% to 5%. August data showed weak consumption, with retail sales up just 0.4% year-on-year, and fixed-asset investment down 7.2% in January to August, while industrial output grew 5.2%.
The International Monetary Fund (IMF) is more optimistic than it was in the spring. In its July World Economic Outlook Update, the IMF raised its 2026 growth projection for China to 4.6%, from 4.4% in April, and projects 4.1% for 2027. It expects higher oil prices, uncertainty and structural headwinds to weigh on activity.
Inflation is no longer close to zero. CPI rose 0.8% year-on-year in August 2026 and averaged 0.9% in January to August, compared with 0.0% for 2025 as a whole. Core inflation reached 1.0%, and transport energy prices were up 8.3%, reflecting higher oil prices linked to the conflict in the Middle East. The IMF projects CPI inflation of 1.2% in 2026.
Labor Market Strains
The urban surveyed unemployment rate rose to 5.3% in August from 5.2% in July. Youth unemployment is higher: the rate for 16 to 24-year-olds, excluding students, rose to 18.9% in August from 17.9% in July, matching the highest reading since the NBS changed its methodology in 2023, as a record 12.7 million university graduates entered the job market. The rate for 25 to 29-year-olds rose to 7.5%.
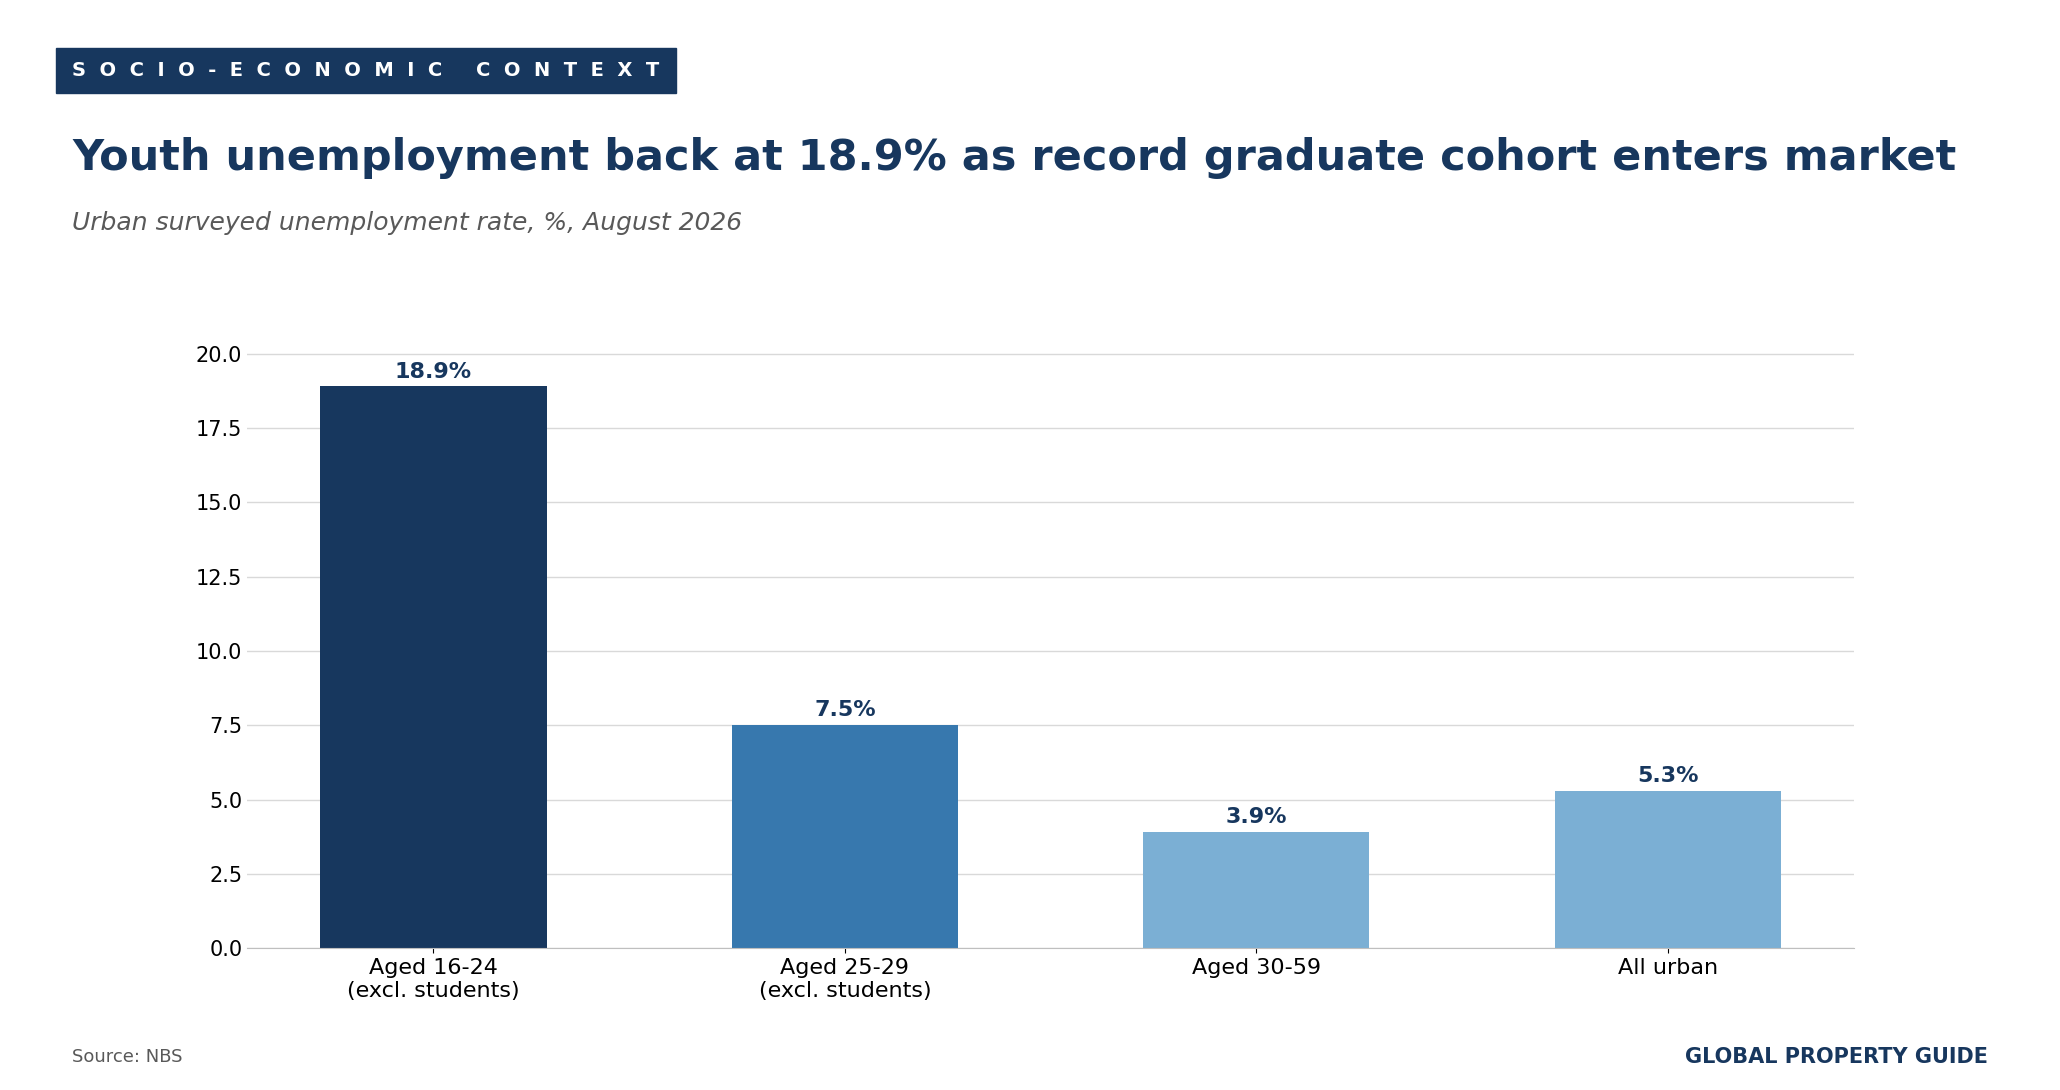
These pressures matter for housing demand, since young urban workers are the main source of first-time buyers and renters. Our previous edition noted that the IMF sees risks to China's outlook tilted to the downside, with a deeper property contraction the main domestic risk. The August reform reduces one of those risks, the delivery of unfinished homes, but a weak labor market and falling household borrowing suggest demand will recover slowly.
Sources:
- National Bureau of Statistics of China (NBS)
- Interpretation of Commercial Housing Sales Prices, August 2026 (CN): stats.gov.cn
- Sales Prices of Commercial Residential Buildings in 70 Cities, August 2026 (CN): stats.gov.cn
- Basic Situation of National Real Estate Market, January to August 2026 (CN): stats.gov.cn
- Consumer Price Index in August 2026: stats.gov.cn
- People's Bank of China (PBOC)
- China Monetary Policy Report Q2 2026 (CN): pbc.gov.cn
- China Monetary Policy Report Q4 2025 (CN): pbc.gov.cn
- Statistical Report on the Credit Structure of Financial Institutions, Q2 2026 (CN, via 21st Century Business Herald): 21jingji.com
- State Council of the People's Republic of China
- China Unveils Regulations on Housing Rental Sector: english.www.gov.cn
- China to Expand Access to Public Rental Housing: english.www.gov.cn
- China Extends Preferential Tax Policies for Public Rental Housing: china.org.cn
- Bank for International Settlements (BIS)
- Residential Property Prices for China (via FRED): fred.stlouisfed.org
- Federal Reserve Bank of St. Louis (FRED)
- Chinese Yuan Renminbi to U.S. Dollar Spot Exchange Rate: fred.stlouisfed.org
- International Monetary Fund (IMF)
- World Economic Outlook Update, July 2026: imf.org
- China Real Estate Index System (CREIS) / China Index Academy
- 100-City Price Index, August 2026 (CN, via Tencent News): news.qq.com
- 50-City Rental Index, August 2026 (CN, via Tencent News): news.qq.com
- Tier-1 Rents, August 2026 (CN, via Tencent News): news.qq.com
- China Daily
- China Issues Reforms in Home Sales and Property Financing: global.chinadaily.com.cn
- China's GDP Expands 4.7% in H1: chinaservicesinfo.com
- CGTN
- China's Property Sales Model Sees Major Shift: news.cgtn.com
- Caixin
- How China's New Housing Rules Rewrite Property Financing: caixinglobal.com
- Xinhua News Agency
- Major Chinese Cities Report Narrowed Home Price Declines in August: english.news.cn
- China's Loan Prime Rates Remain Unchanged: english.news.cn
- China's Loan Prime Rates Remain Unchanged (china.org.cn): china.org.cn
- Reuters
- China Home Prices Seen Falling Slightly Less This Year, Property Investment Slump Deepens: wimz.com
- China Keeps Benchmark Lending Rates Unchanged for 16th Month (via Business Standard): business-standard.com
- CNBC
- South China Morning Post
- Record Influx of University Graduates Pushes Youth Unemployment to 18.9%: scmp.com
- Tencent News
- September Market After the 828 Policy (CN): news.qq.com
- Completed-Home Era Market Report (CN): news.qq.com
- Real Estate Data January to August (CN): news.qq.com