India's Residential Property Market Analysis 2026
India's housing market has held up, but the backdrop has changed. The Reserve Bank of India (RBI) raised interest rates in October 2026 for the first time since 2023, as inflation climbed to 5.5%. House prices are still rising slowly, home sales are flat, and developers keep launching more homes than they sell, mostly at the top end of the market.
This extended overview from Global Property Guide covers key aspects of the Indian housing market and takes a closer look at its most recent developments and long-term trends.
Table of Contents
- Property Prices and Price Index
- Property Demand Trends
- Property Supply Trends
- Rental Market: Rents and Rental Yields
- Mortgage Market and Interest Rates
- Economic and Social Factors
Property Prices and Price Index
In our April 2026 edition, interest rates had just been cut by a total of 1.25 percentage points, inflation was below 3.5%, and most forecasters expected the RBI to keep rates on hold until at least mid-2027. Six months later, that picture has turned around. Inflation has risen every month this year, the RBI raised its policy rate in October, and it has said that further cuts are "off the table in the near term". Prices and sales have so far taken this in their stride, but the support from cheaper borrowing is now gone.
India's house price annual change:
The RBI's All-India House Price Index rose by 3.6% in the year to Q1 2026-27, the quarter from April to June 2026, according to the RBI. That was the same rate of growth as a year earlier. From the previous quarter, prices rose by 1.1%. The index, which is based on registered sale transactions in 18 cities, stood at 117.5 points (2022-23 = 100).
Growth has stayed in a narrow range for more than a year. In the year to Q4 2025-26 (January to March 2026), prices rose by 4.2%, according to the RBI, up from 3.8% a year earlier. In Q2 2025-26, annual growth had dipped to 2.2%, the RBI said, down from 7.0% a year before.
The strongest gains are now coming from smaller cities. In the latest quarter, Chandigarh, Jaipur, Kanpur, Lucknow and Thiruvananthapuram contributed most to annual growth, the RBI said.
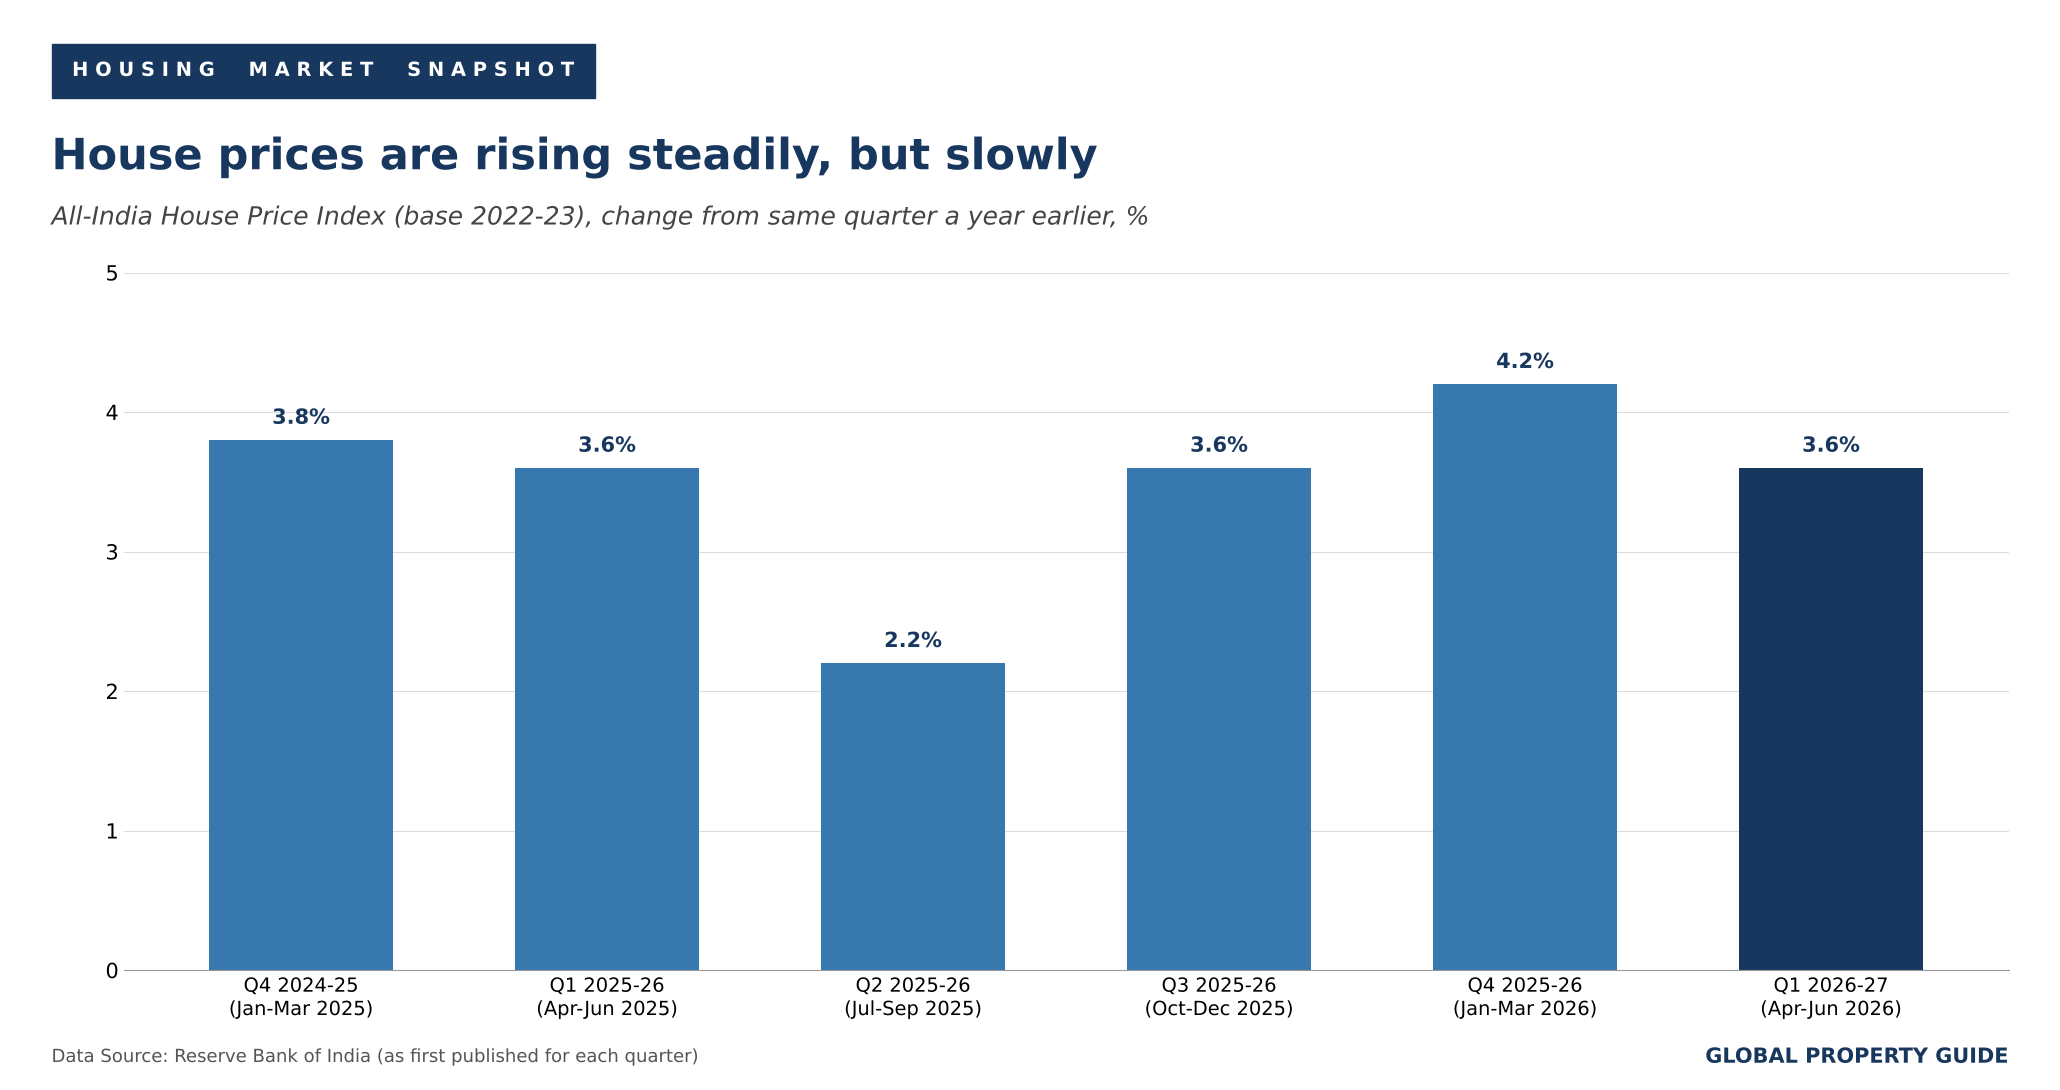
These are modest increases. Consumer prices rose by an average of about 3.9% in the same April to June quarter, so house prices fell slightly in real terms, and inflation has risen further since then.
Developer and agent data show faster growth in the big cities, and especially in the National Capital Region (NCR) around Delhi. In H1 2026, weighted average prices rose by 18% from a year earlier in both Delhi and Faridabad and by 15% in Ghaziabad, according to Knight Frank. Prices rose by 9% in Bengaluru and 7% in Hyderabad. In most other markets, including Mumbai, Pune, Chennai and Kolkata, prices rose by around 5%. Ahmedabad and Navi Mumbai were the slowest, at 3%.
Residential prices in selected markets:
| Market | Average Price, H1 2026, INR/sq m |
Average Price, H1 2026, USD/sq m |
12-month change |
| Mumbai (city) | INR 396,987 | USD 4,163 | 5% |
| Delhi | INR 280,155 | USD 2,938 | 18% |
| Gurugram | INR 197,562 | USD 2,072 | 6% |
| Noida | INR 162,633 | USD 1,705 | 8% |
| Thane | INR 160,900 | USD 1,687 | 4% |
| Navi Mumbai | INR 148,414 | USD 1,556 | 3% |
| Pune | INR 108,318 | USD 1,136 | 5% |
| Bengaluru | INR 100,686 | USD 1,056 | 9% |
| Ghaziabad | INR 104,066 | USD 1,091 | 15% |
| Hyderabad | INR 88,889 | USD 932 | 7% |
| Chennai | INR 81,322 | USD 853 | 5% |
| Kolkata | INR 63,960 | USD 671 | 5% |
| Ahmedabad | INR 51,947 | USD 545 | 3% |
| Note: Exchange rate as of 29 October 2026, USD 1 = INR 95.3688. Converted from INR per sq. ft.. | |||
| Data source: Knight Frank Research. | |||
Knight Frank now reports prices for individual submarkets rather than for whole metropolitan regions. Mumbai in this table means the city itself, not the wider Mumbai Metropolitan Region, so the figures cannot be compared directly with the city-level table in our previous edition.
Knight Frank describes the market as being in "late-cycle consolidation rather than correction". Developers are avoiding formal price cuts, it says, and are instead offering flexible payment plans, interest subsidy schemes, stamp duty waivers and higher commissions for brokers. As a result, it says, the published price growth may overstate what sellers can actually achieve when they resell.
For foreign buyers, the exchange rate matters as much as local prices. The rupee has fallen sharply against the US dollar this year. It was at INR 89.98 per dollar on 1 January 2026 and passed INR 95 at the end of April, according to RBI data. On 29 October, the reference rate was INR 95.3688, as published by the RBI. That is a fall of 5.7% since the start of the year. As a result, a home whose rupee price rose by 5% over the past year is now slightly cheaper in dollar terms.
Property Demand Trends
Sales are flat
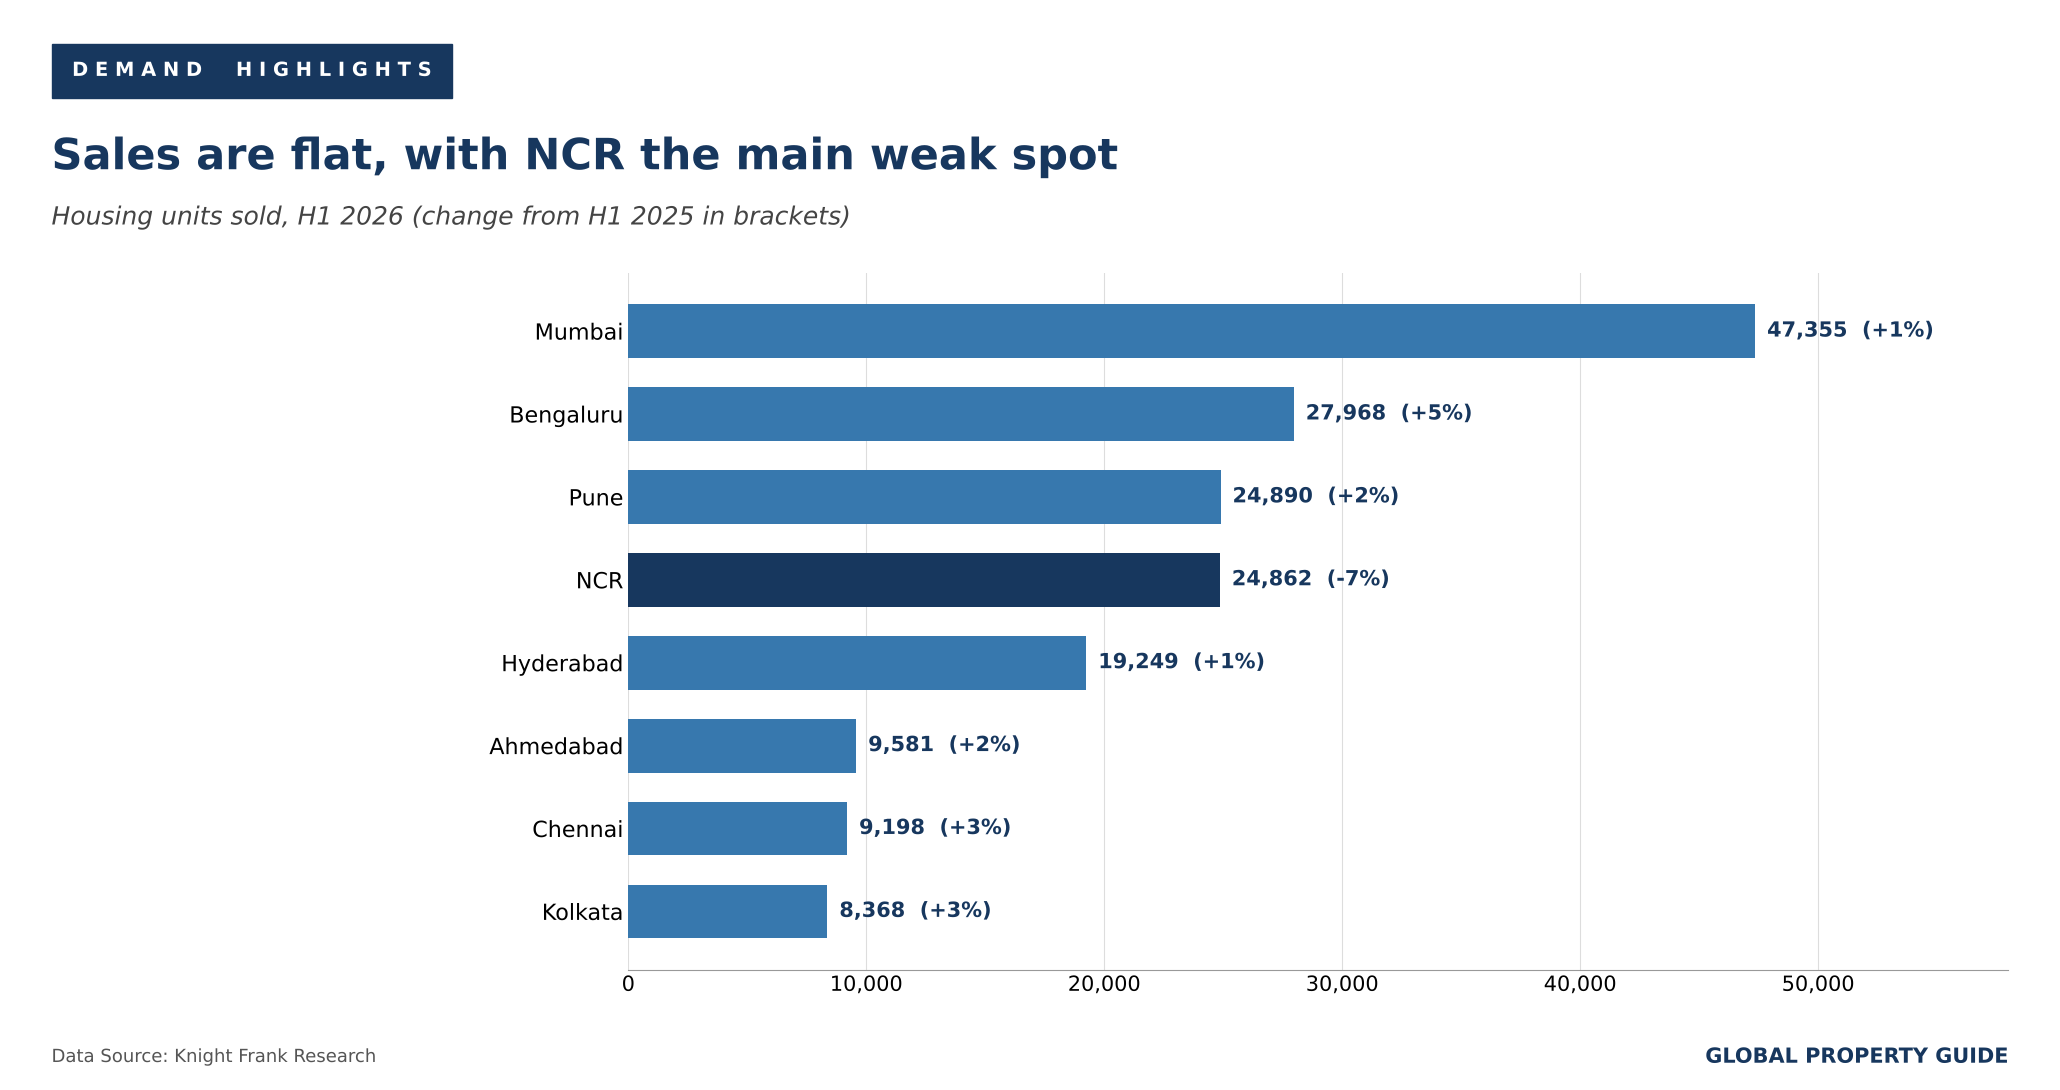
Home sales across India's eight largest cities were almost unchanged in H1 2026. A total of 171,471 homes were sold, up just 0.7% from 170,201 a year earlier, according to Knight Frank. In the whole of 2025, sales were 348,207 units, down 0.7% from 350,612 in 2024.
The year began weakly. In Q1 2026, sales fell by 4% from a year earlier to 84,827 units, according to Knight Frank, which pointed to "the ongoing conflict involving Iran" as a reason for more cautious buyers. Sales then picked up in the second quarter.
CBRE's figures show a similar picture. It counted about 61,150 sales in Q2 2026 and about 127,300 in H1 2026, according to its India Market Monitor. CBRE describes the slower pace as a move toward more sustainable sales levels.
Mumbai is still by far the biggest market. With 47,355 sales in H1 2026, up 1% from a year earlier, it accounted for 27.6% of all sales in the eight cities, Knight Frank said. Bengaluru had the strongest growth, at 5%, while Chennai and Kolkata rose by 3% and Pune and Ahmedabad by 2%.
The NCR was the only large market where sales fell, by 7% to 24,862 units. This continues the trend of 2025, when NCR sales fell by 9%. Prices in the NCR have risen much faster than elsewhere, and affordable homes in good locations are in short supply.
Buyers keep moving upmarket
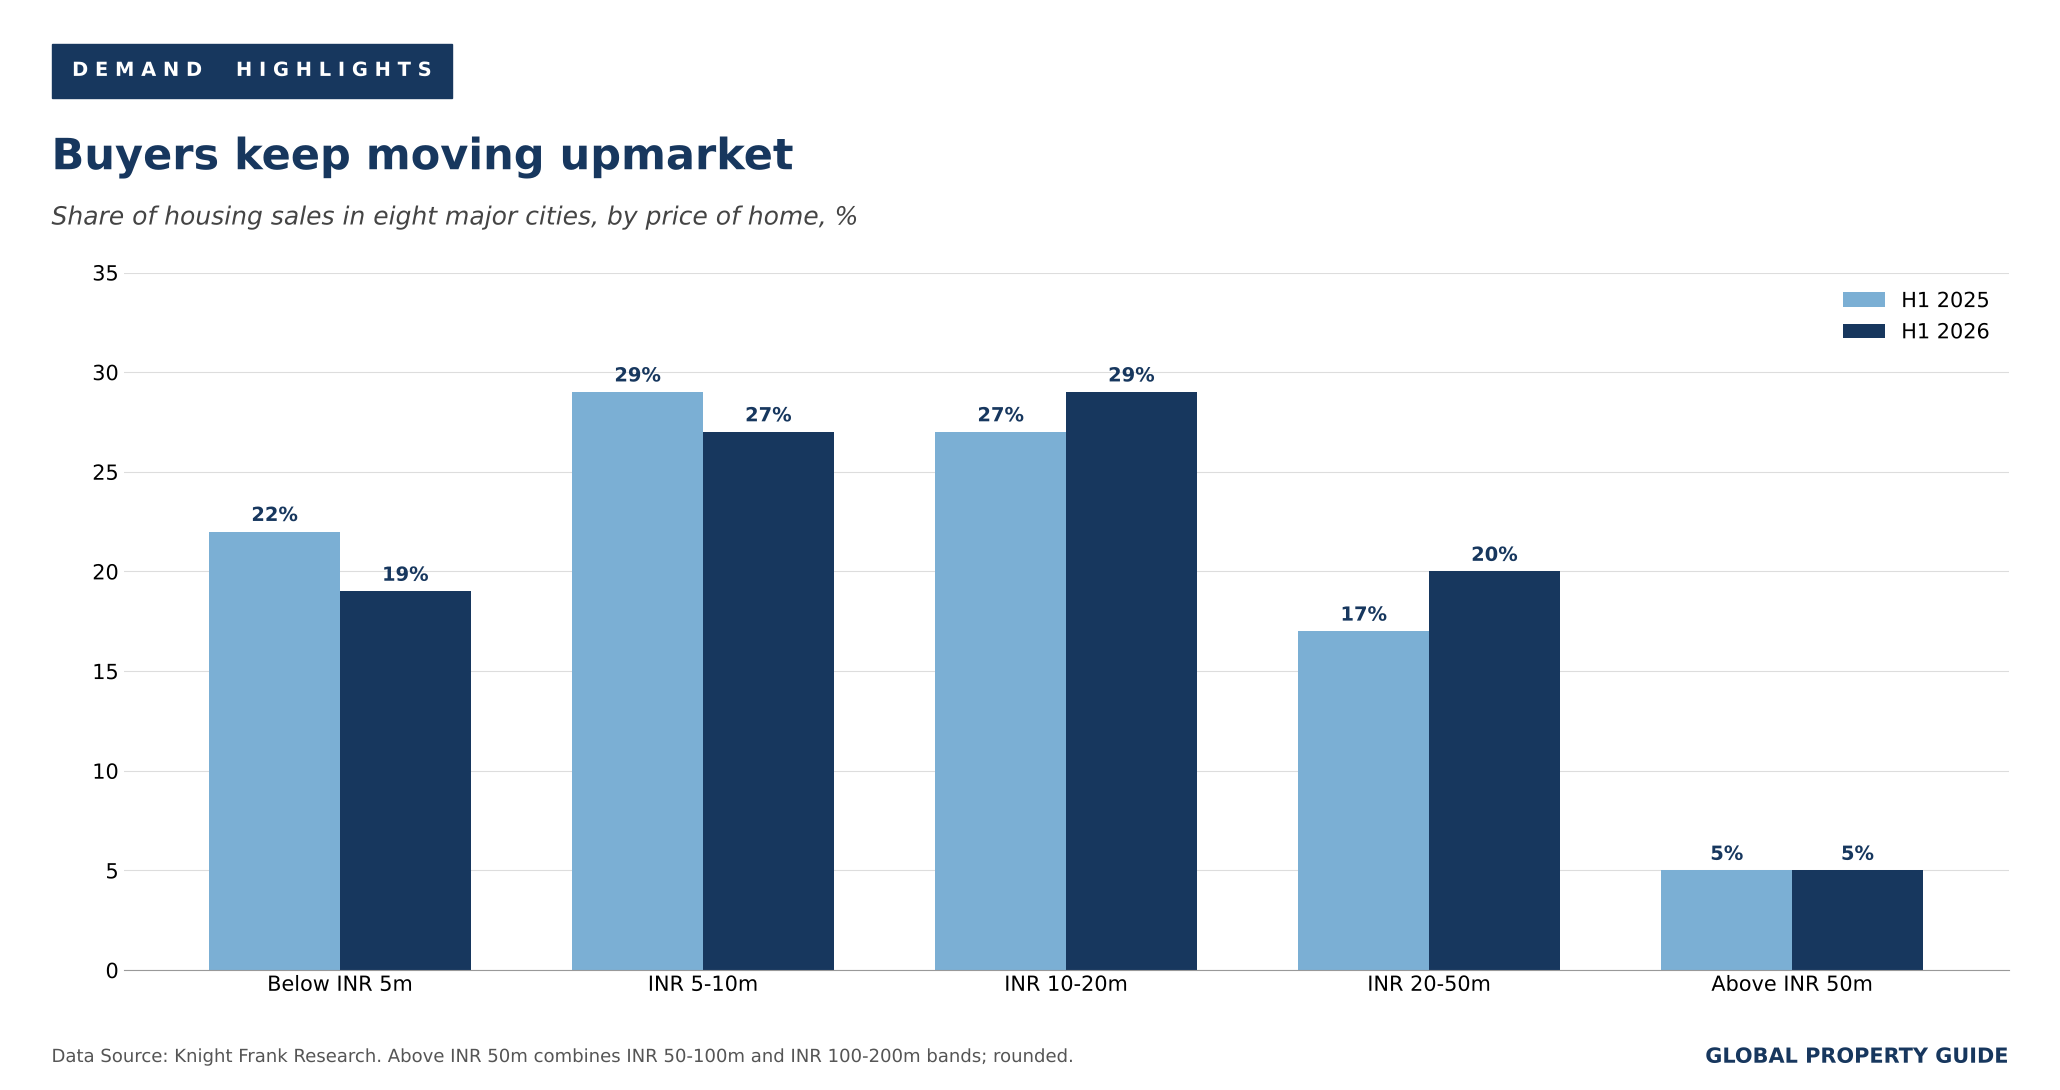
The shift toward more expensive homes has continued. Homes priced above INR 10 million (USD 104,856) made up 54% of sales in H1 2026, up from 49% a year earlier, according to Knight Frank. Sales of homes priced between INR 20 million and INR 50 million (USD 209,712 to USD 524,280) rose by 19%.
The cheaper segments lost ground. Homes priced below INR 5 million (USD 52,428) fell to 19% of sales, from 22% a year earlier. Homes priced between INR 5 million and INR 10 million fell to 27%, from 29%.
CBRE also found that high-end homes accounted for the largest share of sales, at 32% in Q2 2026, and that their sales rose by 4% from the previous quarter.
Knight Frank links buyers' caution to several factors: the pause in interest rate cuts, high global energy prices, the conflict in the Middle East and concerns about how artificial intelligence may change white-collar jobs. These worries have grown since the report was written in July. The RBI has since raised rates, and consumer inflation has climbed further.
At the same time, incomes and the economy are growing strongly. GDP rose by 7.8% in the year to Q1 2026-27, and home loan delinquencies remain very low (see below). "Moderation should not be mistaken for weakness," Knight Frank's chairman and managing director, Shishir Baijal, wrote in the H1 2026 report.
The government's main housing programme, Pradhan Mantri Awas Yojana-Urban (PMAY-U), continues to support lower-income households. Under the original scheme and its successor, 127.62 lakh (12.76 million) homes had been sanctioned and 98.65 lakh (9.87 million) completed by the end of June 2026, according to the Ministry of Housing and Urban Affairs. That means about 77% of sanctioned homes have been finished. Total investment under the scheme has reached INR 8.95 lakh crore (INR 8.95 trillion, USD 93.8 billion).
Under the second phase, PMAY-U 2.0, more than 16.13 lakh (1.61 million) homes had been approved by June 2026. Most of these (12.99 lakh) are homes built by the beneficiaries themselves with government help. Another 1.81 lakh are affordable homes built in partnership with developers, 1.20 lakh are supported through the interest subsidy scheme for home loans, and 12,846 are affordable rental homes.
Property Supply Trends
Developers are still launching more than they sell
Developers launched 187,350 new homes in the eight largest cities in H1 2026, 4% more than a year earlier, according to Knight Frank. That was 15,879 more homes than were sold. Launches have now exceeded sales for at least 14 quarters in a row, according to Knight Frank's Q1 2026 report.
In 2025 as a whole, 362,184 homes were launched, 3% fewer than in 2024.
Pune saw the biggest increase in launches in H1 2026, at 17%, followed by Mumbai at 8% and Bengaluru at 4%. Launches fell by 5% in the NCR and Kolkata and by 2% in Hyderabad. In the NCR and Kolkata, more homes were sold than launched.
Number of housing units launched in selected markets:
| City | Units Launched, H1 2026 |
YoY, % |
| Mumbai | 49,161 | 8% |
| Bengaluru | 34,749 | 4% |
| Pune | 31,116 | 17% |
| National Capital Region (NCR) | 23,877 | -5% |
| Hyderabad | 20,466 | -2% |
| Ahmedabad | 11,077 | 3% |
| Chennai | 9,588 | -0.3% |
| Kolkata | 7,316 | -5% |
| Total | 187,350 | 4% |
| Data source: Knight Frank Research. | ||
CBRE counted about 63,780 launches in Q2 2026 and about 138,800 in H1 2026. Mumbai, Pune and Bengaluru together accounted for 67% of Q2 launches, according to CBRE. High-end homes were the largest segment, at 35% of apartment launches in H1 2026. CBRE says developers are increasingly launching projects in phases, sometimes one tower at a time, to match supply to demand.
Unsold stock is rising at the top end
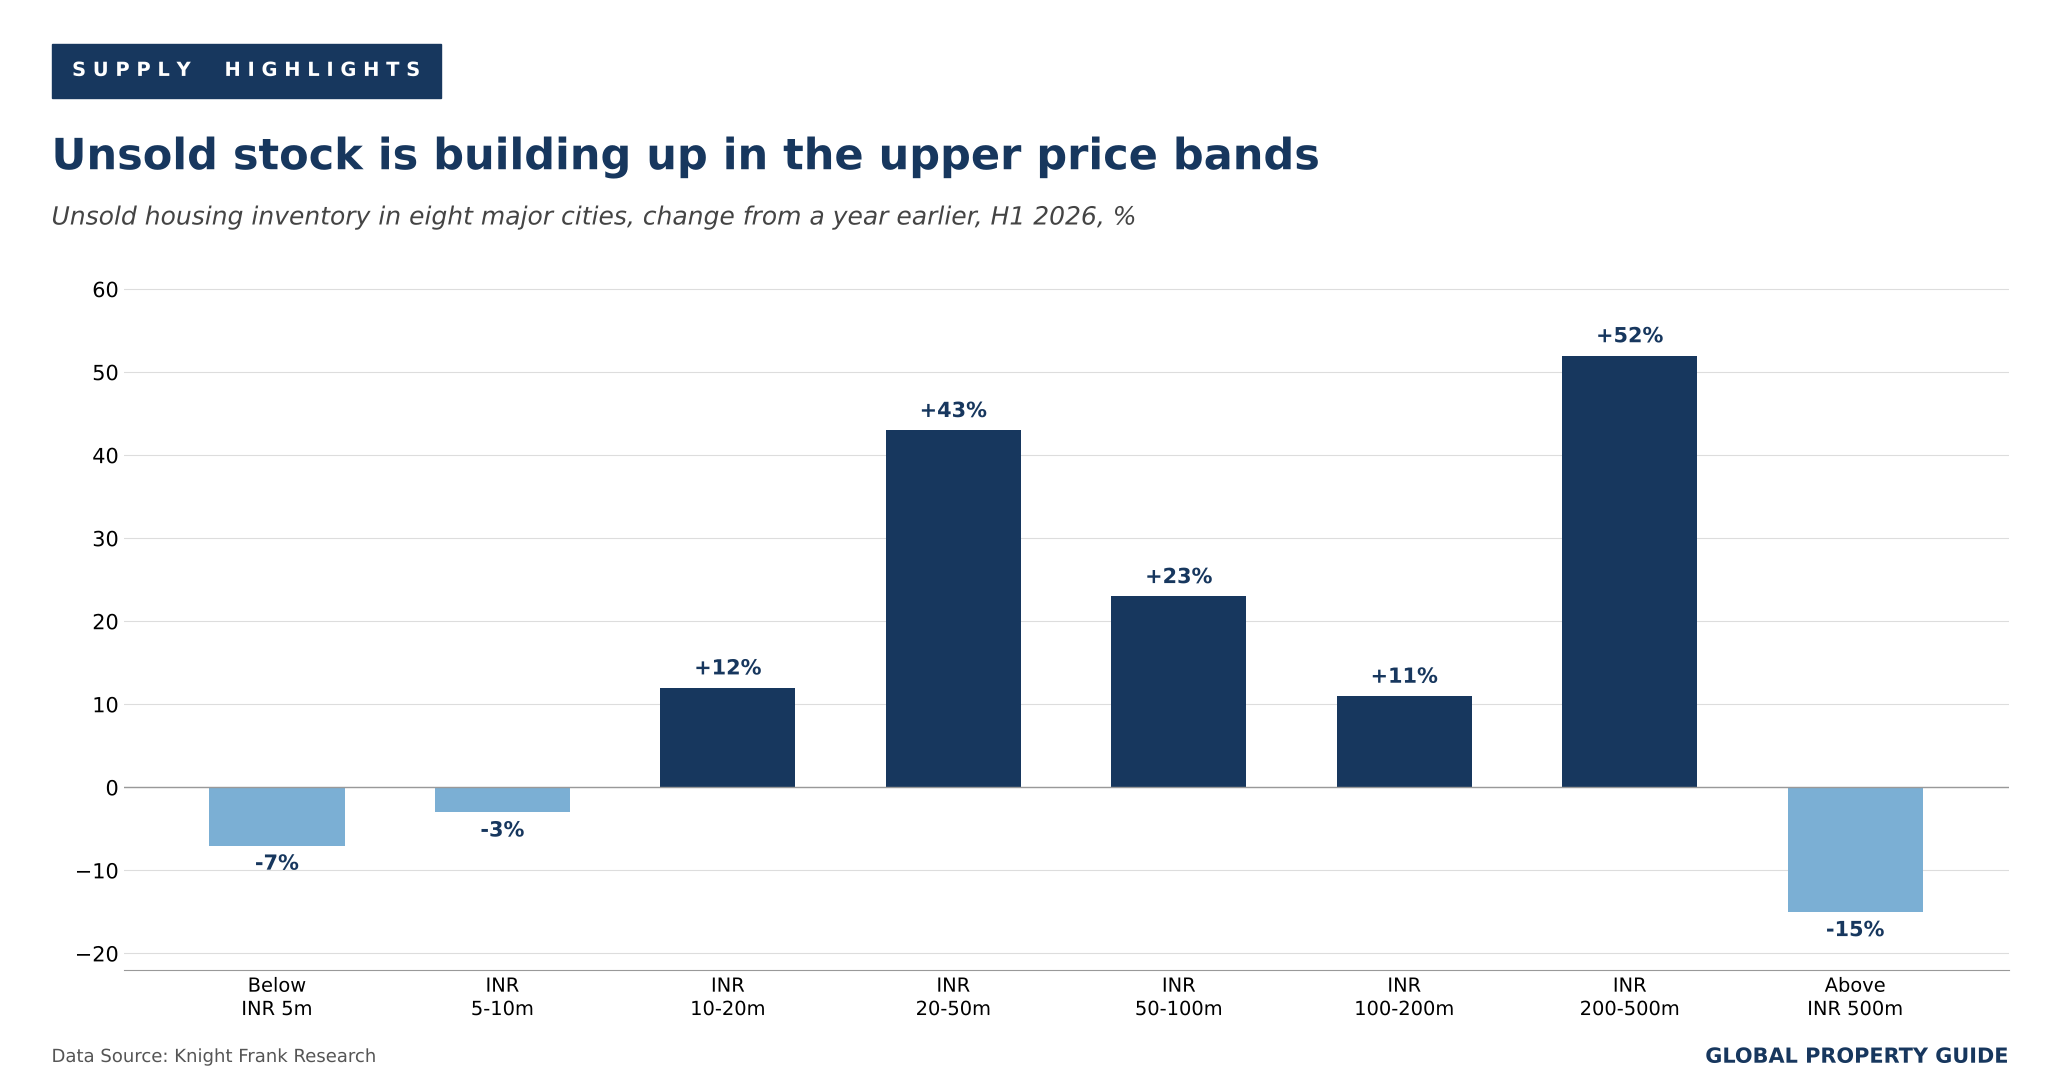
Because launches keep running ahead of sales, unsold stock is growing. At the end of June 2026, there were 525,695 unsold homes in the eight cities, 4% more than a year earlier, according to Knight Frank. At the current pace of sales, it would take 6.0 quarters (18 months) to sell them all, up from 5.8 quarters at the end of 2025.
The build-up is concentrated in the more expensive segments. Unsold stock of homes priced between INR 20 million and INR 50 million rose by 43% from a year earlier, and stock of homes priced between INR 200 million and INR 500 million rose by 52%. By contrast, unsold stock fell by 7% for homes below INR 5 million and by 3% for homes between INR 5 million and INR 10 million.
Unsold stock rose fastest in Bengaluru (up 22%) and Pune (up 19%), where launches have been strong. It fell in Kolkata (down 9%), Mumbai (down 4%), and the NCR (down 1%). Homes take the longest to sell in Ahmedabad (8.1 quarters) and the NCR (7.9 quarters), and are quickest to sell in Chennai and Kolkata (4.4 quarters each).
Unsold inventory in major markets, by city:
| City | Unsold Inventory, H1 2026 |
YoY, % | Quarters to Sell (QTS) |
| Mumbai | 157,410 | -4% | 6.5 |
| NCR | 103,984 | -1% | 7.9 |
| Bengaluru | 74,299 | 22% | 5.3 |
| Pune | 57,879 | 19% | 4.5 |
| Hyderabad | 56,095 | 3% | 5.9 |
| Ahmedabad | 37,727 | 10% | 8.1 |
| Chennai | 19,722 | 13% | 4.4 |
| Kolkata | 18,578 | -9% | 4.4 |
| Total | 525,695 | 4% | 6.0 |
| Data source: Knight Frank Research. | |||
The stock is getting newer, however. The average age of unsold homes fell to 13.5 quarters, from 14.3 quarters a year earlier, Knight Frank said. That means more of the unsold homes are recent launches rather than old projects that have struggled to sell.
Knight Frank expects launches to keep running ahead of sales in H2 2026. If sales do not recover, it says, unsold stock will rise further, and developers will rely more on incentives to sell. CBRE is more positive and expects the balance between supply and demand to keep the market stable through 2026.
Rental Market: Rents and Rental Yields
Rental yields have edged up
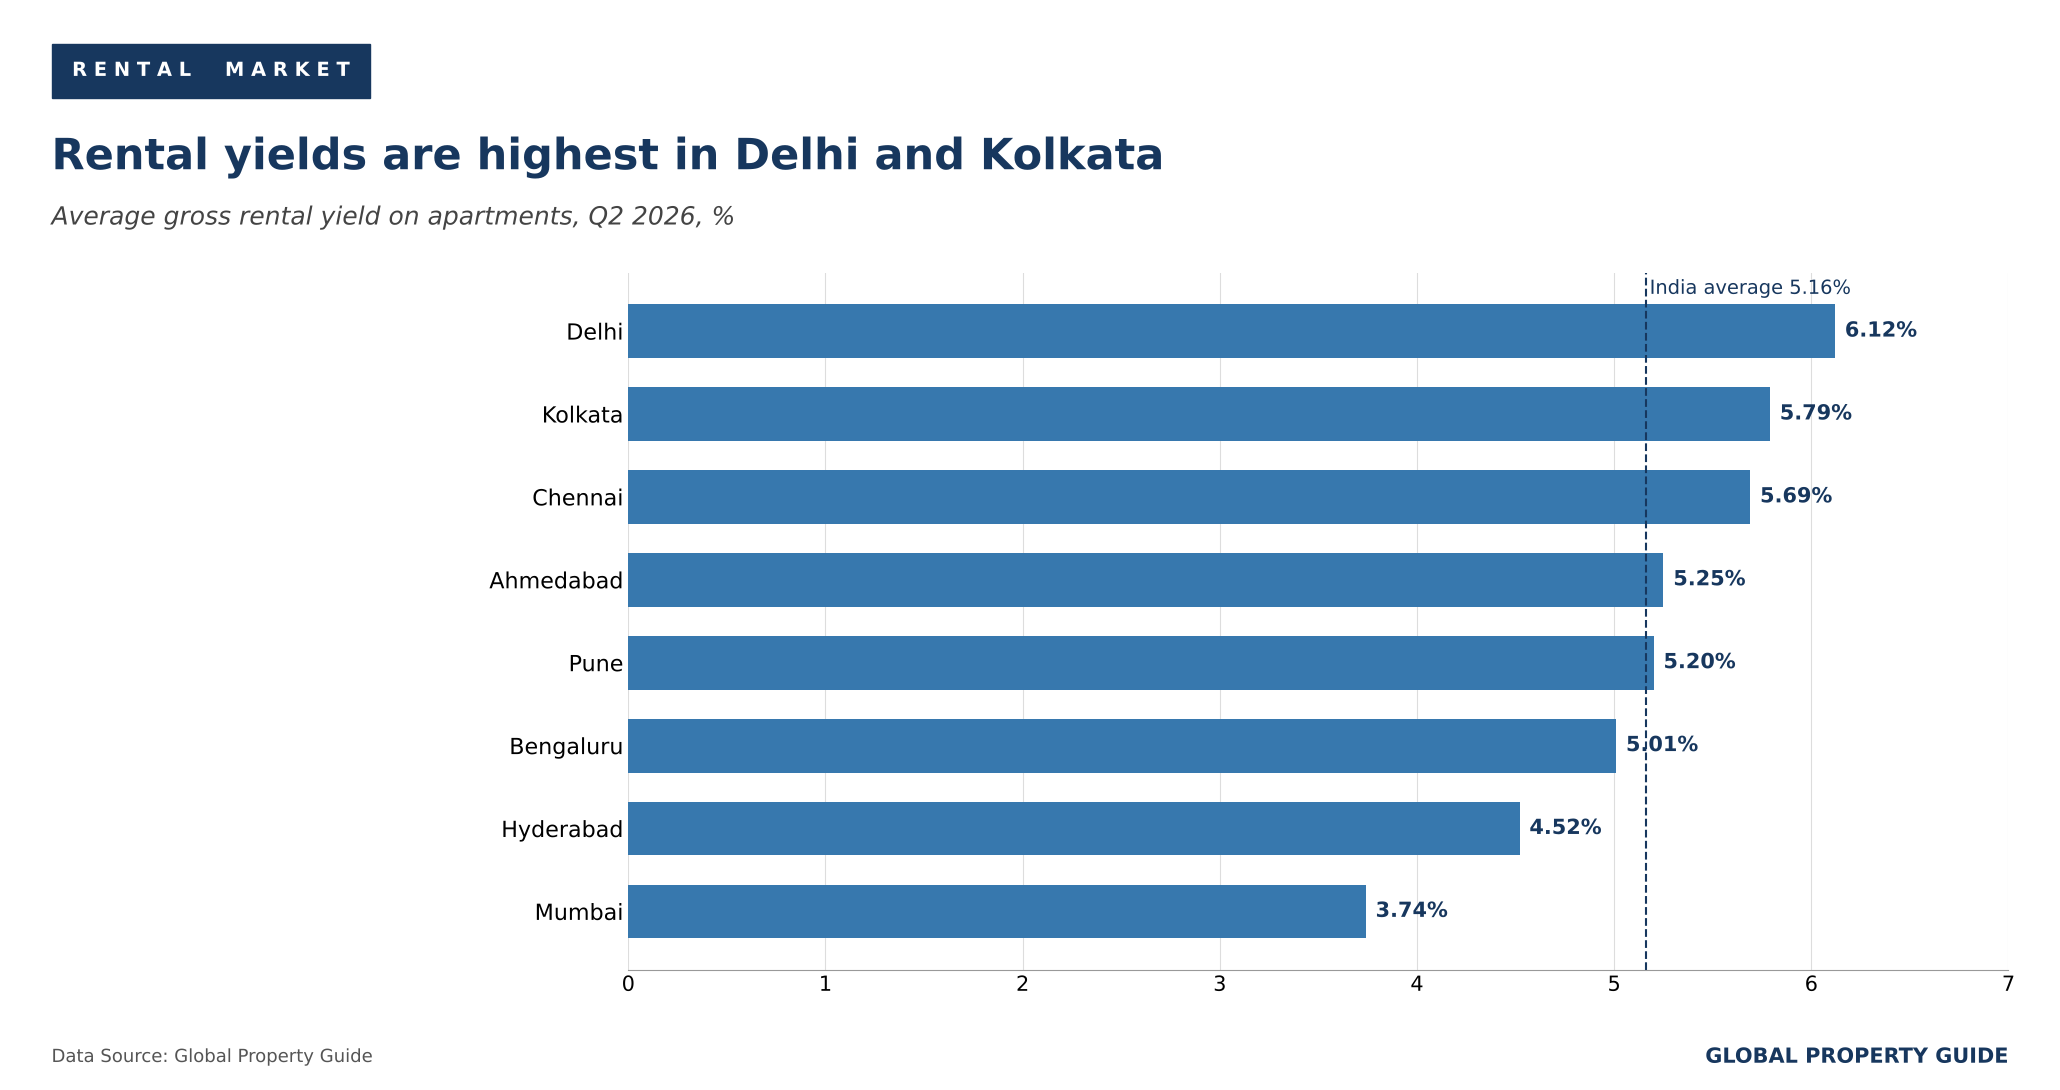
Gross rental yields on apartments in India averaged 5.16% in Q2 2026, up from 5.09% in Q4 2025, according to research by Global Property Guide.
Yields are highest in Delhi, at 6.12%, up from 5.81% in our previous edition. Kolkata is next at 5.79% and Chennai at 5.69%. Ahmedabad (5.25%), Pune (5.20%) and Bengaluru (5.01%) are close to the national average. Hyderabad (4.52%) and especially Mumbai (3.74%), the country's most expensive market, offer the lowest yields.
Rents in Indian cities remain low in dollar terms. Typical monthly rents for a one-bedroom apartment range from around USD 100 in Kolkata to around USD 320 in Bengaluru, according to Global Property Guide research. A two-bedroom apartment typically rents for USD 250 to USD 470 a month, and a three-bedroom apartment for USD 390 to USD 670.
Typical monthly rents by apartment size:
| City | 1-bedroom | 2-bedroom | 3-bedroom |
| Bengaluru | USD 320 | USD 470 | USD 670 |
| Pune | USD 280 | USD 360 | USD 530 |
| Delhi | USD 180 | USD 330 | USD 610 |
| Hyderabad | USD 190 | USD 320 | USD 620 |
| Chennai | USD 190 | USD 260 | USD 520 |
| Ahmedabad | USD 190 | USD 280 | USD 390 |
| Kolkata | USD 100 | USD 250 | USD 510 |
| Data source: Global Property Guide, Q2 2026. | |||
Gross yields do not take into account taxes, maintenance, agents' fees, and other costs. Net yields are typically 1.5 to 2 percentage points lower.
Housing costs are rising more slowly than other prices
Official data suggest that overall housing costs are rising less quickly than prices in general. In September 2026, the housing component of the consumer price index, which also covers water, electricity, gas and other fuels, was up 2.74% from a year earlier, according to the Ministry of Statistics and Programme Implementation (MoSPI). Housing costs rose by 2.33% in urban areas and 3.44% in rural areas. Overall consumer prices rose by 5.54%.
Most of India's housing policy aims to help people buy, not rent. Under PMAY-U 2.0, only 12,846 of the more than 16 lakh approved homes were affordable rental homes by June 2026, according to the Ministry of Housing and Urban Affairs.
For people who cannot afford to buy, renting remains the main option. As home prices in the big cities continue to rise faster than in the rest of the country, and as interest rates turn up, more households may have to keep renting for longer.
Mortgage Market and Interest Rates
The RBI has started raising rates again
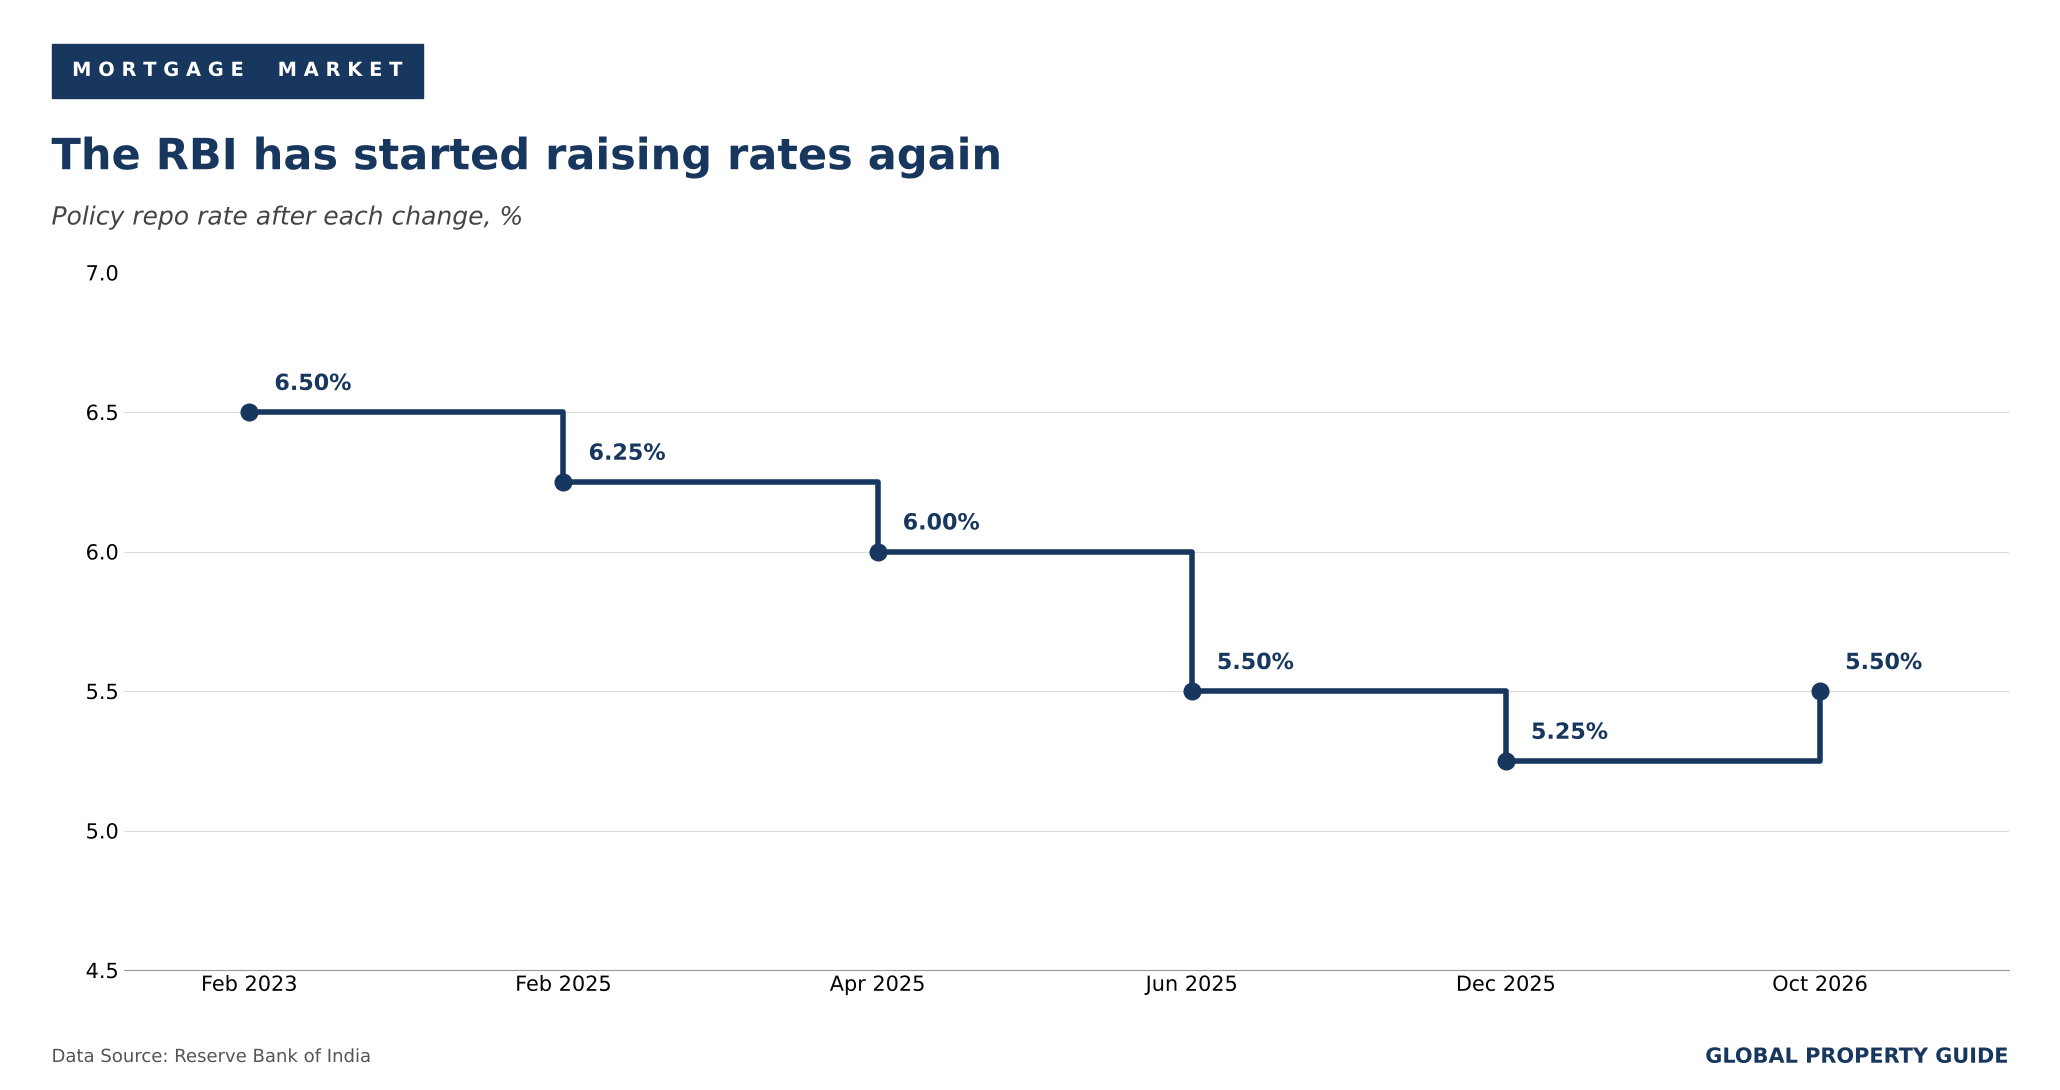
On 7 October 2026, the RBI raised its policy repo rate by 25 basis points to 5.50%, according to the Monetary Policy Committee's resolution. It was the first increase since February 2023. The standing deposit facility rate rose to 5.25%, and the marginal standing facility rate and the Bank Rate to 5.75%.
India's mortgage loan interest rates:
The committee also changed its stance from neutral to "calibrated tightening". "Rate cuts are off the table in the near term and policy action ahead can only be a rate hike or a pause," it said. The decision to raise rates was unanimous, but two of the six members, Nagesh Kumar and Ram Singh, wanted to keep the neutral stance.
This is a sharp change from a year ago. Between February and December 2025, the RBI cut its repo rate four times, from 6.50% to 5.25%. It then kept the rate unchanged at its meetings in April, June and August 2026, while warning each time that the risks to inflation were growing.
"Inflation and its outlook are not benign as they were last year," the committee said in October. It pointed to the "re-escalation of the conflict in West Asia and the consequent sharp volatility in crude oil prices", a weak south-west monsoon and strong El Niño conditions, which threaten farm output and food prices. It also noted that the US Federal Reserve had raised rates in September, and that money and credit were growing strongly in India. "In this milieu, recalibrating the policy rate is imperative," the committee said.
The RBI now expects consumer inflation to average 5.2% in 2026-27, with a peak of 6.0% in October to December 2026. In April, it had forecast 4.6%. The RBI's inflation target is 4%.
Most floating-rate home loans in India are linked to an external benchmark, usually the repo rate, so a change in the policy rate passes quickly to borrowers. Borrowers who benefited from lower payments in 2025 will now see them rise again, and new borrowers will face higher rates than at the start of the year.
Home lending is still growing strongly
Home loans are still growing quickly. Lenders issued 36.4 lakh (3.64 million) new home loans worth INR 11.81 lakh crore (INR 11.81 trillion, USD 123.9 billion) in the financial year 2025-26, which ended in March 2026, according to the credit bureau CRIF High Mark. That was 12.3% more by value and 6.8% more by number than a year earlier. This was a clear pick-up from 2024-25, when the value of new home loans grew by only 2.7%.
Total outstanding home loans reached INR 44.4 lakh crore (USD 465.6 billion) in March 2026, up 9.4% from a year earlier, CRIF High Mark said. Public sector banks provided 44.5% of the value of new home loans in the January to March quarter.
As buyers move upmarket, loans are getting bigger. Loans of INR 7.5 million (USD 78,642) or more accounted for 40.7% of the value of new home loans in the January to March 2026 quarter, up from 33.6% two years earlier. By number, loans of INR 0.5 million to INR 3.5 million still made up more than half (53.7%) of new loans.
Loan quality remains very good. Only 0.2% of outstanding home loans were 91 to 180 days overdue in March 2026, CRIF High Mark said.
Credit as a whole has been growing faster this year. In August 2026, non-food bank credit was 18.8% higher than a year earlier, up from 10.2% a year before, according to the RBI. Personal loans grew by 16.9%, and housing loans "sustained double-digit growth", the RBI said.
Lending by non-bank finance companies, which include housing finance companies, rose by 15.8% in August, and their retail loans by 22.0%, according to the RBI, which said growth in housing loans had accelerated. Strong credit growth was one of the reasons the RBI gave for raising rates.
Economic and Social Factors
The economy is growing strongly
India's economy grew by 7.8% in the year to Q1 2026-27 (April to June 2026), up from 6.9% a year earlier, according to MoSPI. Gross value added rose by 8.2%. Construction grew by 7.7%, and the sector that includes finance, real estate and the ownership of dwellings grew by 12.1%. Investment, measured by gross fixed capital formation, rose by 11.9%, and household consumption rose by 7.1%.
Forecasters have raised their expectations. In October 2026, the International Monetary Fund (IMF) projected growth of 7.0% in the financial year 2026-27 and 7.0% in 2027-28, after 7.8% in 2025-26. In July, the IMF had forecast only 6.4% for 2026-27. The RBI now expects growth of 7.1% in 2026-27, up from 6.6% in June.
India is doing better than much of the world. The IMF expects global growth of 3.1% in 2026, and warns that energy-importing economies face some of the hardest conditions, according to its World Economic Outlook.
Inflation has doubled, while jobs hold steady
Consumer price inflation has risen every month in 2026. It was 2.74% in January and reached 5.54% in September, the highest so far this year, according to MoSPI. Food prices were the main driver, rising by 7.74%, up from 5.97% in August. Inflation was higher in rural areas (6.08%) than in cities (4.88%).
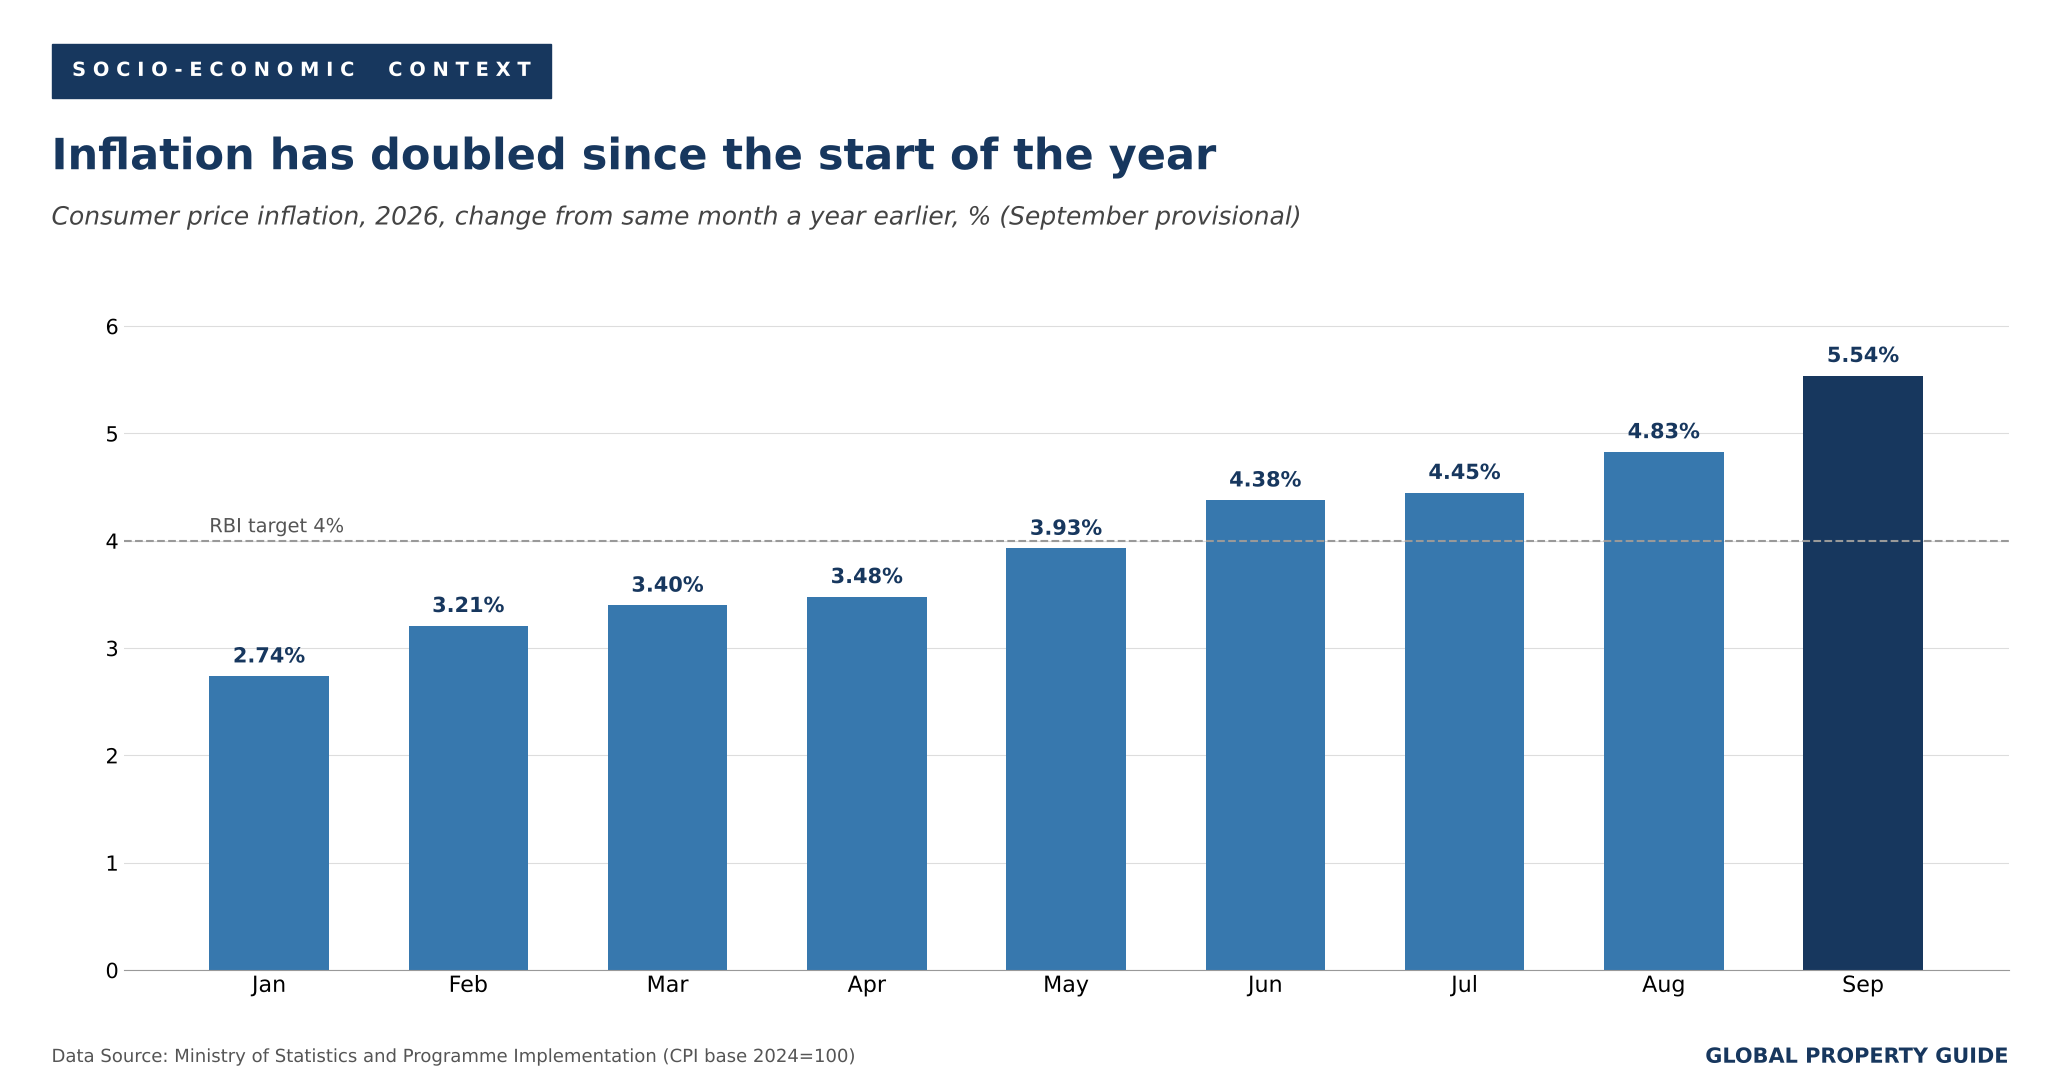
Higher oil prices, linked to the conflict in the Middle East, and a weak monsoon have both pushed prices up. The weaker rupee also makes imports more expensive.
Unemployment has been broadly stable. In June 2026, the unemployment rate for people aged 15 and over was 5.5%, unchanged from May, according to the Periodic Labour Force Survey published by MoSPI. The rate was 6.6% in urban areas and 5.0% in rural areas. Labour force participation was 54.4%.
India's strong growth gives the housing market a solid base. But the risks have shifted. Higher interest rates will make mortgages more expensive at a time when prices in the big cities are already stretching buyers' budgets. Inflation is expected to rise further toward the end of 2026, and the RBI has said its next move can only be another increase or a pause. A weaker rupee and higher energy costs add to the pressure.
For foreign buyers, the main changes since our last edition are the weaker rupee, which has lowered dollar prices, and the end of falling interest rates.
Sources:
- Reserve Bank of India (RBI)
- All-India House Price Index (HPI) for Q1:2026-27: rbi.org.in
- All-India House Price Index for Q4:2025-26: rbi.org.in
- All-India House Price Index (HPI) Q2:2025-26: rbi.org.in
- Monetary Policy Statement, Resolution of the Monetary Policy Committee, October 5 to 7, 2026: rbi.org.in
- Resolution of the Monetary Policy Committee, August 3 to 5, 2026: rbi.org.in
- Resolution of the Monetary Policy Committee, June 3 to 5, 2026: rbi.org.in
- Resolution of the Monetary Policy Committee, April 6 to 8, 2026: rbi.org.in
- Sectoral Deployment of Bank Credit, August 2026: rbi.org.in
- Sectoral Deployment of Credit by NBFC, August 2026: rbi.org.in
- Handbook of Statistics on Indian Economy, Table 223, Daily Exchange Rate of the Indian Rupee: rbi.org.in
- Current Rates (FBIL reference rate and policy rates): rbi.org.in
- Knight Frank
- India Real Estate, Office and Residential Market, H1 2026: content.knightfrank.com
- India Real Estate, Office and Residential Market, Jan-Mar 2026: content.knightfrank.com
- CBRE
- India Market Monitor Q2 2026, Residential: mktgdocs.cbre.com
- CRIF High Mark
- How India Lends, Credit Landscape in India, Q4 FY26 and FY 2026: crifhighmark.com
- Press Information Bureau, Government of India
- MoSPI, Press Release of Consumer Price Index on Base 2024=100 for September 2026: pib.gov.in
- MoSPI, Press Note on GDP Estimates for Q1 2026-27: static.pib.gov.in
- MoSPI, Press Note on Periodic Labour Force Survey Monthly Bulletin, June 2026: static.pib.gov.in
- Ministry of Housing and Urban Affairs (PMAY-Urban)
- PMAY-U Newsletter, 30 June 2026: pmay-urban.gov.in
- International Monetary Fund (IMF)
- Global Property Guide
- Gross Rental Yields in India: globalpropertyguide.com