Argentina Residential Real Estate Market Analysis 2026
Argentina's housing market has lost its engine. Sales are holding up, but the mortgage boom that carried the market through 2025 has broken, and apartment prices have stopped rising with it.
Table of Contents
- Property Prices and Price Index
- Historic Perspective
- House Price Variations
- Property Demand Trends
- Property Supply Trends
- Rental Market: Rents and Rental Yields
- Mortgage Market and Interest Rates
- Economic and Social Factors
Property Prices and Price Index
In Q2 2026, the average asking price of used two-room apartments in Buenos Aires rose by just 1.4% to US$2,343 per square metre (sqm) compared to a year earlier, according to the Institute of Statistics and Censuses of the Autonomous City of Buenos Aires (IDECBA). That was the ninth consecutive quarter of year-on-year growth, but it was also the weakest of the nine. A year ago, the same measure was rising by 5.3%.
Argentina's house price annual change:
Quarter-on-quarter, prices were essentially flat, up 0.2%. IDECBA reports that every used segment moved within a band of minus 0.3% to plus 0.3% over the quarter, and describes the result as confirmation that the market has reached a period of stability.
Deflated by Argentina's consumer price index, apartment prices fell by 24.0% year-on-year and by 6.1% over the quarter. These inflation-adjusted figures should be read with care. Argentine apartments are priced, marketed and transacted in US dollars, while the deflator is the peso consumer price index, so the real series largely measures peso inflation rather than any loss of value experienced by a dollar-denominated owner. The nominal dollar change is the more meaningful number for buyers and investors.
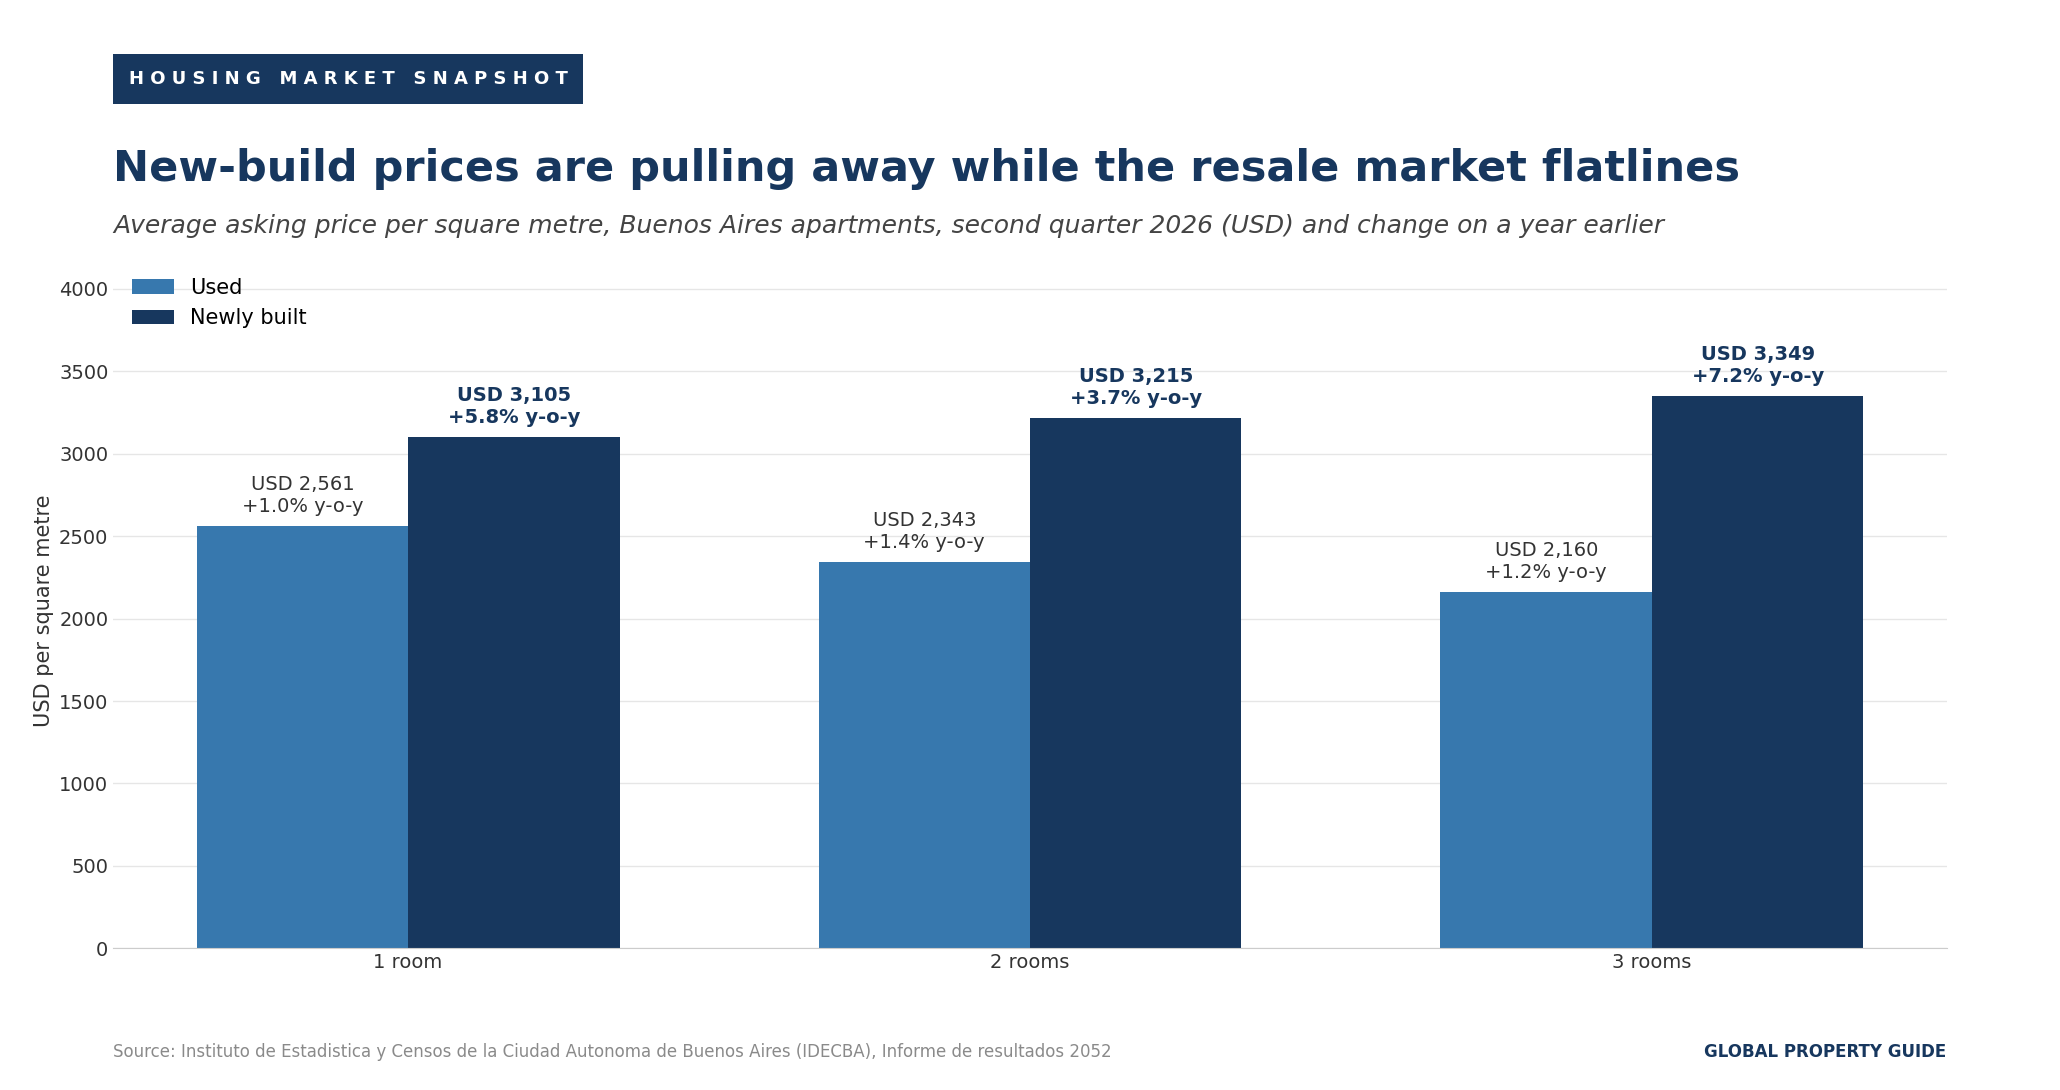
The stall is concentrated in the resale market. Newly built apartments continue to command much stronger increases: 5.8% for one-room units, 3.7% for two-room units and 7.2% for three-room units. IDECBA notes that new-build prices have closed to within 2.0% of their all-time series high, while used prices remain 19.0% below theirs. Two markets are now moving at different speeds within the same city.
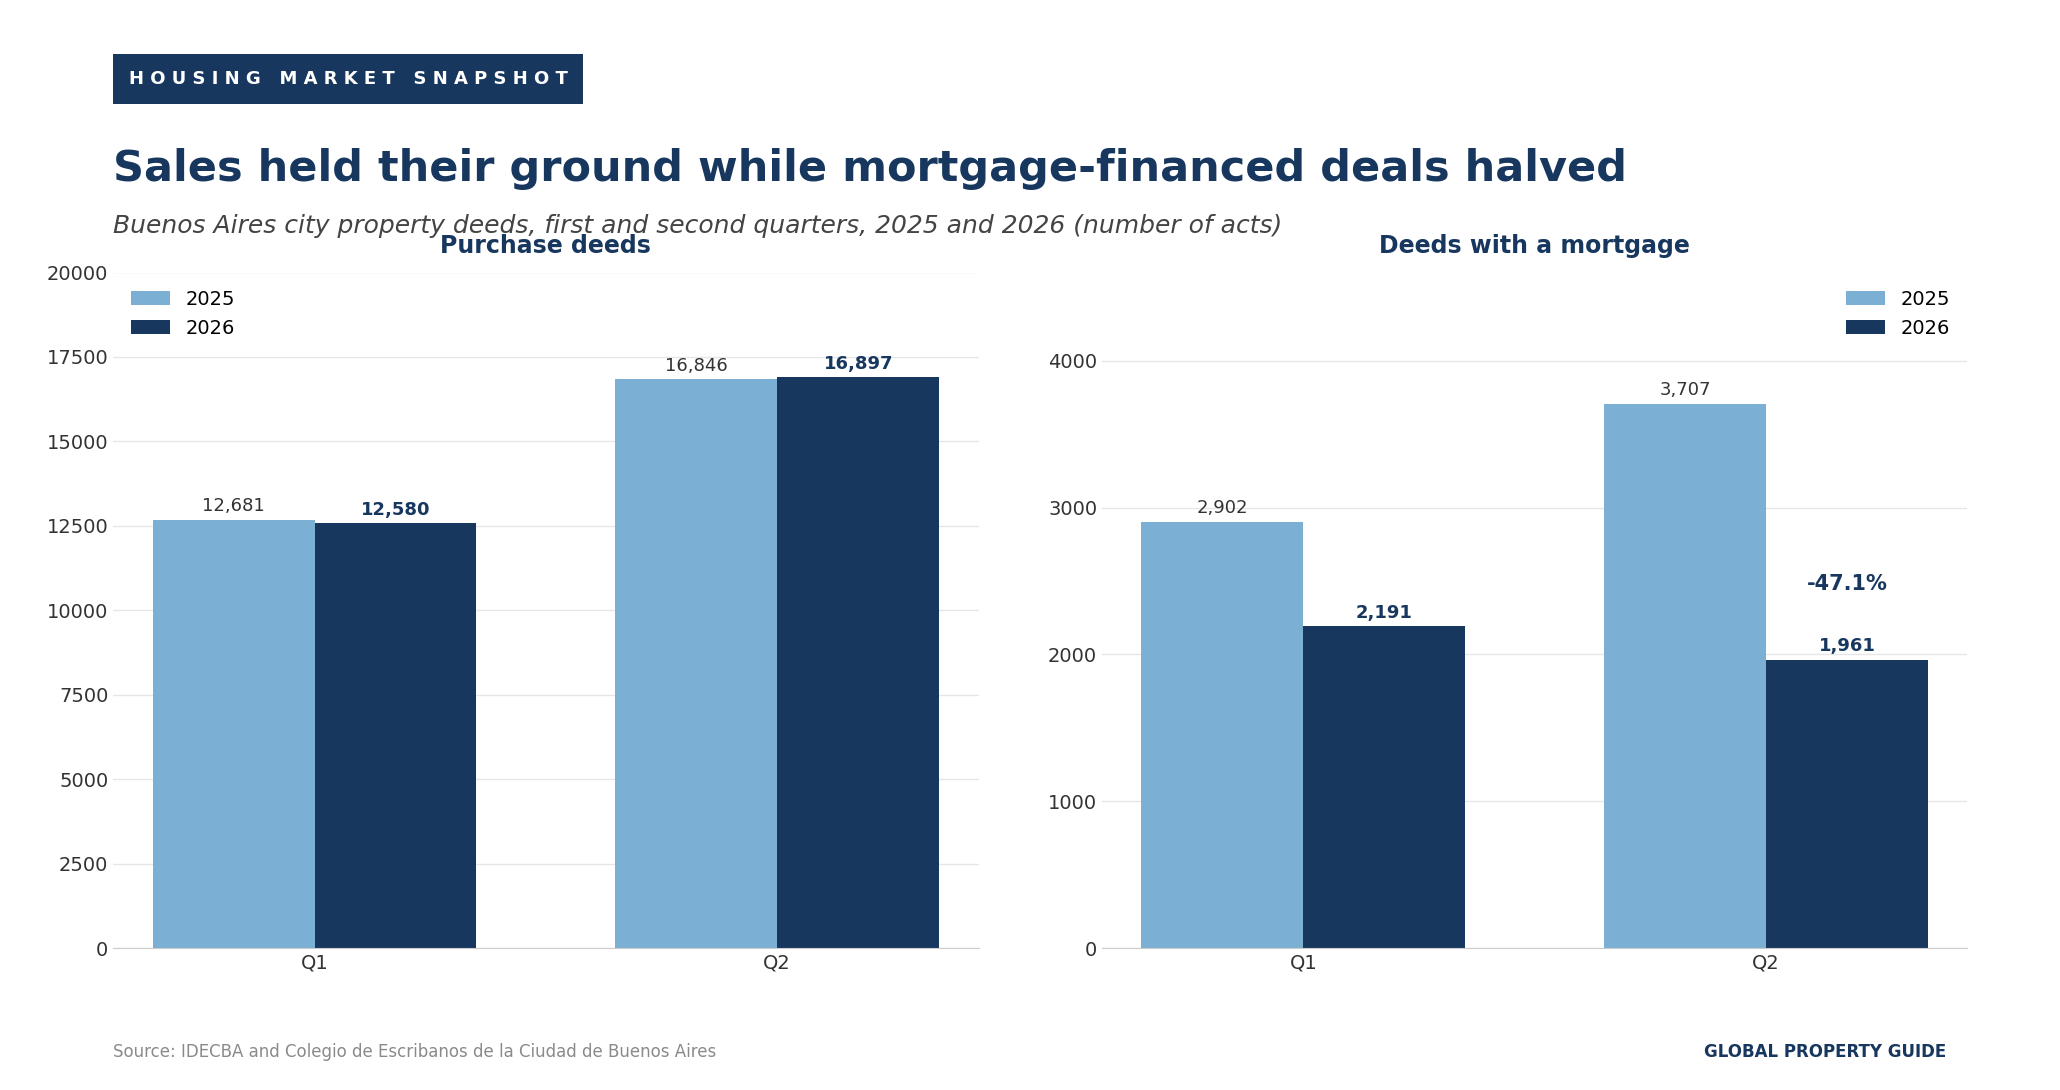
The cause of the stall is visible in the financing data. Mortgage-backed deeds in the capital fell by 47.1% year-on-year in Q2 2026, to 1,961 acts, after a 24.5% fall in Q1. IDECBA attributes the retreat to changes in the mortgage terms offered by the main public banks, introduced in the final days of 2025, against a very high base of comparison.
Purchase deeds themselves barely moved. Between April and June, the capital recorded 16,897 conveyances, up 0.3% year-on-year and still the best second quarter in 18 years. Buyers have not left the market. They have stopped borrowing to enter it.
Supply, meanwhile, keeps building. The stock of sale listings reached its highest level since the series began in 2015, surpassing the record set in Q3 2025.
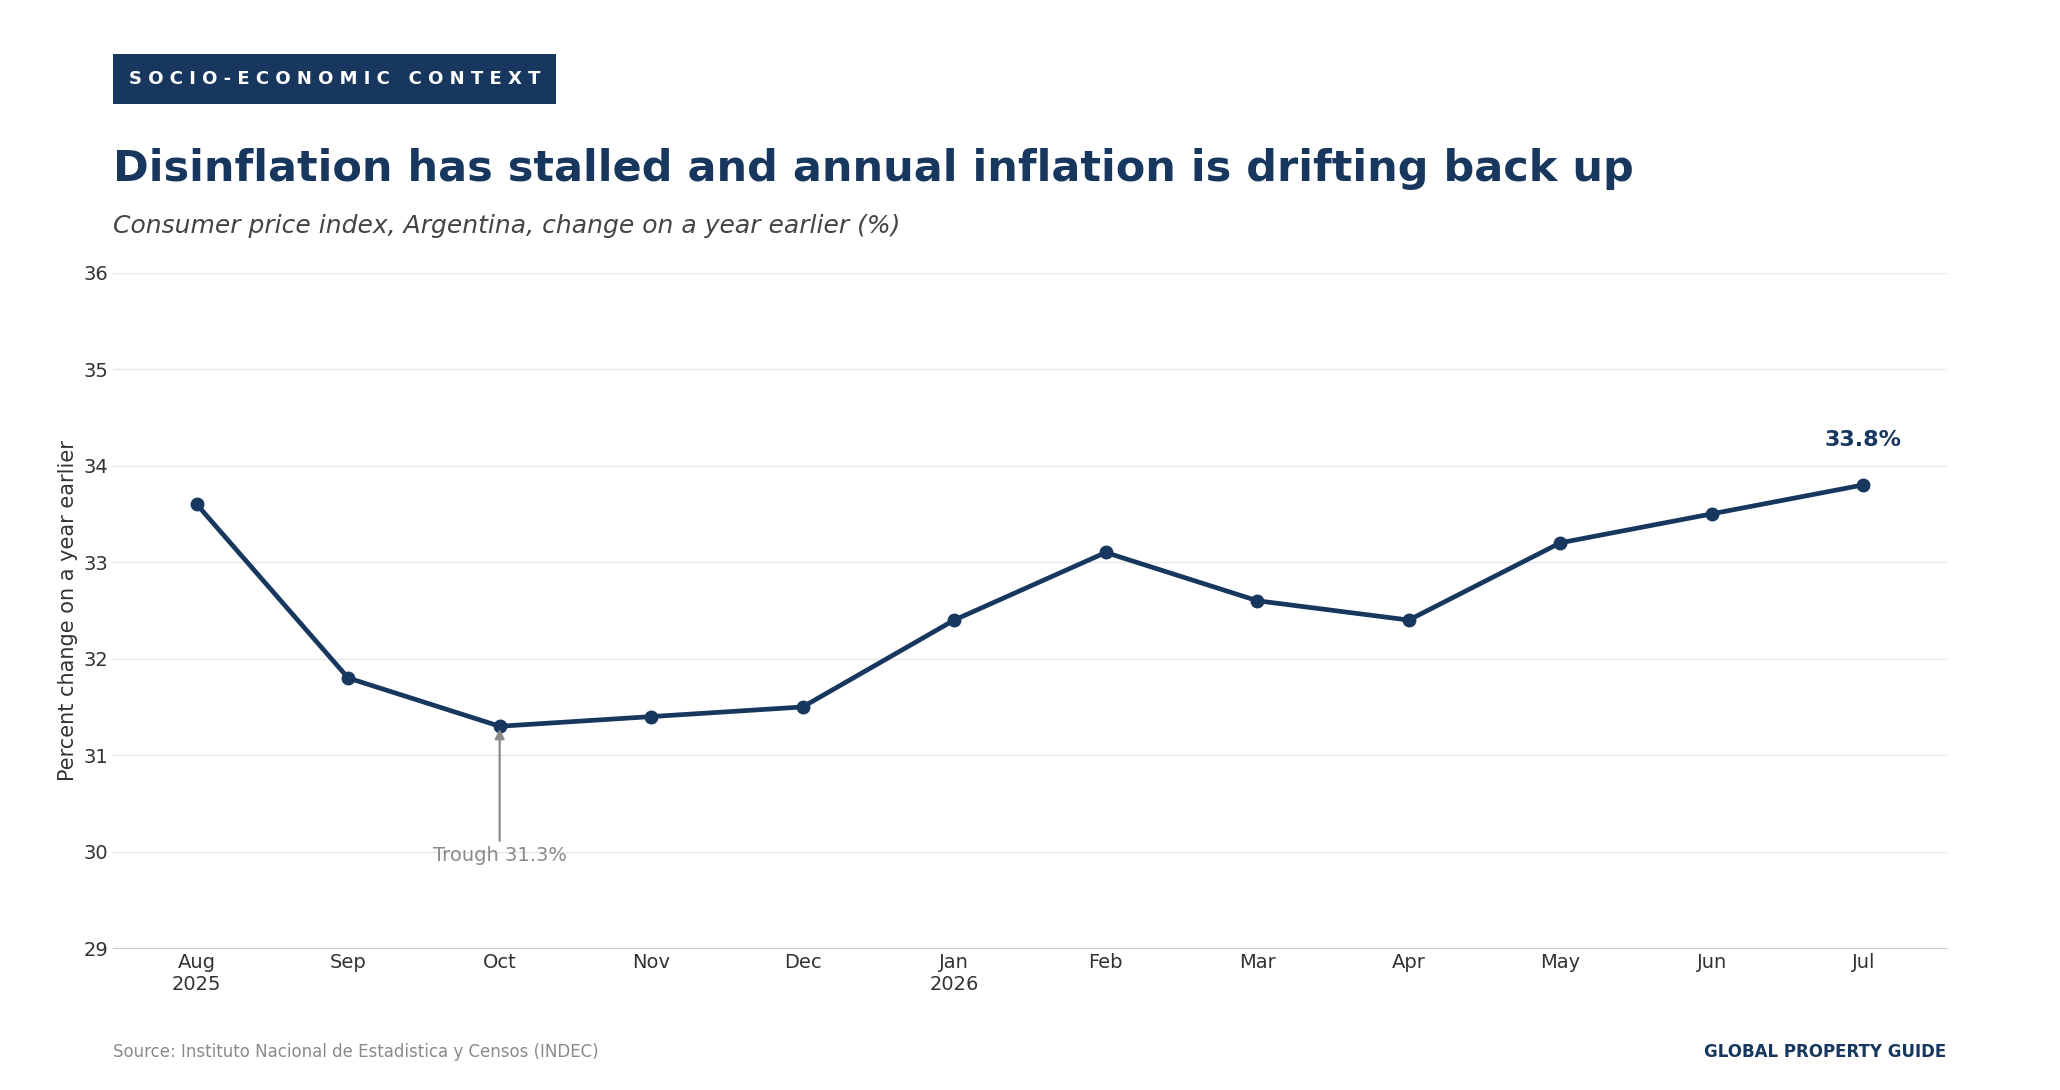
The backdrop is a macroeconomy that has stabilised without quite delivering. Inflation has stopped falling: the annual rate bottomed out at 31.3% in October 2025 and has drifted back up to 33.8% by July 2026. GDP grew 2.3% year-on-year in Q1 2026, but private forecasters expect a contraction in Q2. All three major rating agencies upgraded Argentina between May and July 2026, the first time they have moved in step in a decade.
Historic Perspective
How capital controls thwarted housing market growth
The lacklustre performance of Argentina's housing market over the past decade can be partly attributed to the imposition of capital controls.
Capital controls introduced in 2011 by then-President Cristina Fernández made it extremely difficult for most Argentines to acquire property. Sellers demanded to be paid in dollars, which had proven safer than the peso. Buyers were prevented from acquiring those dollars by strict currency controls. And the indexation of peso loans had been forbidden since 2004, at the height of Argentina's currency crisis.
Coupled with high inflation, these factors pushed the property market into a three-year crisis. In 2014, just 2,800 property sales per month were registered in Buenos Aires, a city of about 3 million people. That compares with 5,200 in 2010, 6,100 in 2007, and a historical average of 5,000, according to the Buenos Aires Notary College.
Argentina's very high inflation also made peso-denominated mortgage lending too risky for banks. In 2015, the number of new mortgages slumped to its lowest level in 15 years, accounting for just 1% of GDP, the lowest in Latin America, according to a report by the Housing Finance Information Network. That was down from 5.4% in 2000.
Immediately after taking office in December 2015, President Mauricio Macri began to reverse the economic legacy of his predecessor, devaluing the currency and lifting tight capital controls. Ironically, Macri reintroduced currency controls after his defeat in the August 2019 primary poll. On September 11, 2019, the central bank unveiled a new round of controls, capping individual dollar purchases at US$10,000 a month and requiring government permission to transfer money abroad. Within a month, the peso fell by 20% against the dollar.
From December 2015 to December 2019, the peso lost over 81% of its value against the US dollar, and it kept falling for another five years after that.
The dismantling of Argentina's currency controls
The decisive break came in April 2025, when the BCRA issued Communication A 8226, which substantially liberalised access to the official exchange market. Importers could settle payments immediately on customs clearance; service imports from unrelated foreign providers became payable on delivery; related-party waiting periods were halved from 180 to 90 days; companies could remit dividends abroad for the first time in years; and several parking restrictions on securities transactions were removed.
What has changed since the previous edition of this report is that the reform has held and has been reinforced. In October 2025, the BCRA and the United States Department of the Treasury signed a US$20 billion exchange stabilisation agreement. In December 2025, the central bank announced a re-monetisation phase for 2026, projecting an increase in the monetary base from 4.2% to 4.8% of GDP over the year.
The result is the most stable peso in a decade. The BCRA reference rate stood at ARS1,507.37 to the US dollar on September 4, 2026, against ARS1,362.33 twelve months earlier. That is a depreciation of 10.7%, or a loss of 9.6% of the peso's dollar value. In the four and a half years to August 2025, by contrast, the peso lost about 94% of its value.
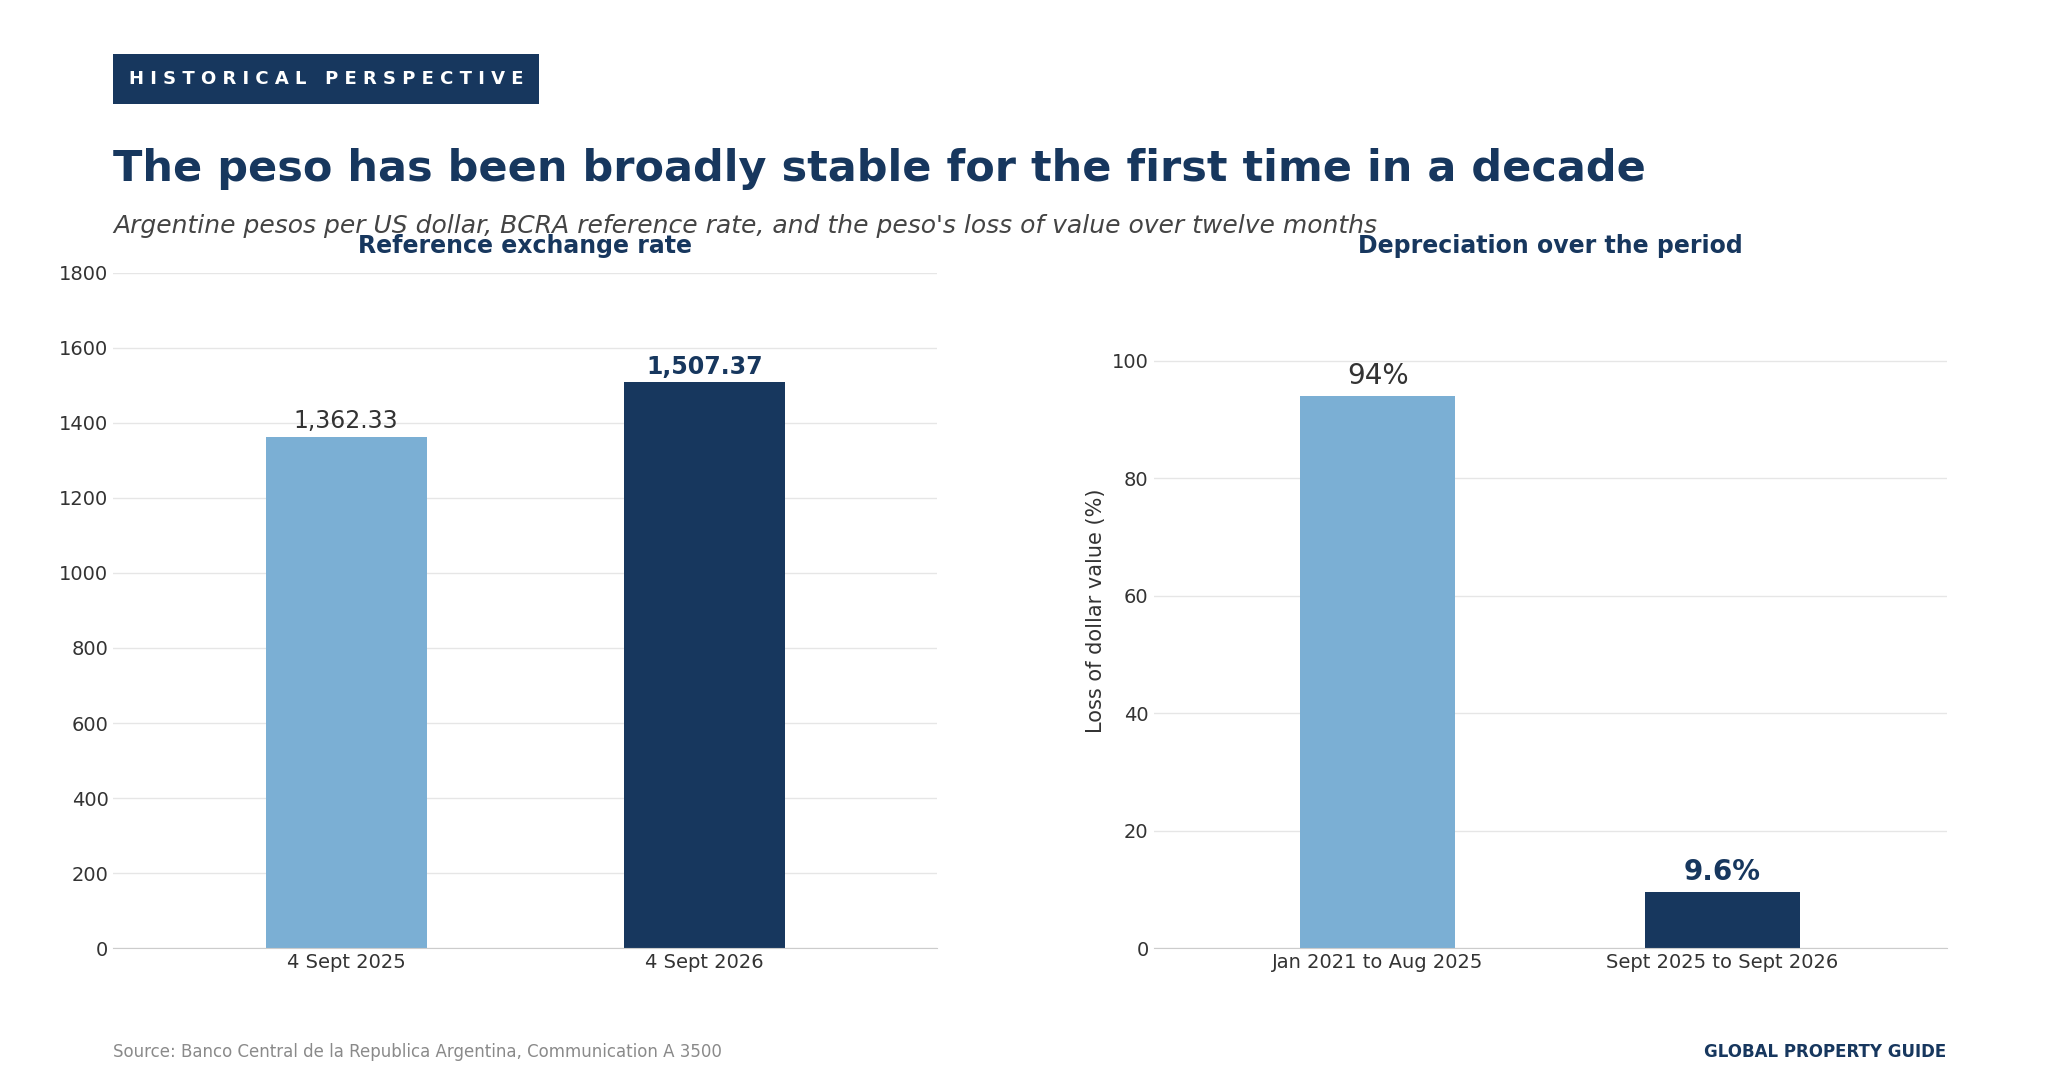
Since Argentina's real estate market has historically been transacted in US dollars, this matters. For most of the past fifteen years, every tightening of dollar access damaged the housing market. That constraint has now largely been removed. The binding constraint has shifted from foreign exchange to mortgage credit.
House Price Variations
Apartment prices in the major neighbourhoods of Buenos Aires
Residential property prices across the capital's neighbourhoods vary enormously. Puerto Madero remains far and away the most expensive, at more than four times the cheapest barrio in the city and roughly two and a half times the city average.
- In Puerto Madero, the average asking price of used two-room apartments fell by 3.4% year-on-year to US$5,805 per sqm in Q2 2026. The city's most expensive neighbourhood was among the weakest performers of the quarter.
- In Núñez, apartment prices rose by 10.1% year-on-year to US$3,266 per sqm, the second largest increase recorded anywhere in the city for this segment.
- In Palermo, prices were up by just 0.9% year-on-year to an average of US$3,118 per sqm.
- In Belgrano, prices rose by 2.9% year-on-year to US$2,958 per sqm.
- In Caballito, prices were up by 0.9% to an average of US$2,317 per sqm.
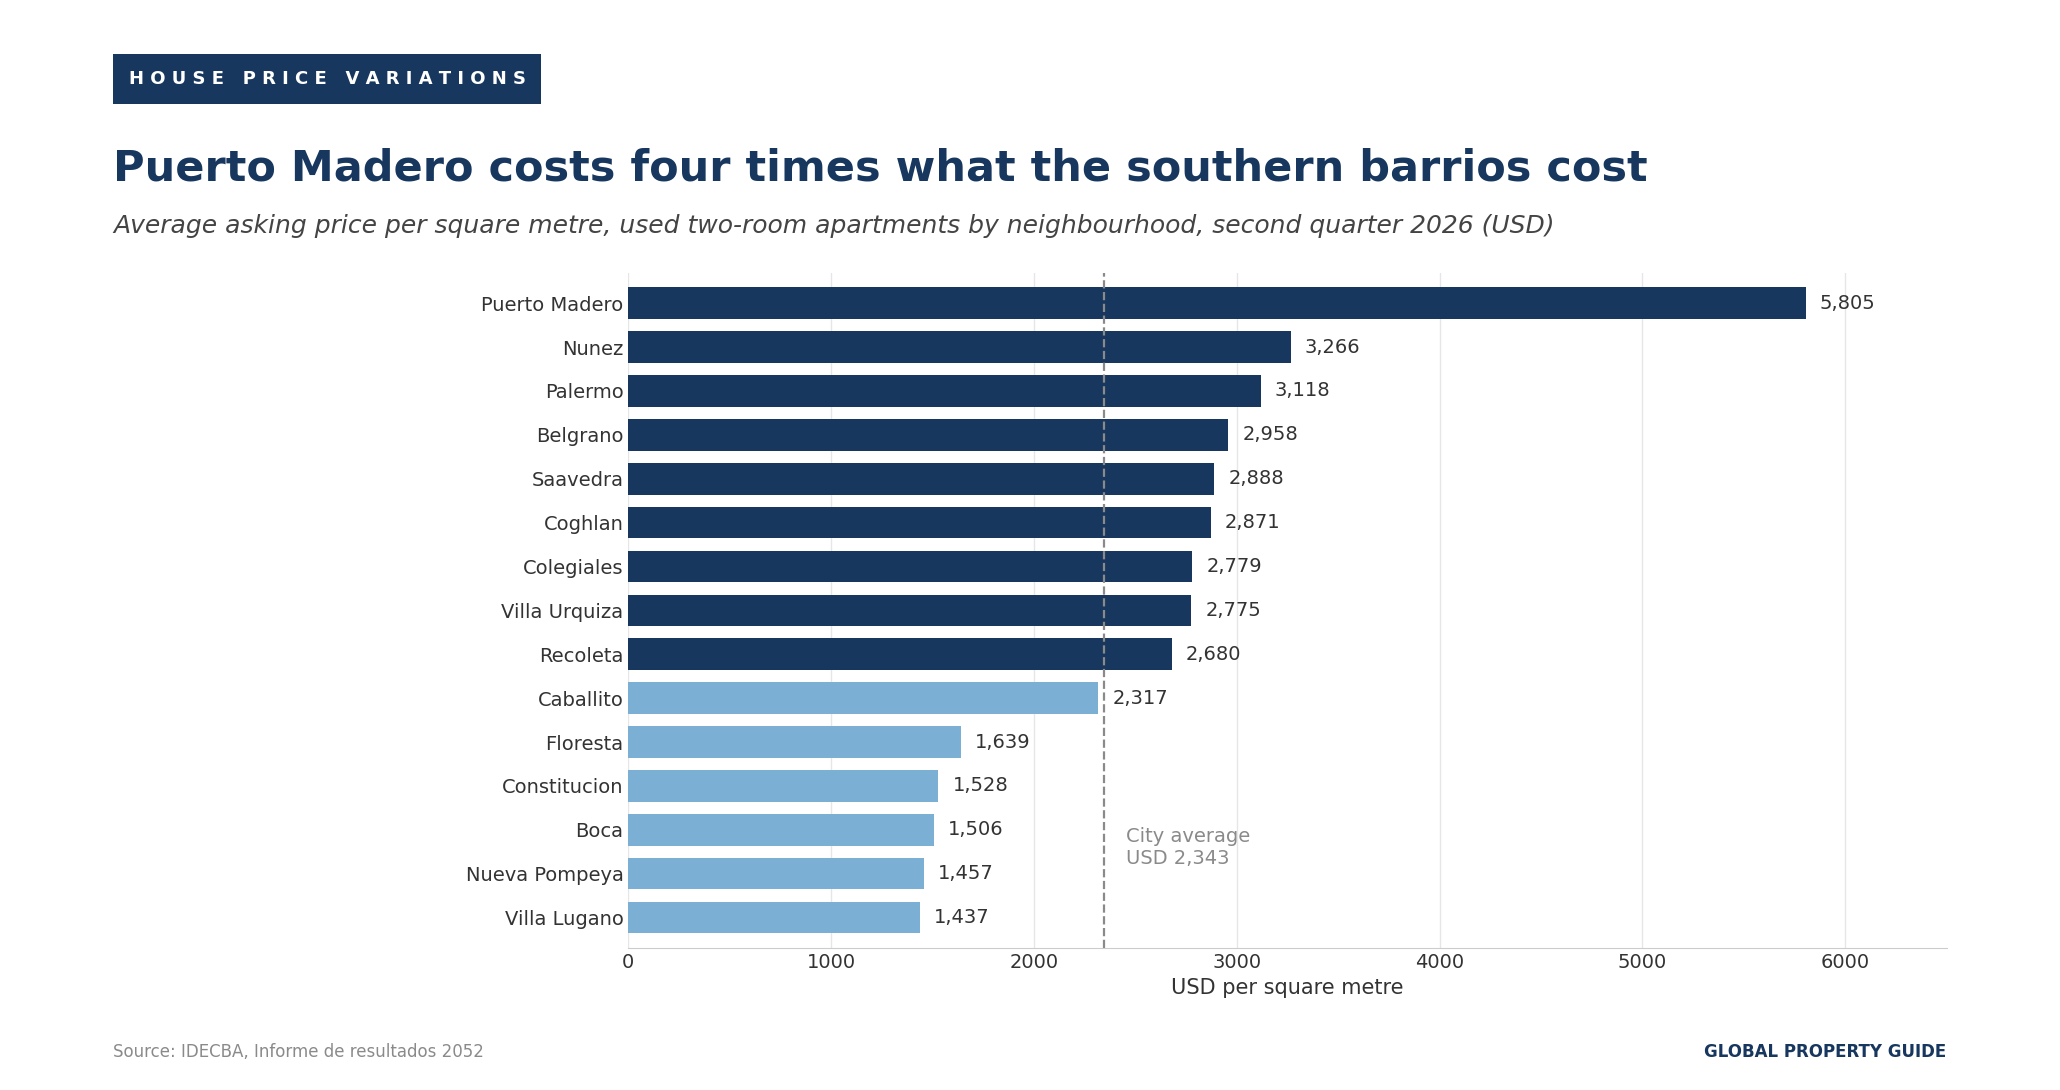
The pattern of gains has shifted. The strongest increases in Q2 2026 came not from the premium corridor but from mid-priced barrios in the northwest: Villa Pueyrredon at 11.0%, Nunez at 10.1%, Villa Santa Rita at 7.1%, Parque Chas at 6.5% and Flores at 6.3%. The sharpest falls were in Floresta at minus 7.2%, followed by Constitución and San Nicolás, both at minus 3.8%.
| AVERAGE ASKING PRICE, USED TWO-ROOM APARTMENTS, BUENOS AIRES (USD PER SQM) | ||
| Neighbourhood | Q2, 2026 | Change y-o-y (%) |
| Puerto Madero | 5,805 | -3.4 |
| Núñez | 3,266 | 10.1 |
| Palermo | 3,118 | 0.9 |
| Belgrano | 2,958 | 2.9 |
| Saavedra | 2,888 | 6.3 |
| Coghlan | 2,871 | 0.1 |
| Colegiales | 2,779 | 5.7 |
| Villa Urquiza | 2,775 | 1.1 |
| Recoleta | 2,680 | -1.9 |
| Villa Pueyrredón | 2,594 | 11.0 |
| Caballito | 2,317 | 0.9 |
| Floresta | 1,639 | -7.2 |
| Villa Lugano | 1,437 | 2.3 |
| City average | 2,343 | 1.4 |
| Note: Provisional data. Prices are published in US dollars and require no conversion. Reference rate: USD 1 = ARS 1,507.37. | ||
| Data source: IDECBA, on the basis of Argenprop listings. | ||
By comuna, Comuna 14 (Palermo) recorded the highest price per square metre in almost every segment, with the exception of used one-room apartments, where Comuna 13 (Nunez, Belgrano and Colegiales) led. The lowest valuations were spread across the southern comunas 4, 8 and 9, which take in Barracas, La Boca, Nueva Pompeya, Parque Patricios, Villa Soldati, Villa Riachuelo, Villa Lugano, Liniers, Mataderos and Parque Avellaneda.
Property Demand Trends
Sales are holding, but the credit that fuelled them is gone
2025 was an exceptional year. The capital recorded 69,461 purchase deeds over the twelve months, up 26.8% from 54,770 in 2024, according to the Colegio de Escribanos de la Ciudad de Buenos Aires. That was the best year since 2007 and one of the five strongest in three decades. The all-time record remains 1998, at about 76,000 deeds.
2026 has not repeated it, but neither has it collapsed. The capital recorded 12,580 deeds in Q1, down 0.8% year-on-year and the first decline after fifteen consecutive quarters of growth, followed by 16,897 in Q2, up 0.3%. Across the first half, the capital registered 29,477 conveyances, down just 0.2% on a year earlier.
The province of Buenos Aires fared worse, with 55,035 deeds in the first half, down 7.8% year-on-year, according to the Monitor de Credito Hipotecario published by Fundacion Tejido Urbano.
The striking divergence is between transactions and financing. Mortgage-backed deeds in the capital fell 37.2% in the first half, to 4,152 from 6,610. In the province, they fell 32.6%, to 6,913 from 10,261. Credit financed roughly one purchase in nine in the capital in Q2 2026, against approximately one in five a year earlier.
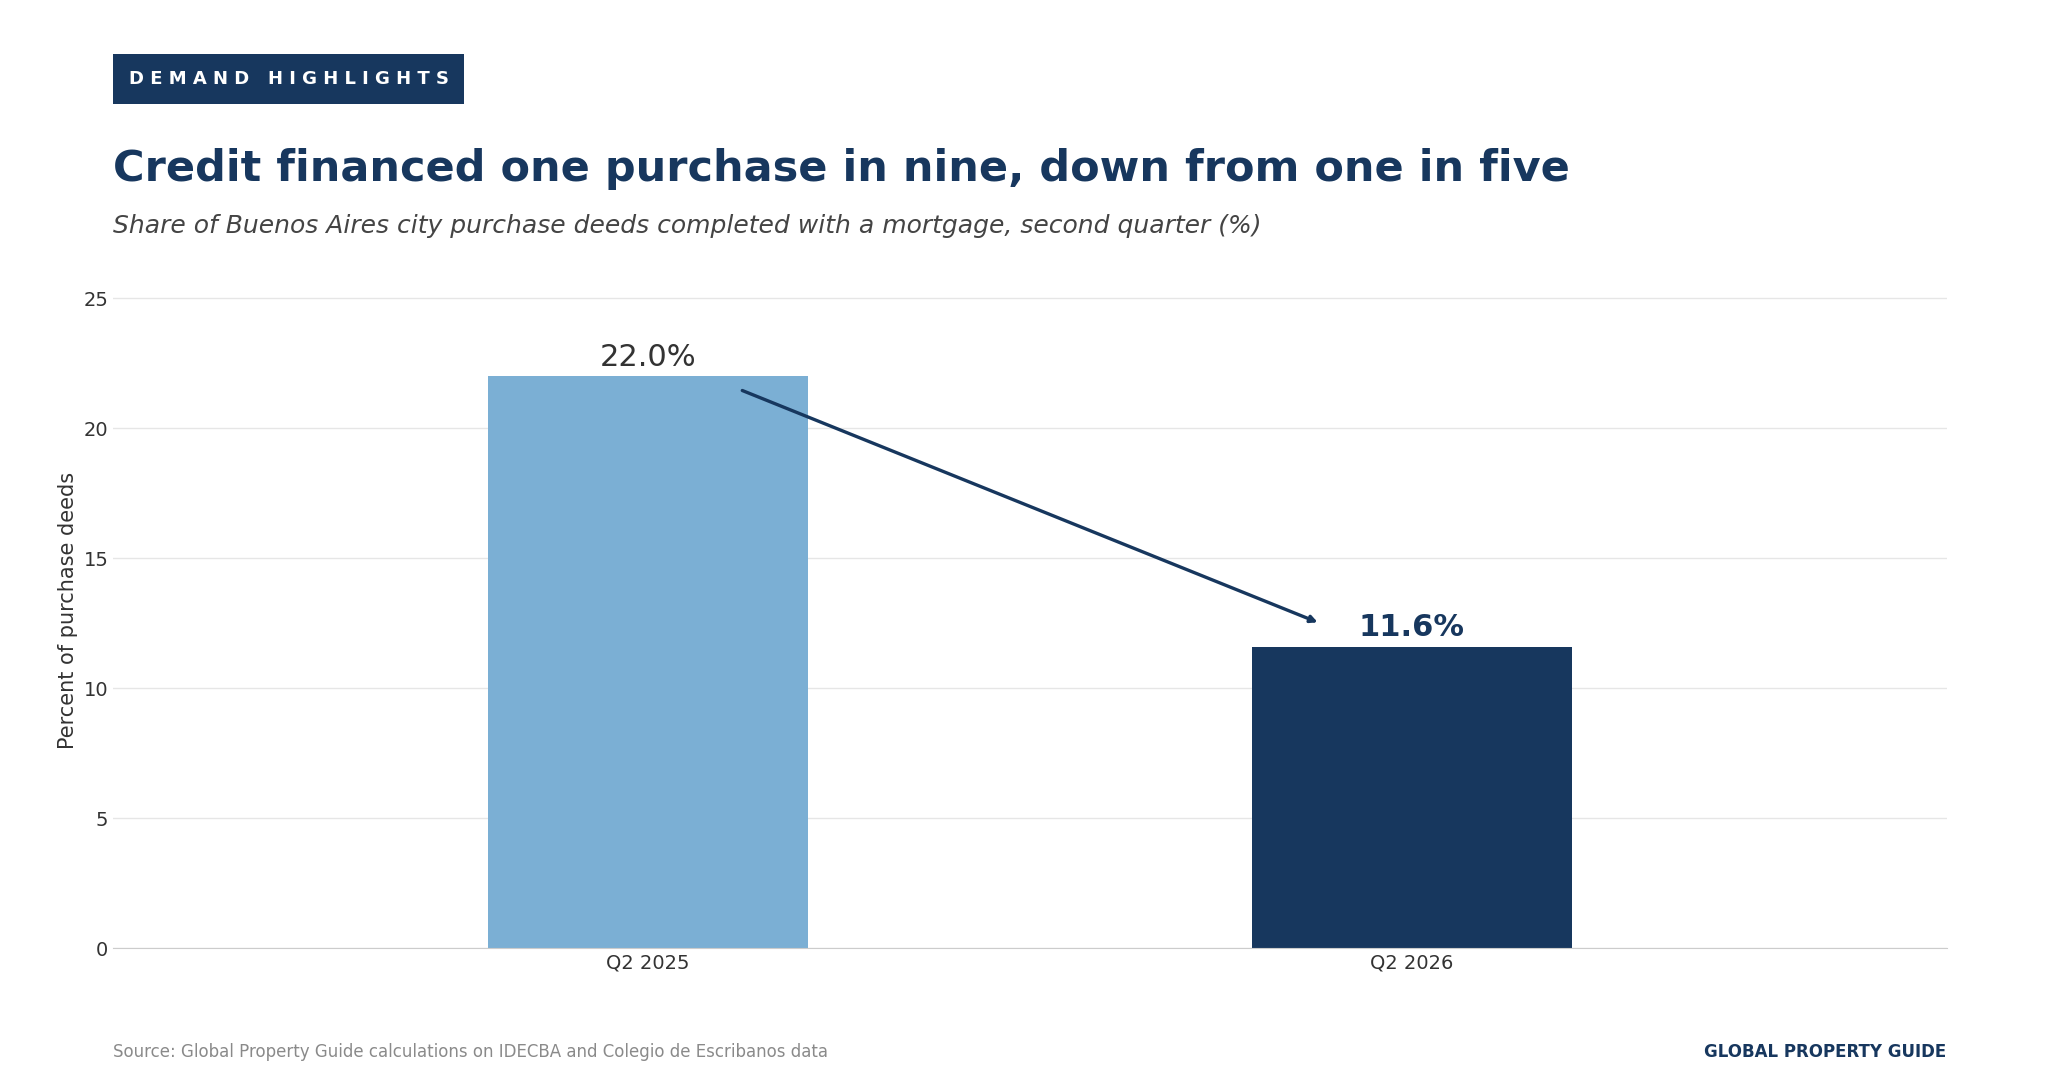
Tejido Urbano draws the obvious conclusion, noting that the weaker mortgage market reflects reduced use of bank financing rather than simply fewer sales. Cash and savings are doing the work that credit did in 2025, which points to a market increasingly dominated by higher-income households. The foundation itself observes that under more restrictive conditions, households with higher income and savings capacity may be gaining weight in the market.
Property Supply Trends
Listings at a record high, construction erratic
The stock of apartments advertised for sale in the capital reached its highest level since the series began in 2015, surpassing the previous record set in Q3 2025. Listings rose in both the used and new-build segments against both the previous quarter and the previous year.
One-room units drove the increase in both segments, gaining share at the expense of every other size category. Three-room new-builds were the exception, falling in absolute terms, which helps explain why that segment recorded the strongest price growth of the quarter at 7.2%.
Newly built units accounted for 25.1% of all listings in Q2 2026. Before the pandemic and the macroeconomic conditions that hit the construction sector, the new-build share averaged 35.0%.
Construction activity itself is positive year-on-year but unstable month-to-month. The synthetic indicator of construction activity (ISAC) rose 4.0% year-on-year in June 2026, though it fell 4.1% against May. Over the first half of 2026, the index was up 2.8% compared with the same period of 2025. The full year 2025 saw growth of 6.3%.
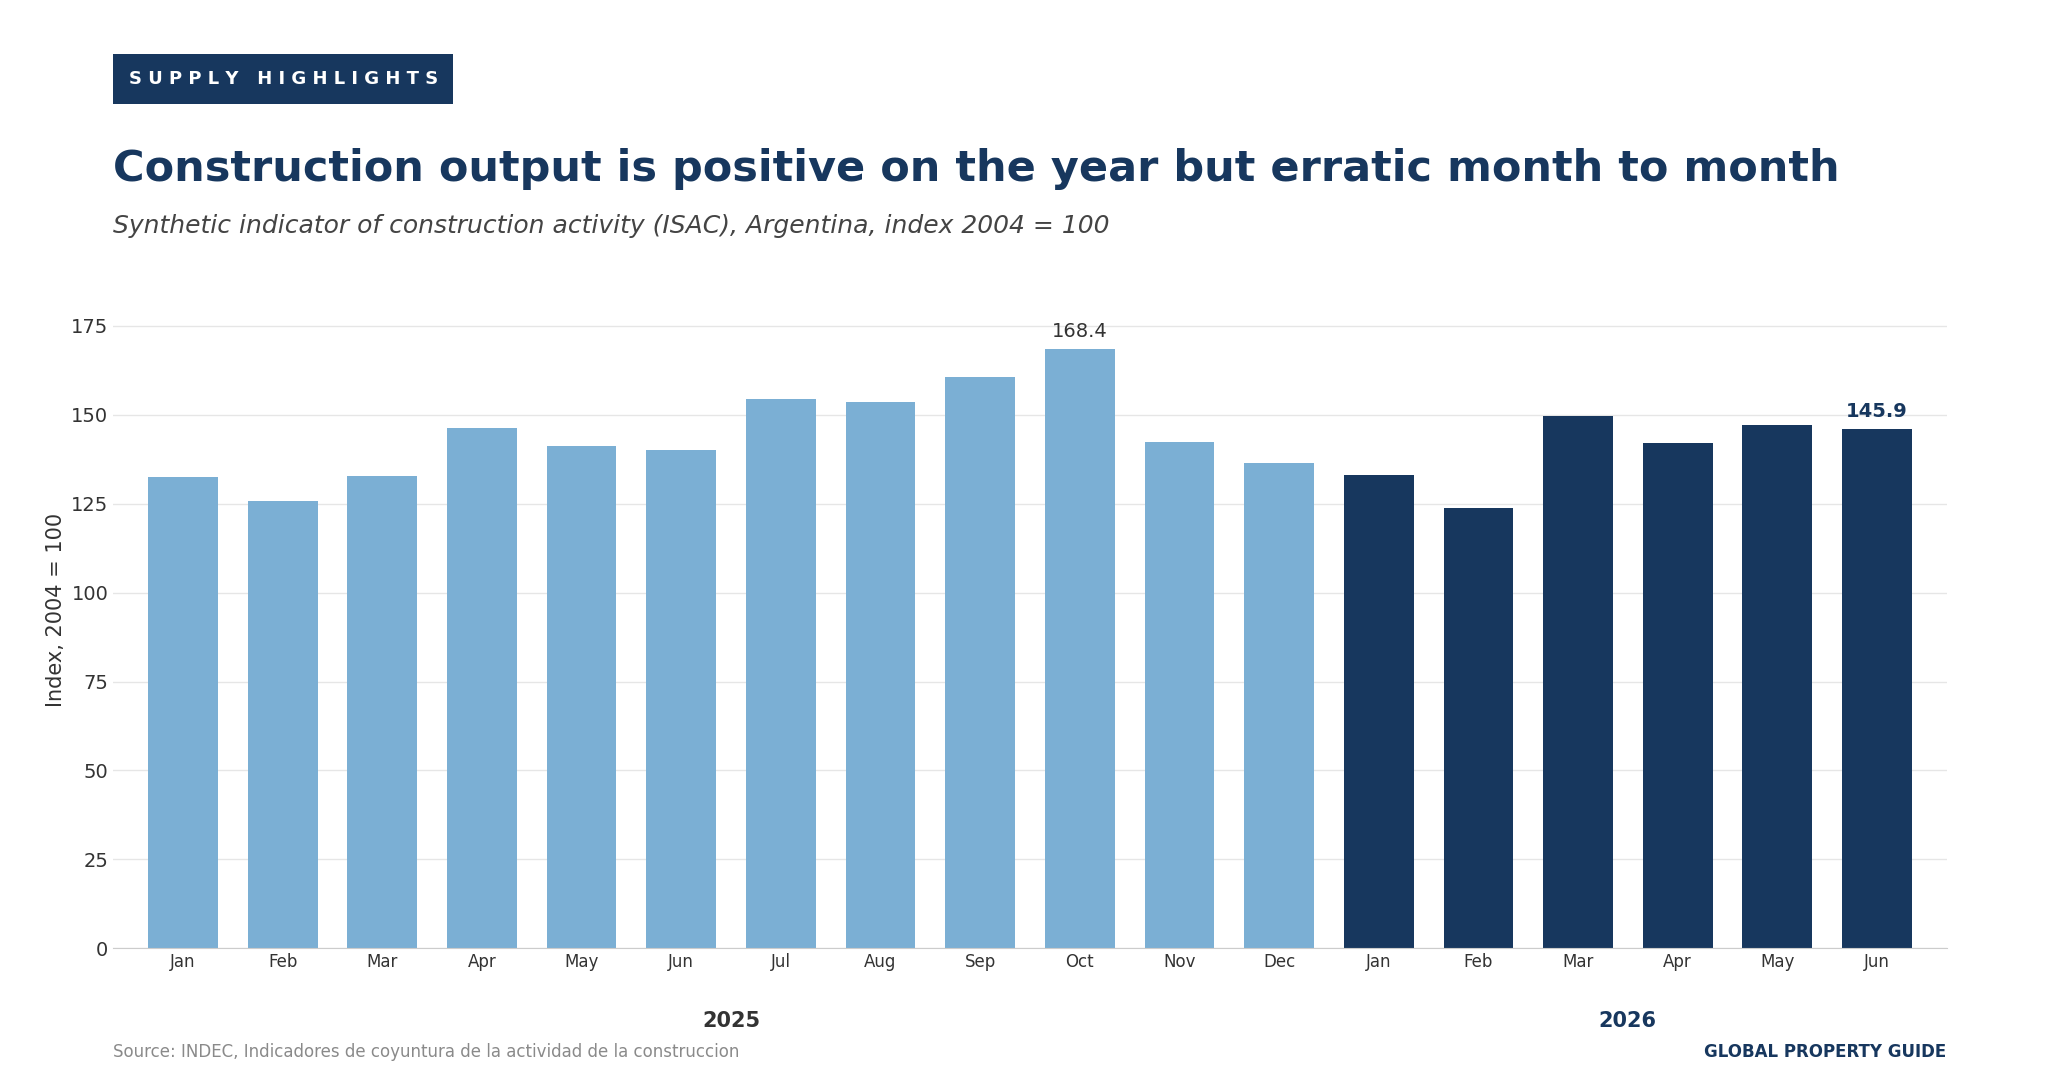
Private measures are less encouraging. The Indice Construya, which tracks volumes of construction materials sold to the private sector by its member companies, fell 6.5% year-on-year in July 2026 and 0.8% month-on-month in seasonally adjusted terms. Over the first seven months of the year, shipments were 0.6% different from the same period of 2025. The divergence between the official index and the private materials measure is worth watching.
Rental Market: Rents and Rental Yields
Rental yields have given back most of last year's gain
Gross rental yields on apartments in Argentina are moderate, and by the standards of Latin America, where yields tend to be high, unremarkable. The typical gross rental yield, the rental return earned on the purchase price before taxation, vacancy costs and other costs, is not something that will attract foreigners to invest, even if they could obtain a mortgage in Argentina, which they cannot.
Argentina's rent price index:
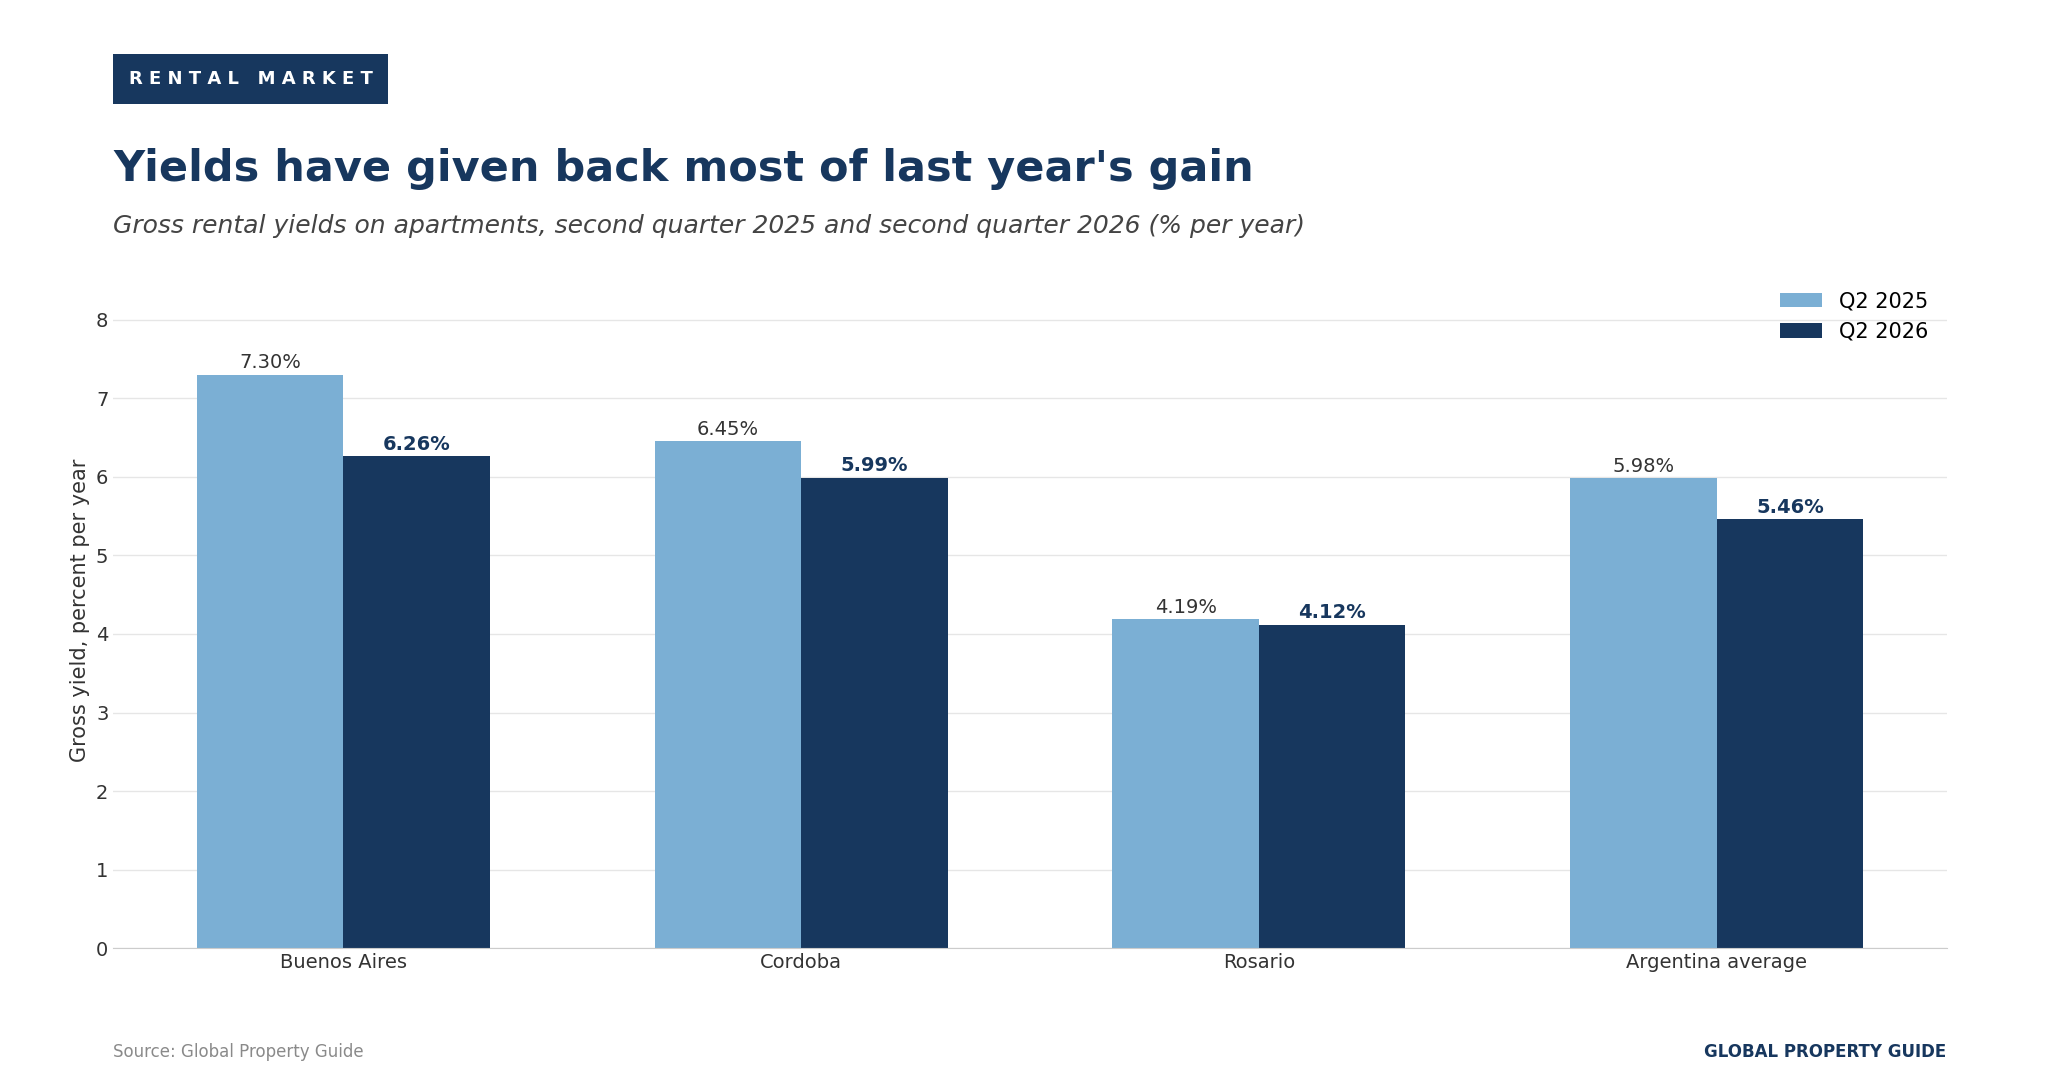
Nationwide, the average gross rental yield stood at 5.46% in Q2 2026, down from 5.98% in the same period last year, according to research conducted by the Global Property Guide. Yields did recover from the 5.09% recorded in Q4 2025, but the year-on-year direction has reversed. In the previous edition of this report, yields were rising.
In major cities:
- In Buenos Aires, gross rental yields for apartments are relatively higher, with a city average of 6.26%, down from 7.30% a year earlier.
- In Rosario, gross rental yields are much lower, with a city average of 4.12%, little changed from 4.19%.
- In Cordoba, residential properties yield a city average of 5.99%, down from 6.45%.
| GROSS RENTAL YIELDS ON APARTMENTS (% PER YEAR) | ||
| City | Q2, 2025 | Q2, 2026 |
| Buenos Aires | 7.30 | 6.26 |
| Córdoba | 6.45 | 5.99 |
| Rosario | 4.19 | 4.12 |
| Argentina average | 5.98 | 5.46 |
| Note: Yields are gross, before taxes, repair costs, ground rents, and agent fees. Reference rate: USD 1 = ARS 1,507.37. | ||
| Data source: Global Property Guide. | ||
Given that a typical landlord's expenses run to around 2% per annum in maintenance, repairs and vacancies, many landlords will effectively earn significantly less than the headline figure suggests. Round-trip transaction costs are also high in Argentina.
In Buenos Aires, a two-room apartment is currently offered for a monthly rent of US$1,200 in Tigre; US$970 in Vicente Lopez; US$900 in San Isidro; US$660 in Buenos Aires Costa Atlantica; US$590 in Moron; US$520 in Lomas de Zamora; and US$480 in both La Matanza and Lanus. In Rosario and Cordoba, a similar apartment rents for US$480 and US$570 per month, respectively.
Rents have stopped outpacing inflation
The bigger change in the rental market is that rents have converged on inflation and stayed there.
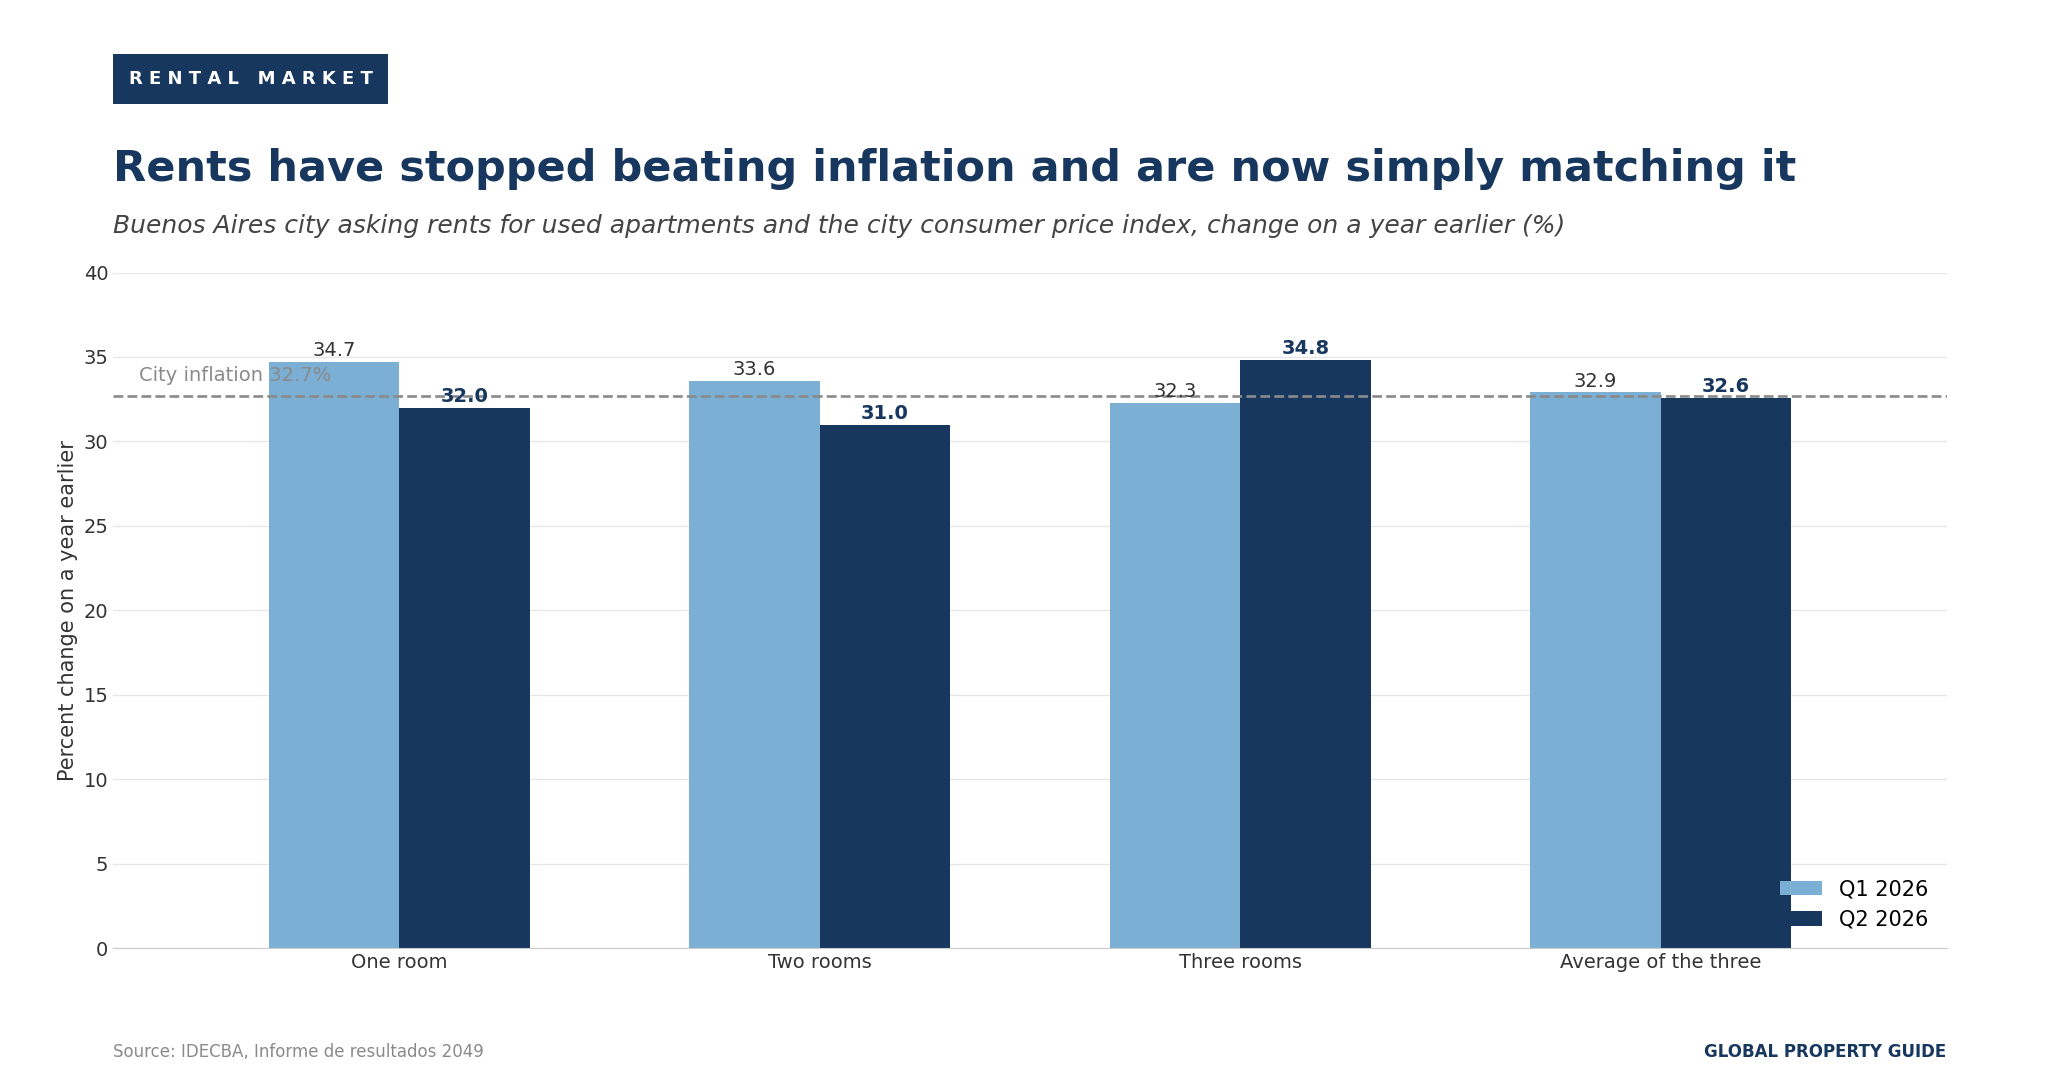
In Q2 2026, the average asking rent for a used two-room apartment in the capital reached ARS764,485 per month, up 31.0% year-on-year, according to IDECBA. One-room units averaged ARS565,658, up 32.0%, and three-room units ARS1,174,304, up 34.8%.
Averaged across the three sizes, asking rents rose 32.6% against city inflation of 32.7%. IDECBA notes that this convergence has now held for five consecutive quarters, and that the evolution of used rental asking prices closely tracks the city's general price level. In real terms, rents were flat.
This is a genuine reversal. For years, Argentine rents rose by double-digit real margins as tenants competed for a shrinking pool of units. The previous edition of this report described rent growth outpacing house price growth. That is no longer the case in real terms.
Supply explains much of it. The stock of rental listings hit a new series record in Q2 2026, 9.0% above the previous peak of July to September 2025, with peso listings running about 30% above the first quarter.
One structural shift deserves attention. Dollar-denominated rental listings now account for 25.4% of the total stock, and their share rises with unit size: about 30% for three-room apartments and 44.0% for four- and five-room units. These listings are heavily concentrated in the north: comunas 14 (Palermo), 13 (Belgrano, Núñez and Colegiales) and 2 (Recoleta) account for 61.0% of them, rising to 82.0% once Comuna 1 is included. IDECBA suggests the declining weight of the northern corridor in the peso rental market reflects progressive replacement by units offered in foreign currency.
Mortgage Market and Interest Rates
The 2025 credit boom has broken
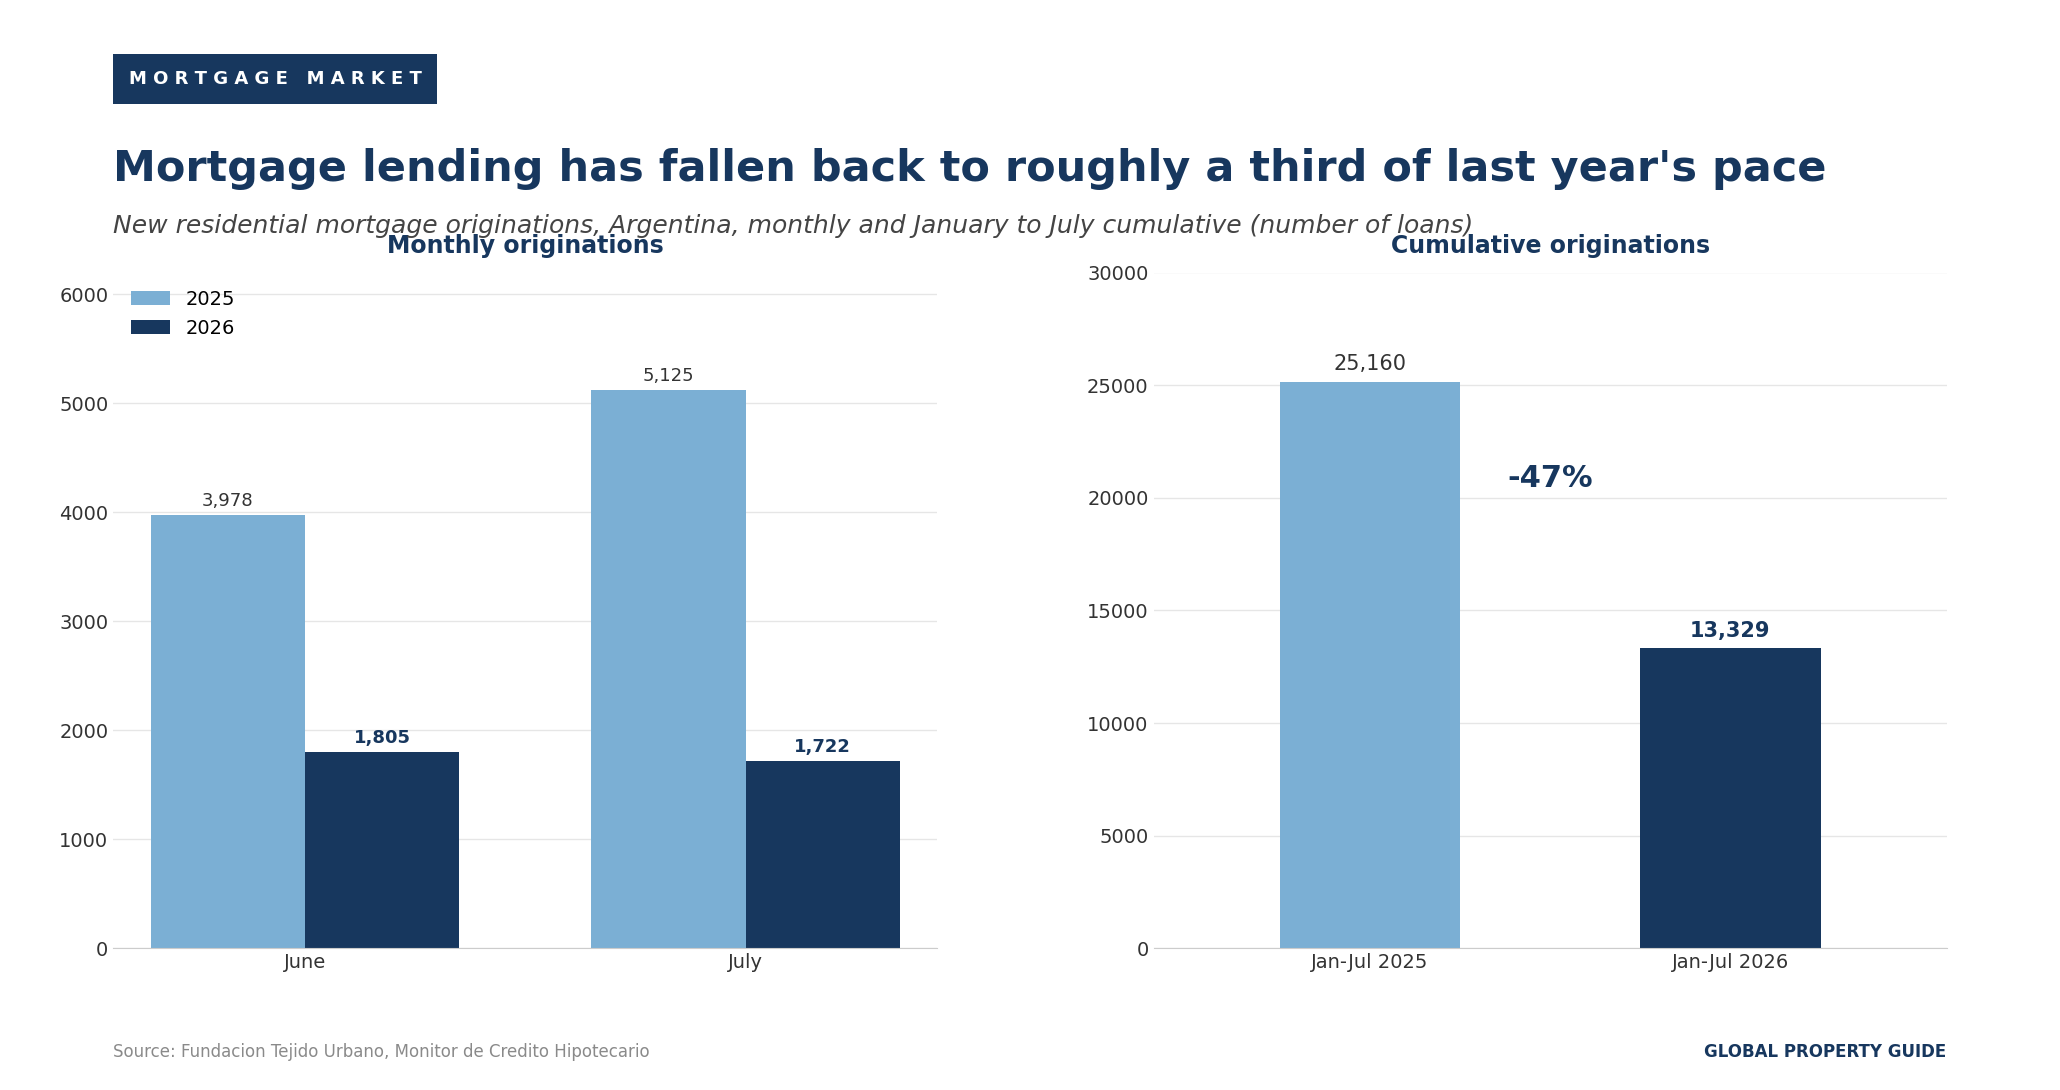
Nationally, new mortgage originations totalled 13,329 between January and July 2026, down 47% from 25,160 in the same period of 2025, according to Fundacion Tejido Urbano. Monthly originations ran at 1,805 in June and an estimated 1,722 in July, against 3,978 and 5,125 in the same months of 2025.
Argentina's mortgage loan interest rates:
Tejido Urbano reads June and July as a stabilisation at between 1,700 and 1,800 operations a month following the sharp retreat of April and May, rather than as a recovery of the credit cycle.
The tightening came from the lending side. Loan-to-value ratios were cut from 80% and 90% to between 70% and 75%, and maximum terms at several banks were shortened from 30 years to 20. Average terms on new loans fell from 24.7 years in April 2026 to 23 years in June. Banks also raised approval requirements, which reduced volumes and lengthened administrative timelines.
Volume tells a different story from count. Roughly US$905 million was disbursed in mortgage lending over the first half of 2026, a figure similar to the whole of 2024. Fewer loans are being written, but for larger amounts. In the province of Buenos Aires, the average mortgage-backed deed in June 2026 was approximately US$97,844.
Housing loan interest rates
Argentina's mortgage market is now overwhelmingly denominated in Unidades de Valor Adquisitivo (UVA), the inflation-linked unit introduced in 2016. The relevant interest rate is therefore the real rate charged above indexation, not a nominal peso rate.
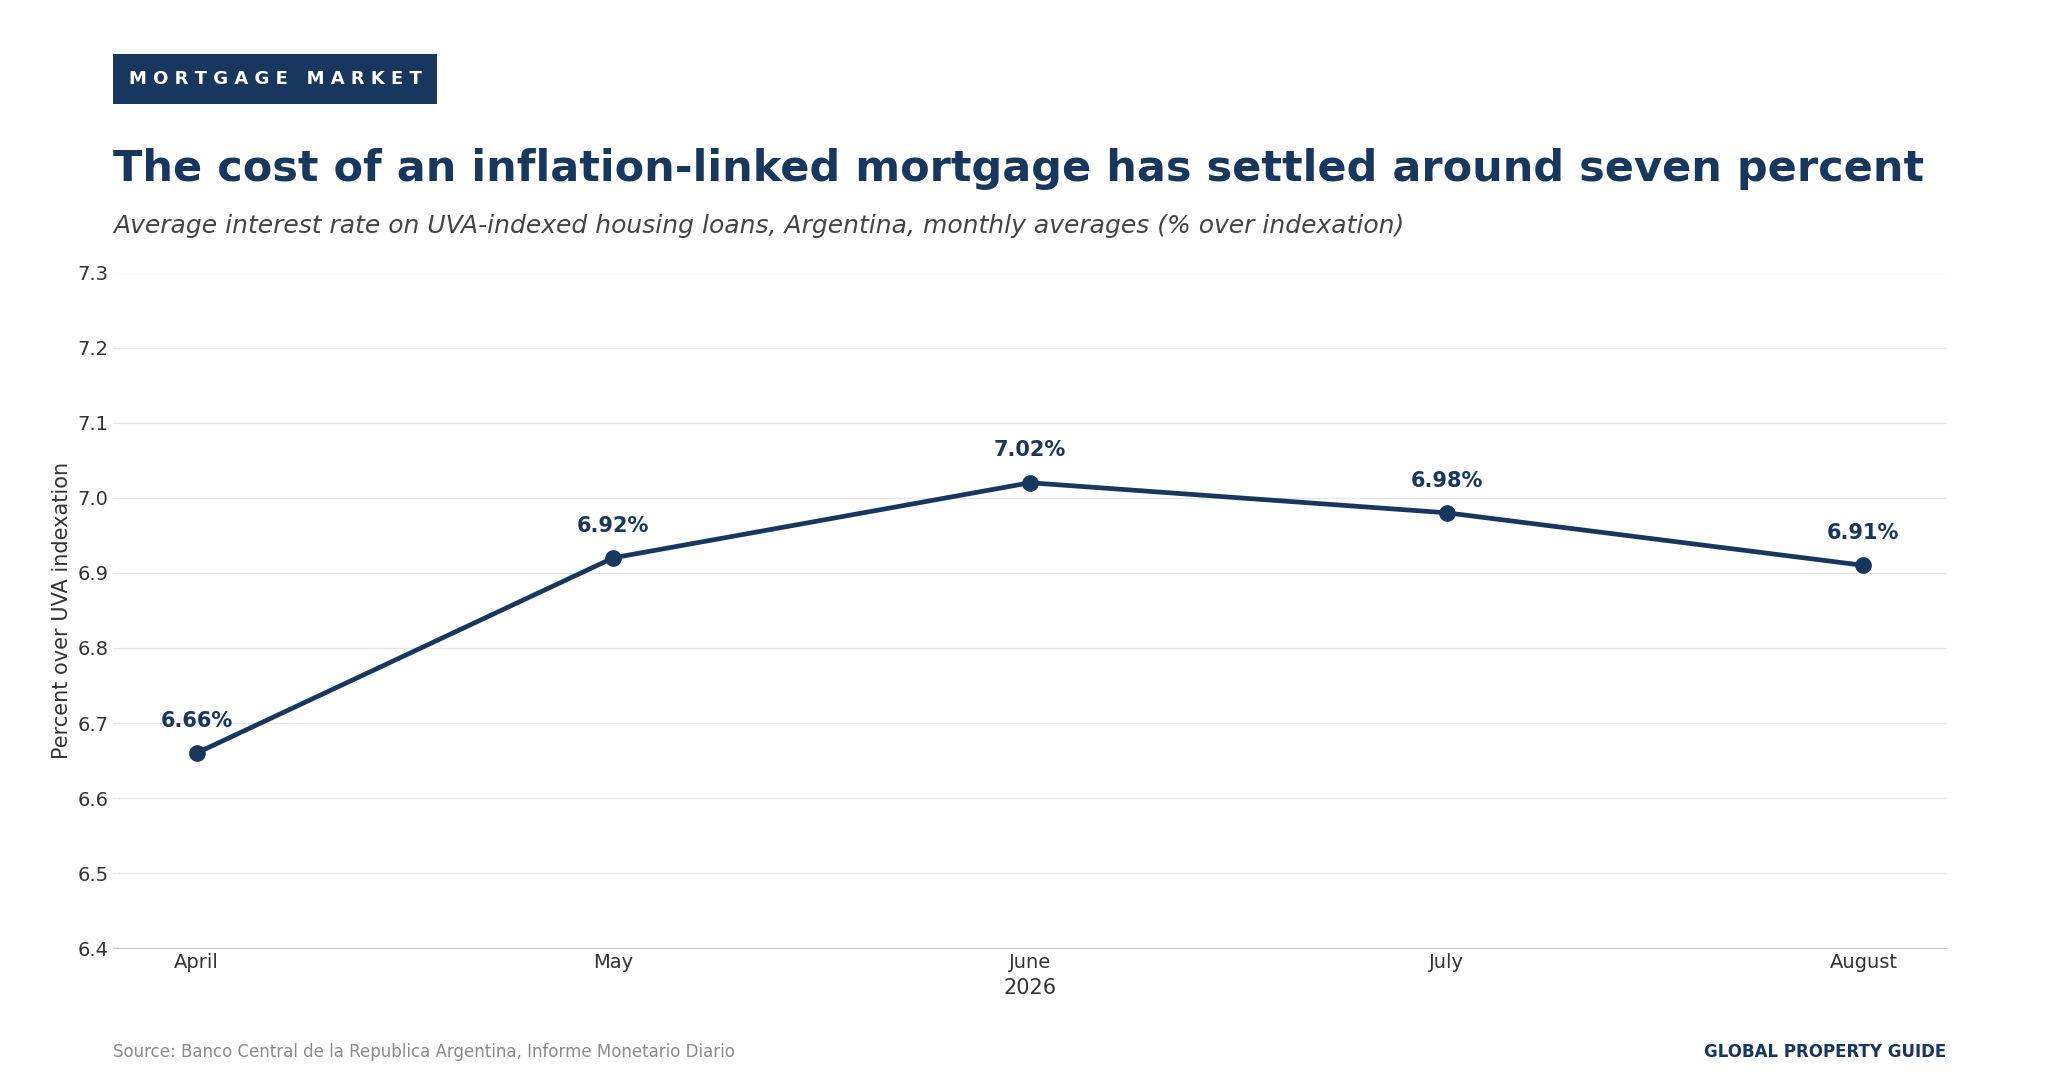
On that measure, the average rate on UVA housing loans was 6.91% in August 2026, easing from 7.02% in June and 6.98% in July, according to the BCRA. Tejido Urbano records the average rate on newly granted loans rising through the second quarter, from 6.66% in April to 6.92% in May and 7.02% in June.
Separately, the average rate on peso mortgage loans written at a fixed nominal rate stood at 32.12% in early September 2026, against 32.00% twelve months earlier. This is a small and shrinking part of the market.
Readers comparing these figures with the previous edition of this report should note that they are not drawn from the same series. The August 2025 edition quoted an average mortgage rate of 43.46% with a breakdown by maturity. That figure cannot be reconciled with either BCRA series available today, and the two should not be chained together.
The stock of mortgage debt
Outstanding peso-denominated mortgage loans reached ARS8.68 trillion (US$5.76 billion) in early September 2026, up 81.0% year-on-year, based on figures released by the BCRA. Against consumer price inflation of 33.8%, that is real growth of about 35%.
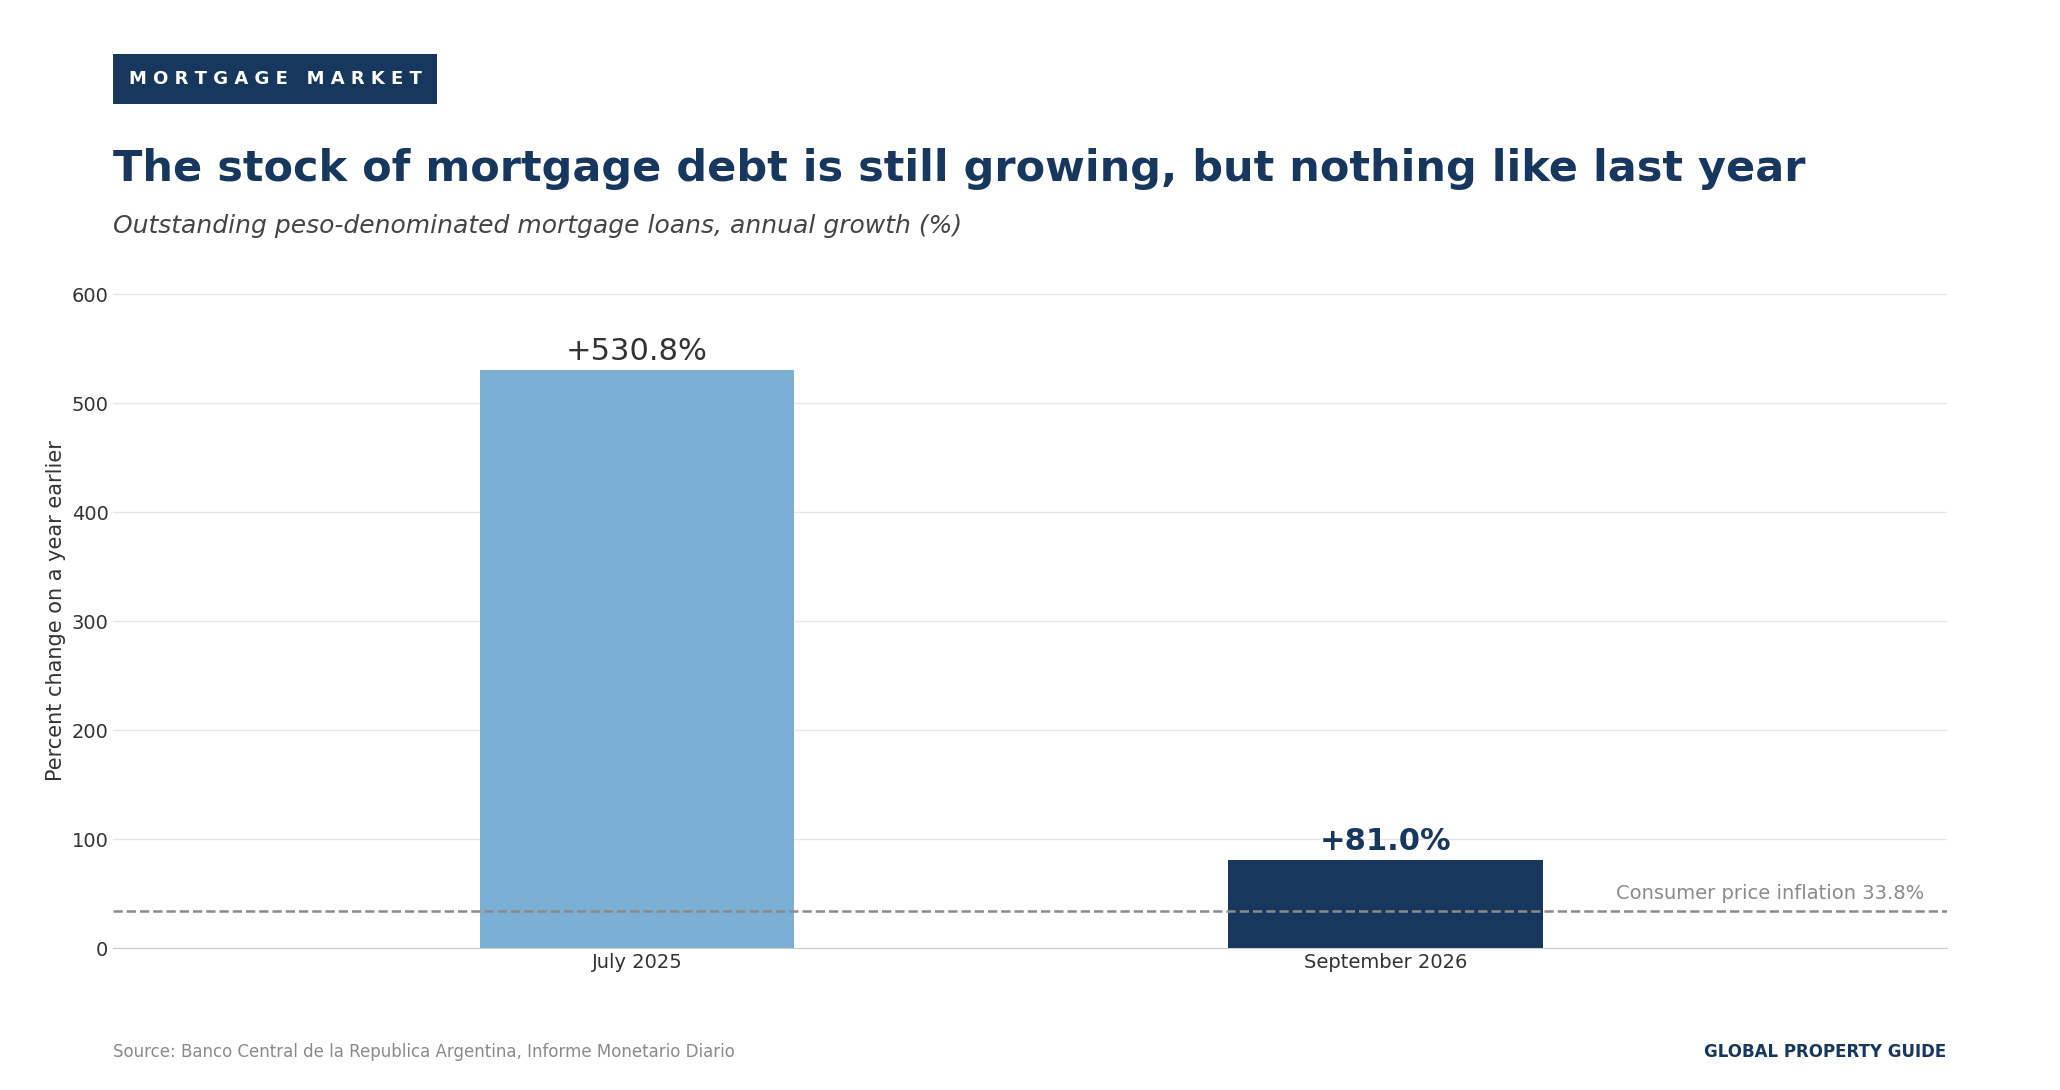
The stock is still expanding faster than total peso lending to the private sector, which grew 31.7%. But the pace has collapsed relative to last year, when the same measure was growing at 530.8%. A stock that is still rising while new originations fall by half is the signature of a market working through loans approved in a previous cycle.
Despite the surge in nominal terms, the Argentine mortgage market remains tiny by any international comparison. Homes are priced in US dollars while buyers can only borrow in pesos, a mismatch that has never been resolved.
The policy response
On August 26, 2026, the government announced that it would channel ARS2 trillion from the Fondo de Garantía de Sustentabilidad, the ANSES pension guarantee fund, into funding banks to expand first-home mortgage lending. Auctions will be held in tranches of ARS200,000 million, with no institution permitted to take more than 20% of the resources offered, and loans capped at 150,000 UVA.
If fully deployed, the programme could add more than half the volume the market projects for the whole of 2026. Critics have noted that it is a one-off liquidity operation rather than a structural change to how Argentine mortgages are funded. The government is separately working on expanded guarantees, mortgage securitisation and a federal registry of guarantees, though any effect from those measures would be felt over the medium term.
Note also that a correction is due to the previous edition of this report. It described the central bank as having held its benchmark rate steady since January 2025, and referred to that rate as the Leliq. Neither is accurate. LELIQ instruments were eliminated in July 2024. More fundamentally, under the monetary aggregates regime adopted in December 2023, the BCRA has formally retired the concept of a monetary policy rate, leaving interest rates to be determined endogenously by the market. There has been no benchmark rate to hold since the framework changed.
Economic and Social Factors
Growth has slowed and disinflation has stalled
Argentina's economy grew by 2.3% year-on-year in Q1 2026, and by 0.7% quarter-on-quarter in seasonally adjusted terms, according to INDEC. Growth was led by agriculture, fishing and mining, all export-facing, while manufacturing fell 1.7% and retail commerce declined 0.3%.
Momentum has since weakened. Private consultancies surveyed in August estimated a seasonally adjusted contraction of between 0.5% and 1.0% in Q2 2026, against a market consensus in June that had expected growth of 0.6%. INDEC publishes the official Q2 figure on September 17, 2026. Fitch Ratings forecast growth of 3.2% for 2026 as a whole when it upgraded Argentina in May.
Inflation is the more troubling indicator. The annual rate reached 33.8% in July 2026, according to INDEC, having troughed at 31.3% in October 2025. Monthly inflation was 2.1% in July, down from a peak of 3.4% in March, and the cumulative increase for 2026 through July was 19.3%. Disinflation has not resumed; it has flattened out at a level that would be a crisis almost anywhere else.
Regulated prices are the main pressure, rising 44.3% year-on-year against core inflation of 32.2%. Housing, water, electricity and gas rose 48.9%.
The labour market has softened. The unemployment rate was 7.8% in Q1 2026, up from 7.5% in Q4 2025, though marginally below the 7.9% of Q1 2025. INDEC noted that neither movement was statistically significant. More concerning were the underlying measures: underemployment rose 1.1 percentage points to 11.1%, a statistically significant increase, and informality rose 2.2 percentage points to 44.2%.
Argentina's credit rating recovery
The clearest evidence of the stabilisation programme's credibility came from the rating agencies, which upgraded Argentina three times in under three months.
Fitch Ratings raised Argentina's long-term issuer default ratings to B- from CCC+ on May 5, 2026, with a stable outlook, citing improved fiscal and external balances and better prospects for reserve accumulation. It was the first Fitch upgrade in eight years, restoring a level Argentina had not held since the 2018 currency crisis. The agency cautioned that international liquidity remains weak, inflation high, and that foreign-currency bond maturities approach US$9.8 billion in 2027.
S&P Global Ratings followed in June 2026. Moody's upgraded Argentina to B3 from Caa1 on July 21, 2026, with a positive outlook, pointing to a durable improvement in credit fundamentals, stronger exports, rising foreign direct investment in energy and mining, and better access to external financing.
All three agencies now rate Argentina above the highly distressed category, the first time they have been aligned in a decade. Argentina's sovereign risk premium narrowed to around 400 to 420 basis points in July 2026, its lowest in eight years. The central bank purchased more than US$11 billion of foreign exchange through mid-2026 without exchange rate stress.
Both Moody's and Fitch flagged the same risk: the 2027 presidential election. Moody's observed that the range of policy outcomes has narrowed compared with previous cycles, which increases the likelihood of policy continuity.
What to watch
The Argentine housing market enters the second half of 2026 with a stable currency, a functioning foreign exchange market, restored international credit standing and record listing volumes, but without the mortgage credit that drove the 2025 recovery. Whether the ANSES funding programme restores lending volumes, and whether the new-build and resale segments reconverge, will determine whether the 2025 expansion resumes or whether 2026 marks its high-water point.
Note on currency: all peso amounts in this report are converted at USD 1 = ARS 1,507.37, the BCRA Communication A 3500 reference rate on September 4, 2026. Apartment prices and rental yields are published in US dollars by IDECBA and the Global Property Guide, respectively, and require no conversion.
Sources:
- Dinámica del mercado de venta de departamentos. Ciudad de Buenos Aires. 2do. trimestre de 2026 (Instituto de Estadística y Censos de la Ciudad Autónoma de Buenos Aires): estadisticaciudad.gob.ar
- Dinámica del mercado de venta de departamentos. Ciudad de Buenos Aires. 1er. trimestre de 2026 (Instituto de Estadística y Censos de la Ciudad Autónoma de Buenos Aires): estadisticaciudad.gob.ar
- Dinámica del mercado de alquiler de departamentos. Ciudad de Buenos Aires. 2do. trimestre de 2026 (Instituto de Estadística y Censos de la Ciudad Autónoma de Buenos Aires): estadisticaciudad.gob.ar
- Barrio por barrio: cuánto vale el metro cuadrado en la Ciudad de Buenos Aires (Infobae): infobae.com
- Escrituras en CABA: 2025 cerró con casi 70.000 operaciones (Ámbito): ambito.com
- Se enfría el crédito hipotecario: operaciones cayeron 47% interanual entre enero y julio (Primera Edición): primeraedicion.com.ar
- La reactivación del crédito hipotecario retrocedió en el primer trimestre del 2026 (El Observador): elobservador.com.uy
- Créditos hipotecarios: la nueva medida del Gobierno (La Nación): lanacion.com.ar
- Créditos hipotecarios: tras el boom de 2025, el acceso vuelve a frenarse (Perfil): perfil.com
- Informe Monetario Diario (Banco Central de la Republica Argentina): bcra.gob.ar
- Cuadros estandarizados de series estadísticas (Banco Central de la República Argentina): bcra.gob.ar
- Objetivos y planes respecto al desarrollo de las políticas monetarias, financieras, crediticias y cambiarias 2026 (Banco Central de la República Argentina): bcra.gob.ar
- Monetary Policy (Banco Central de la Republica Argentina): bcra.gob.ar
- Índice de precios al consumidor. Julio de 2026 (Instituto Nacional de Estadística y Censos): indec.gob.ar
- Construcción (Instituto Nacional de Estadística y Censos): indec.gob.ar
- Indicadores de coyuntura de la actividad de la construcción. Junio de 2026 (Instituto Nacional de Estadística y Censos): indec.gob.ar
- Mercado de trabajo. Tasas e indicadores socioeconómicos (EPH). Primer trimestre de 2026 (Instituto Nacional de Estadistica y Censos): indec.gob.ar
- Índice Construya (Grupo Construya): grupoconstruya.com.ar
- Gross rental yields in Argentina: Buenos Aires and 2 other cities (Global Property Guide): globalpropertyguide.com
- Buying guide for Argentina (Global Property Guide): globalpropertyguide.com
- Fitch upgrades Argentina's debt rating to B- (Buenos Aires Herald): buenosairesherald.com
- Fitch upgrades Argentina's credit rating for first time in eight years (bne IntelliNews): intellinews.com
- Moody's lifts Argentina debt rating in fresh boost to Milei (Buenos Aires Times): batimes.com.ar
- Economistas anticipan caída del PBI de Argentina en el segundo trimestre (Bloomberg Línea): bloomberglinea.com
- Desempleo en Argentina aumenta por segundo trimestre consecutivo (Bloomberg Línea): bloomberglinea.com
- Removal of foreign exchange controls in Argentina (Dentons): dentons.com
- Argentina: Significant Relaxation of Access to Official Exchange Market (KPMG): kpmg.com
- Investors see green shoots in barren Argentine real estate market (Reuters): reuters.com
- Central bank to launch new mortgage plan (Buenos Aires Herald): buenosairesherald.com