Singapore's Residential Property Market Analysis 2026
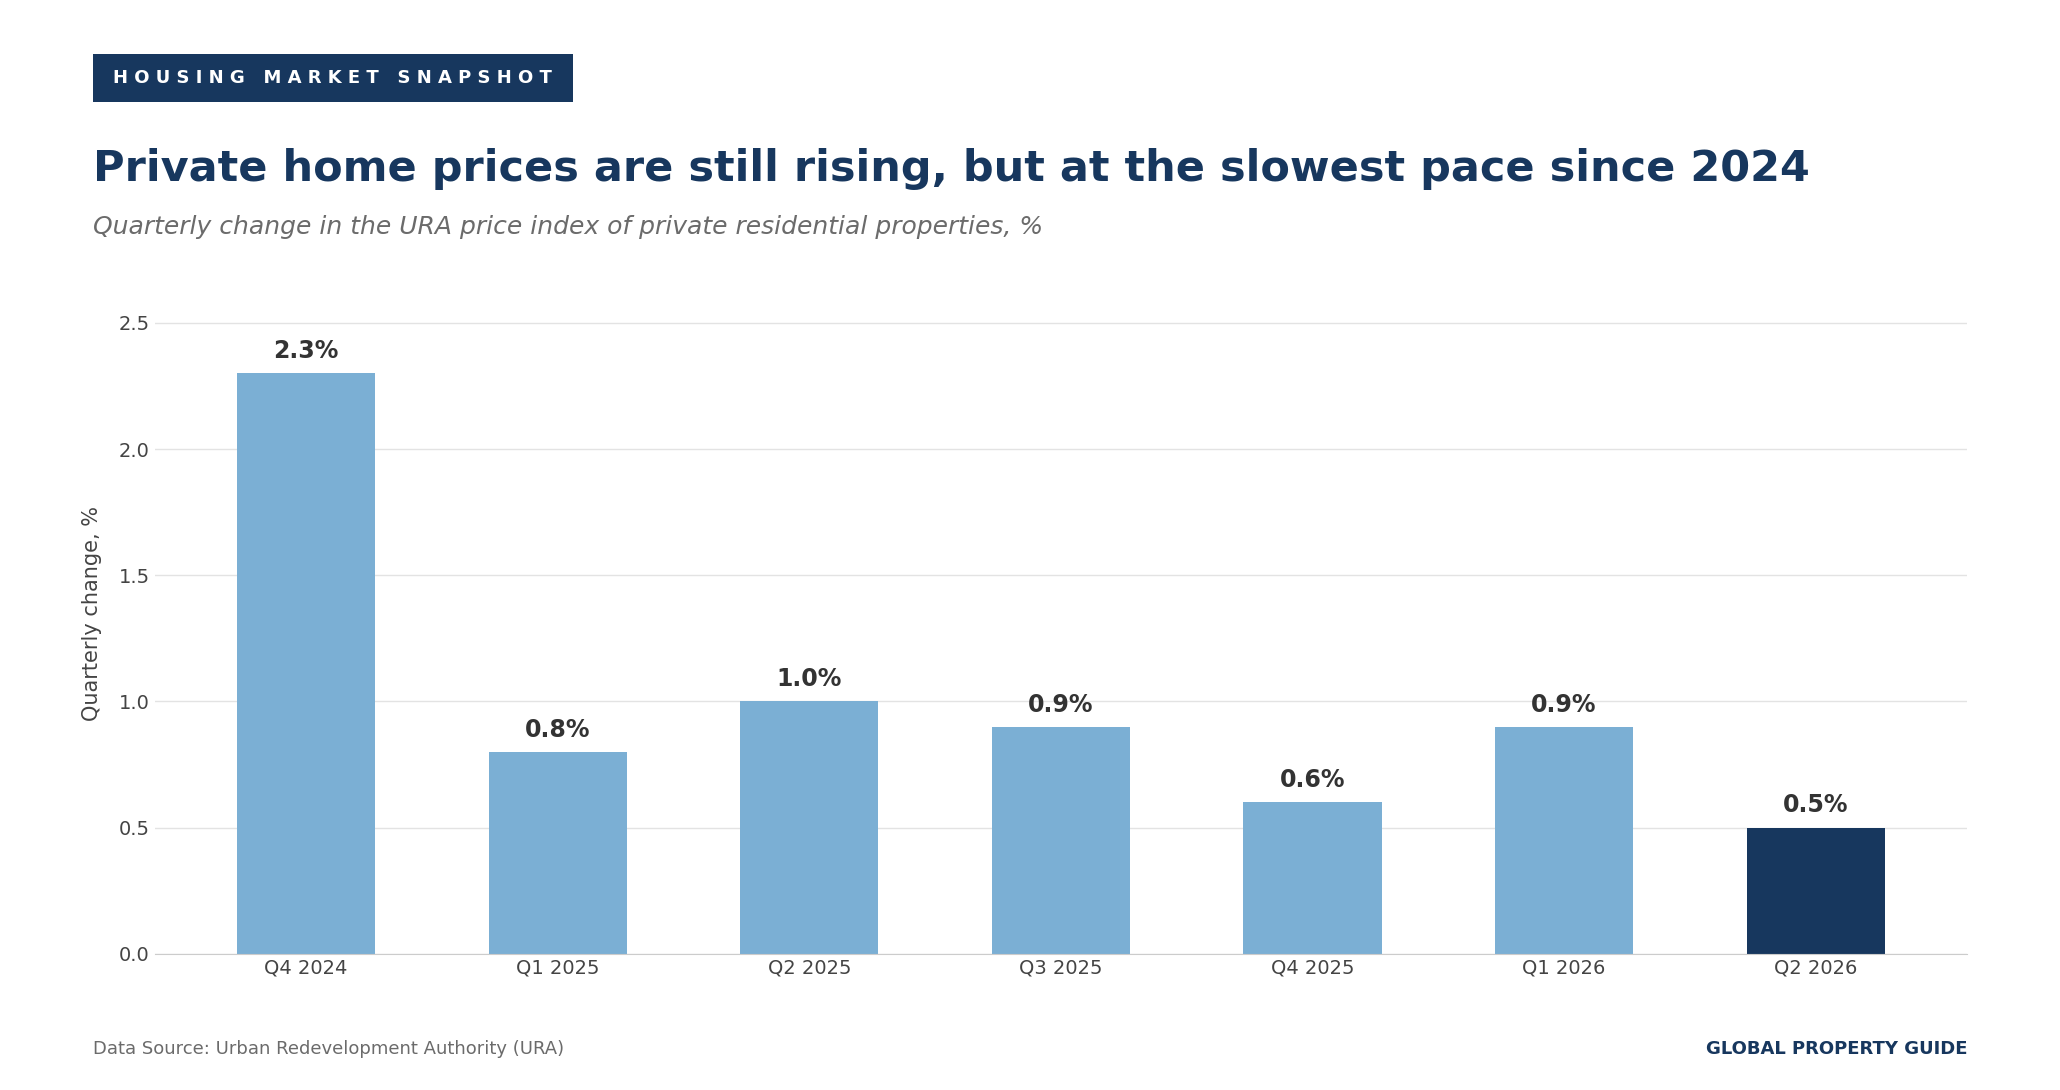
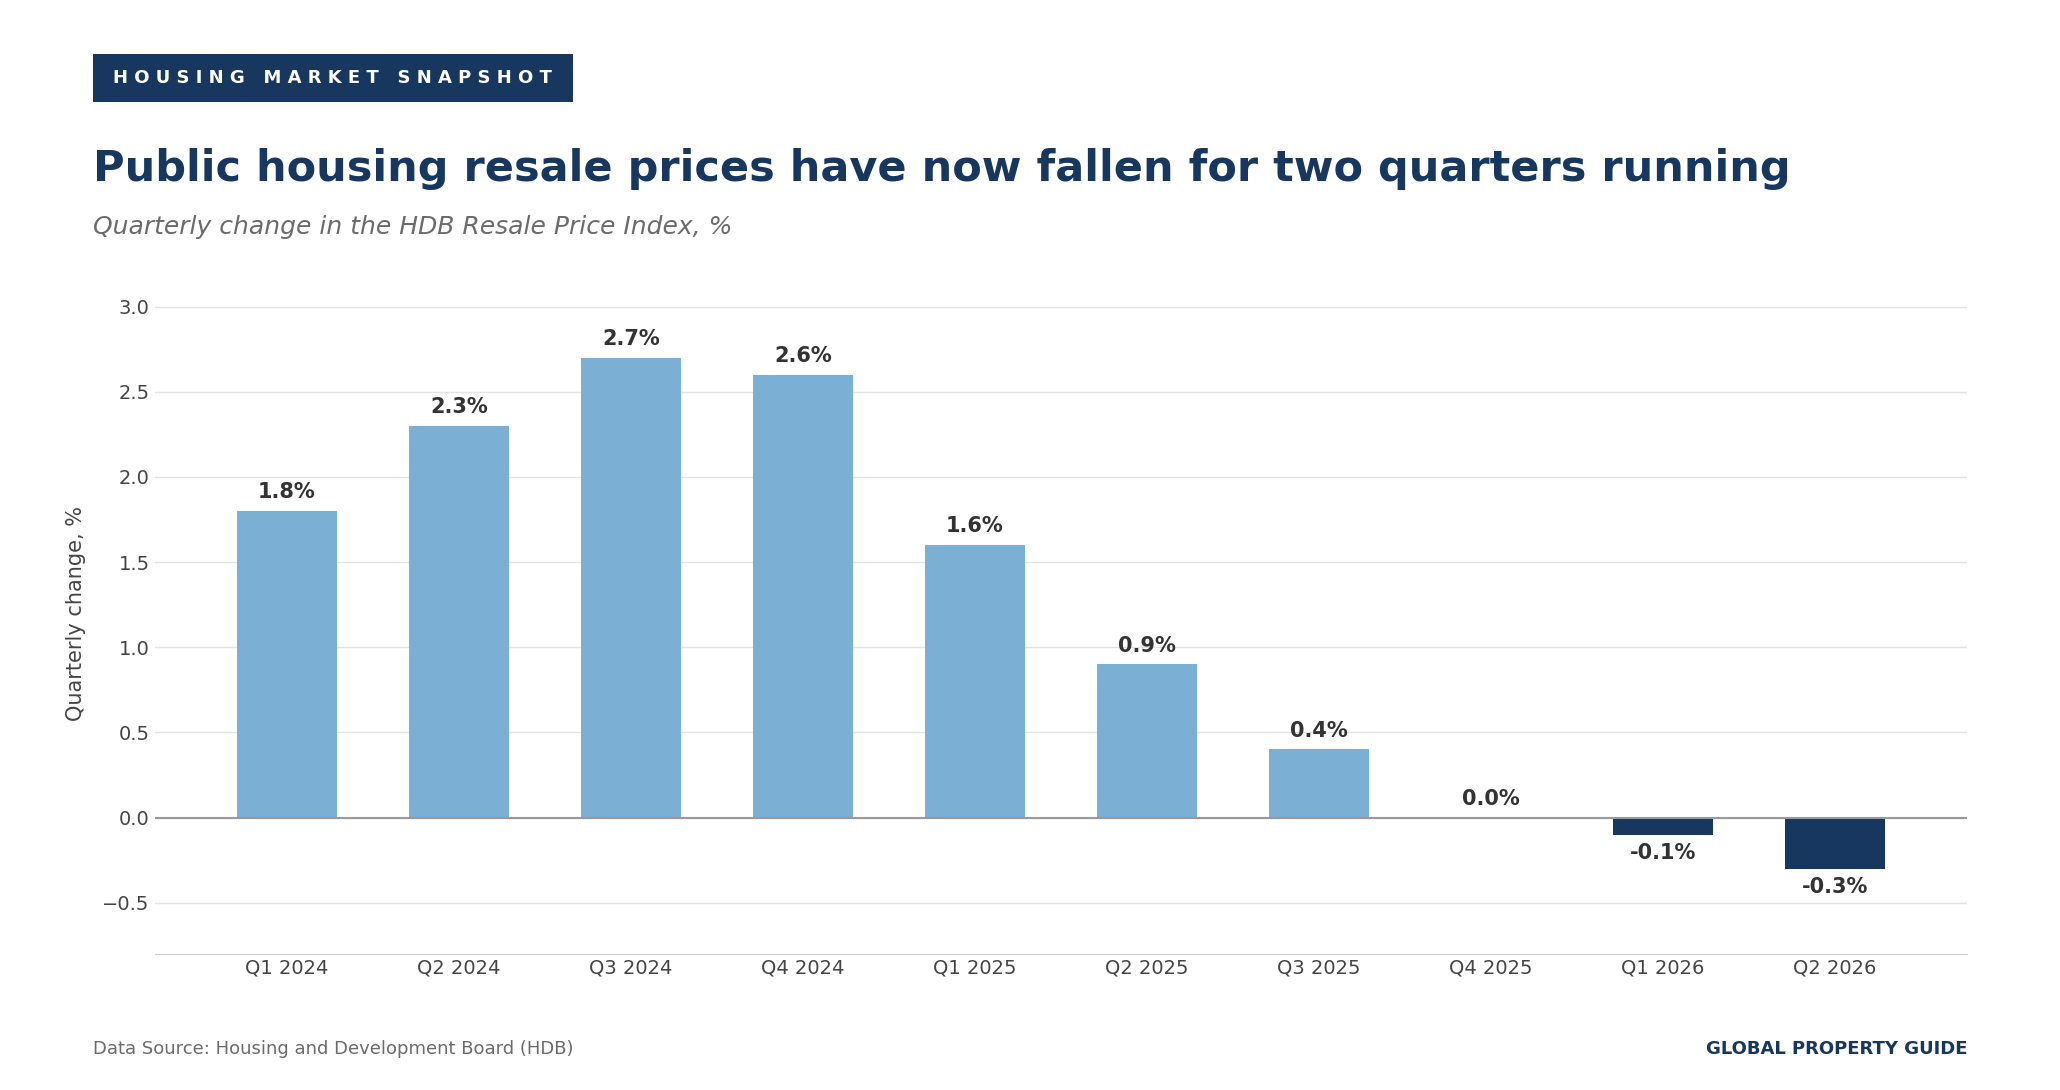
The cheap-money phase that carried Singapore's housing market into 2026 is ending. Interest rates bottomed in June and are rising again, the US Federal Reserve has resumed hiking, and the Monetary Authority of Singapore has tightened policy twice this year. Private home prices are still rising, but at the slowest pace in almost two years, while public housing resale prices have now fallen for two quarters running.
This extended overview from Global Property Guide covers key aspects of the Singaporean housing market and takes a closer look at its most recent developments and long-term trends.
Table of Contents
- Property Prices and Price Index
- Property Supply Trends
- Property Demand Trends
- Rental Market: Rents and Rental Yields
- Mortgage Market and Interest Rates
- Economic and Social Factors
Property Prices and Price Index
Private residential prices in Singapore rose for a seventh consecutive quarter in Q2 2026, but the momentum is fading. Based on the Urban Redevelopment Authority (URA) Property Price Index, prices for all private residential properties increased by 0.50% quarter-on-quarter in Q2 2026, after 0.88% in Q1, and by 2.91% year-on-year, down from 3.41% in the previous quarter. That brought cumulative growth in the first half of 2026 to 1.4%, below the 1.8% recorded in the first half of 2025, and marked the weakest quarterly reading since Q3 2024, when prices last fell.
Singapore's house price annual change:
The headline conceals a sharp divergence between segments. Prices of landed homes (privately owned terrace houses, semi-detached houses, bungalows and shophouses) rebounded by 2.50% in the quarter, reversing the 0.40% decline recorded in Q1, and now stand 7.04% higher than a year earlier. Non-landed homes (strata-titled condominiums and apartments), which carried the market in the previous quarter, slipped by 0.09%.
Within the non-landed segment, the regional ranking has inverted. In our previous edition, the Outside Central Region (OCR), Singapore's suburban market, led the country with a 2.18% quarterly gain. In Q2 2026, it edged down by 0.11%. The Core Central Region (CCR), the prime districts around Orchard, Tanglin and the downtown core, was the strongest non-landed market with a 1.83% rise. The Rest of Central Region (RCR), the city fringe, fell by 1.18% and its index is now below its end-2025 level. CBRE linked the RCR decline to realistic pricing at Hudson Place Residences, which sold 218 units at a median of SGD 2,467 (USD 1,928) per square foot, 2% below the SGD 2,518 (USD 1,968) achieved at the neighbouring Bloomsbury Residences.
Property Price Index of Private Residential Properties, quarterly and annual movement:
| Quarterly Movement (QoQ), Q2 2026 vs Q1 2026 |
Annual Movement (YoY), Q2 2026 vs Q2 2025 |
|
| All properties (whole island) | 0.50% | 2.91% |
| Landed properties (whole island) | 2.50% | 7.04% |
| Non-landed properties (whole island) | -0.09% | 1.84% |
| Core Central Region (CCR) | 1.83% | 0.50% |
| Rest of Central Region (RCR) | -1.18% | 0.62% |
| Outside Central Region (OCR) | -0.11% | 3.91% |
| Note: Changes computed from URA index levels. Non-landed regional figures refer to non-landed properties only. | ||
| Data source: URA. | ||
The CCR's annual figure is worth reading carefully. Despite the strong second quarter, prime non-landed prices are only 0.50% higher than a year ago, because the segment's index fell by 3.5% in Q4 2025. The quarterly strength is a partial recovery rather than a new upswing.
The URA's own flash estimates also deserve caution. The flash estimate for Q2 2026, published on 1 July, showed CCR prices up 2.0%, RCR prices down 1.4% and landed prices up 2.6%, all revised in the final release three weeks later. The Q3 2026 flash estimate is due at the start of October.
Market expectations for 2026 have held up but narrowed. PropNex maintains its forecast of 3% to 4% price growth for the full year, Huttons expects 2% to 5%, and Savills maintains around 3%. With 1.4% recorded in the first half, reaching PropNex's range requires prices to rise faster in the second half than in the first, in a quarter in which borrowing costs have started to rise.
Public Housing Resale Prices Have Stopped Rising
The cooling is most visible in public housing. The Housing and Development Board (HDB) Resale Price Index fell by 0.3% quarter-on-quarter to 202.8 in Q2 2026, after a 0.1% dip in Q1. It is the first back-to-back decline since the four consecutive falls between Q3 2018 and Q2 2019. The index is now essentially unchanged from its level a year ago and 0.4% below its Q3 2025 peak. In the first half of 2026, resale prices fell by 0.4%, against a 2.5% rise in the first half of 2025.
Volumes softened too. According to ERA, 6,396 resale flats changed hands in Q2 2026, down 9.9% from a year earlier. Analysts attribute the slowdown to competition from new Build-To-Order flats, more flats reaching the end of their minimum occupation period, and buyer caution over the job market. The number of flats sold for at least SGD 1 million nonetheless kept rising, reaching 491 in the quarter.
The HDB plays a central role in Singapore's housing landscape, developing and managing residential estates to ensure affordability for citizens. Ownership is restricted to Singaporeans and eligible permanent residents, with a minimum occupation period of five years before resale. As of 2025, HDB flats accommodated 77.2% of resident households, according to the Singapore Department of Statistics (DOS).
Property Supply Trends
Launches Stay Thin and Inventory Keeps Falling
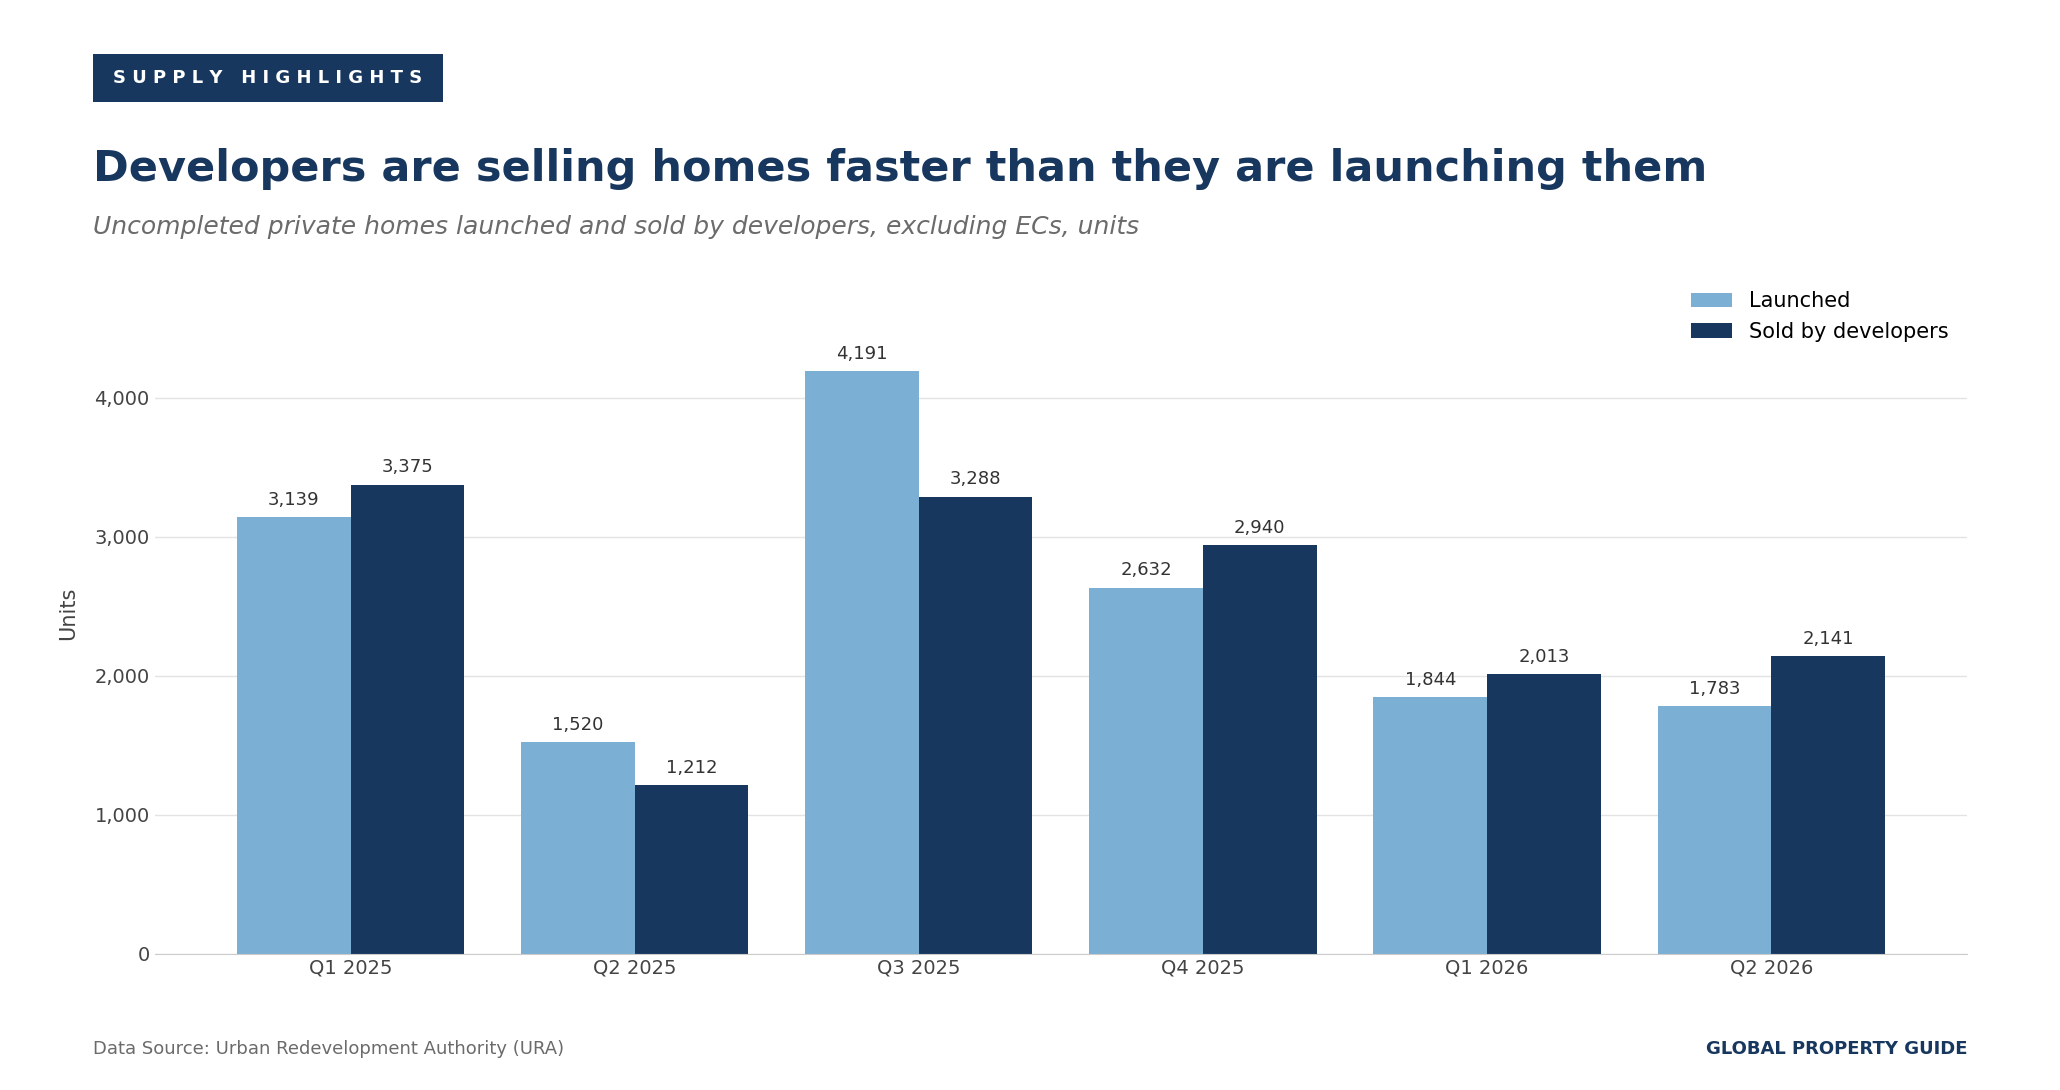
New private supply remained limited in the first half of 2026. Developers launched 1,783 uncompleted private residential units, excluding executive condominiums (ECs), in Q2 2026, compared with 1,844 units in Q1. Over the first half, launches totalled 3,627 units, 22.15% fewer than in the first half of 2025.
The geography of new supply swung again. No new units were launched in the CCR during the quarter, after 701 in Q1, while the OCR accounted for 1,406 units and the RCR for 377. The quarter's main launches were Tengah Garden Residences and Vela Bay in the OCR and Hudson Place Residences in the RCR.
Uncompleted private residential units launched by submarket:
| Units Launched, H1 2025 |
Units Launched, H1 2026 |
YoY | |
| Core Central Region (CCR) | 96 | 701 | 630.21% |
| Rest of Central Region (RCR) | 2,259 | 377 | -83.31% |
| Outside Central Region (OCR) | 2,304 | 2,549 | 10.63% |
| Total | 4,659 | 3,627 | -22.15% |
| Data source: URA. | |||
Developers Are Selling Faster Than They Are Launching
For the third consecutive quarter, developers sold more homes than they launched. New sales of 2,141 units in Q2 2026 exceeded launches by 358 units, and the pattern is drawing down the stock of unsold homes.
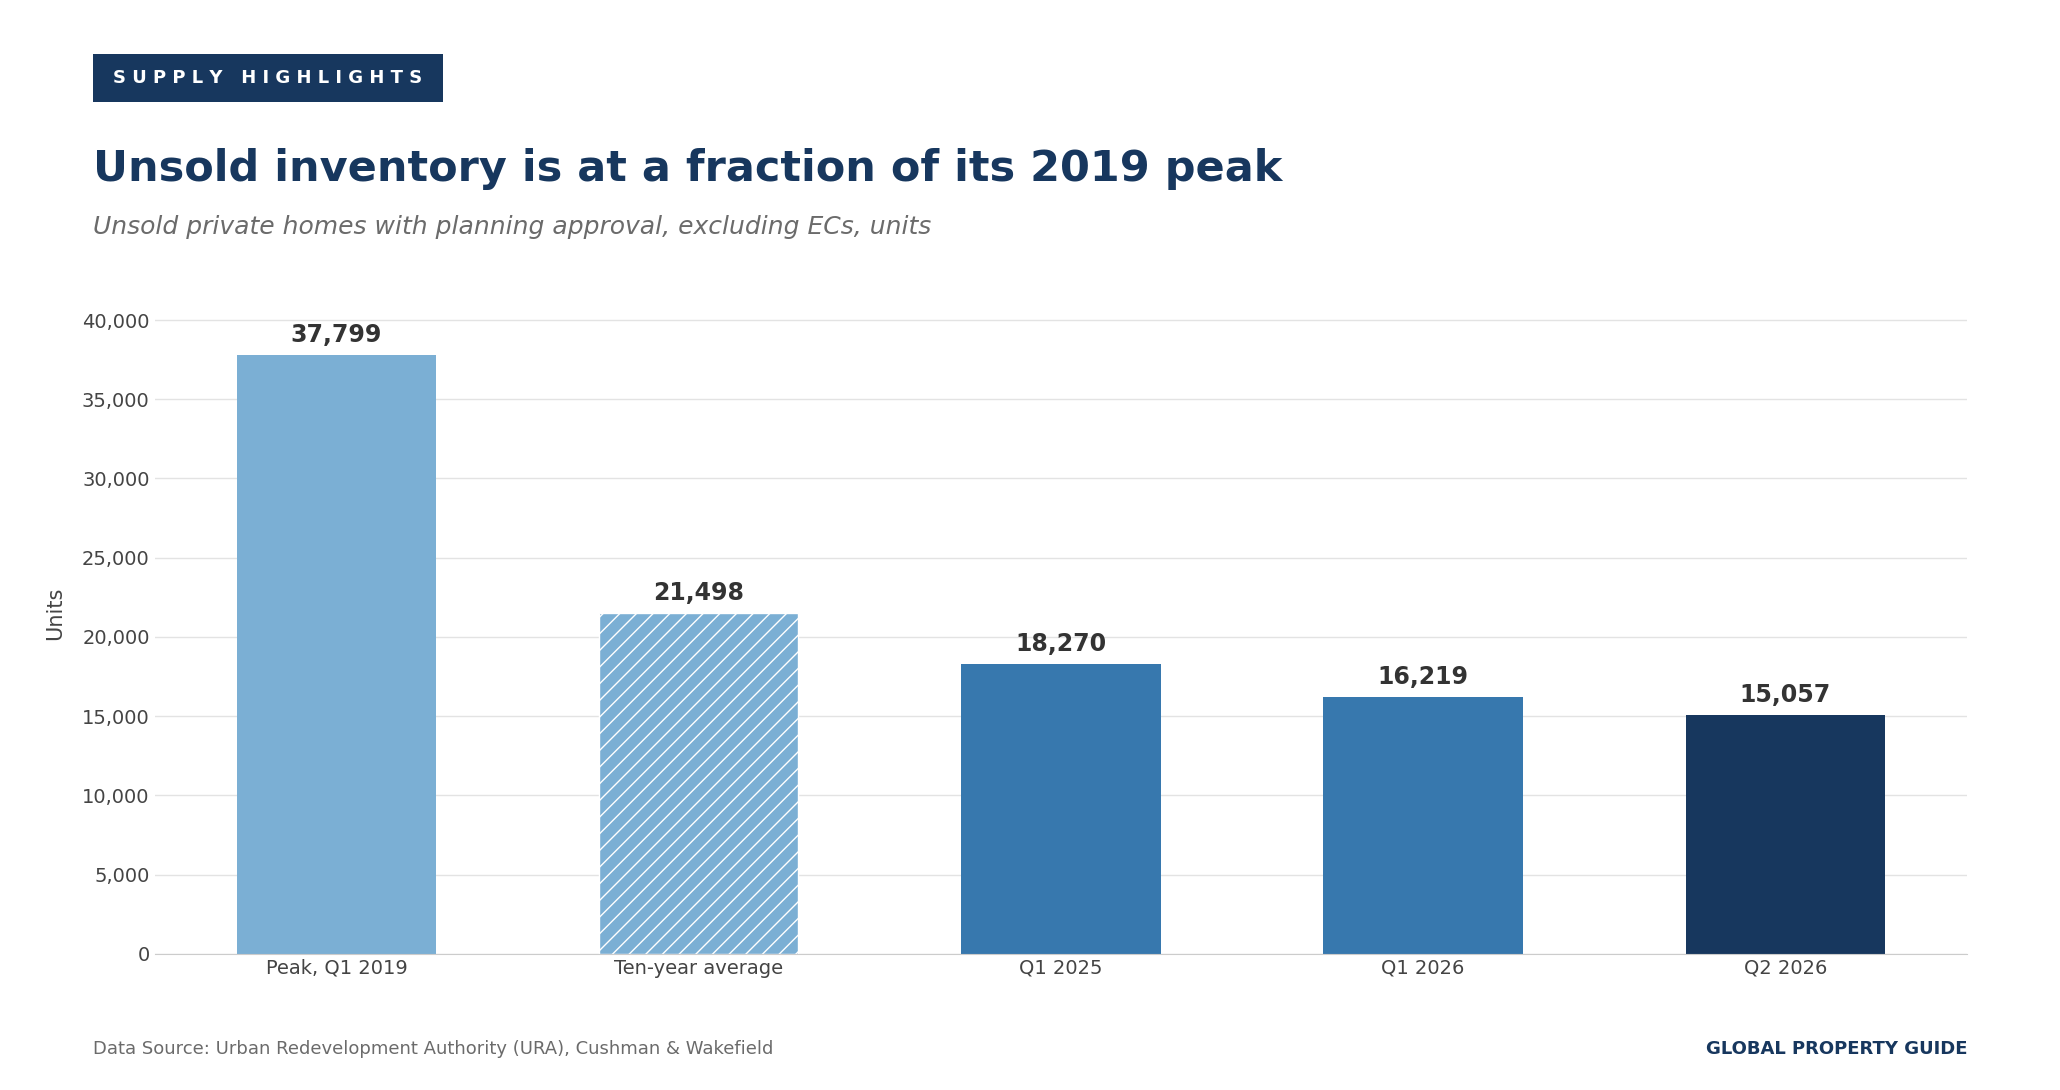
Total unsold private residential inventory with planning approval, excluding ECs, fell by 7.2% quarter-on-quarter to 15,057 units at the end of Q2 2026, of which 14,929 were in uncompleted projects and only 128 in completed ones. That reverses the 8.1% increase recorded in Q1 and leaves inventory around 60% below the peak of 37,799 units in Q1 2019 and well below the ten-year annual average of 21,498 units that Cushman and Wakefield cited earlier this year. The sharpest drawdown was in the RCR, where uncompleted unsold stock fell by 11.9%.
The pipeline beyond the next two years is larger. According to the URA, about 60,600 private residential units, including ECs, are expected to be completed in the coming years, up from about 55,800 at the time of our previous edition: about 25,900 units by 2028 and about 34,700 from 2029 onward. Only 1,212 units, including ECs, were completed in Q2 2026.
The Government Is Keeping Land Supply High
The government has kept its land supply elevated. The second-half 2026 Government Land Sales Confirmed List offers sites for 4,745 private residential units, including 735 EC units, bringing the full-year Confirmed List to 9,320 units, more than 50% above the average of the past ten years. Developers are bidding confidently: CBRE notes that three CCR tenders closed in Q2 2026 at benchmark prices above comparable 2025 tenders in the same locations.
Property Demand Trends
Resales Rebound as New Sales Fade
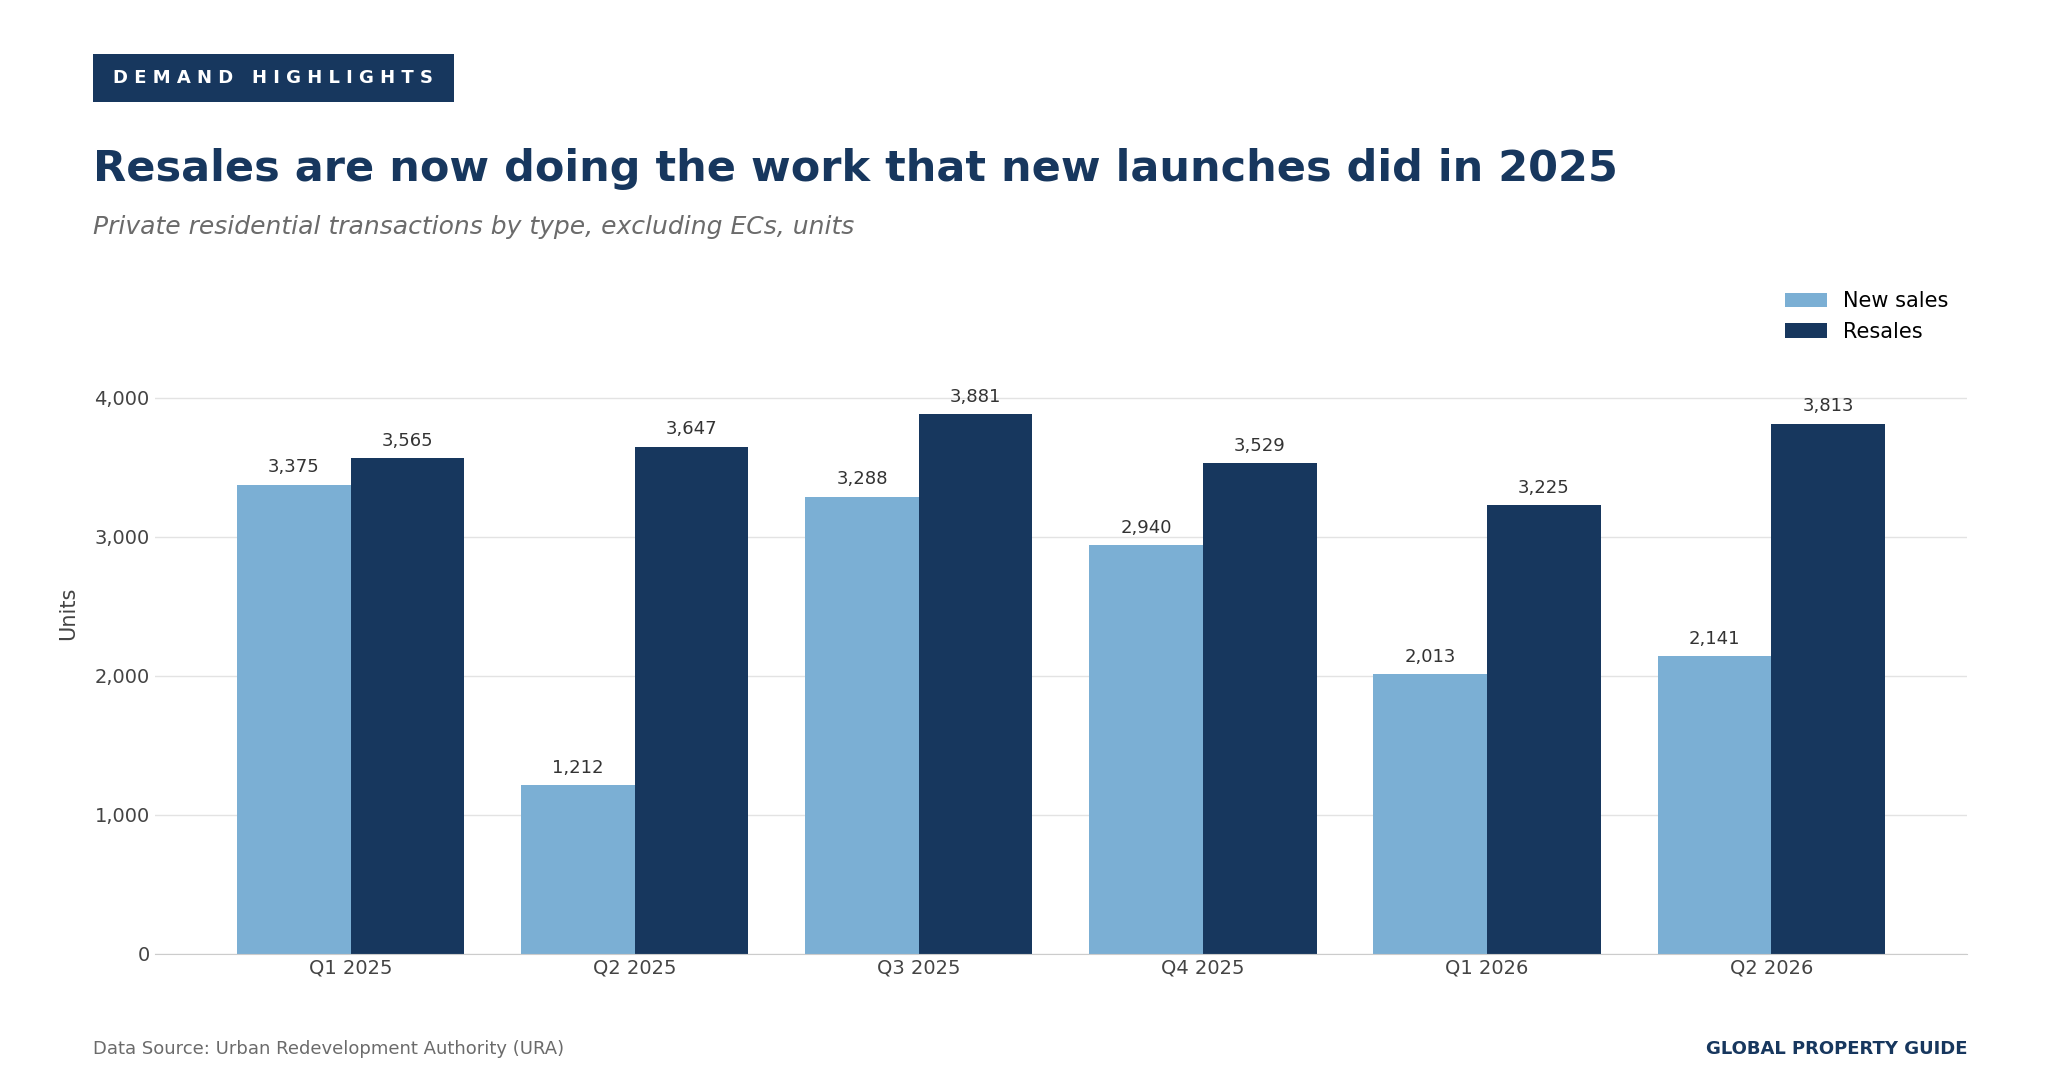
Singapore's private residential transactions rebounded in Q2 2026 after a weak start to the year. According to URA data, 6,148 private homes excluding ECs were transacted in the quarter, up 13.58% from Q1 and 19.89% from Q2 2025, a quarter depressed by a lull in launches. Over the first half as a whole, however, transactions totalled 11,561 units, 6.68% fewer than in the first half of 2025.
The composition of demand is the important change. In 2025, the recovery was led by the primary market, where developer sales rose 67.18%. In Q2 2026, resales did the work: 3,813 resale transactions were recorded, up 18.23% on the quarter and 4.55% on the year, lifting the resale share of the market to 62.0%. New sales rose 76.65% year-on-year to 2,141 units, but from an unusually low base, and first-half new sales of 4,154 units were still 9.44% below the first half of 2025. Sub-sales rose to 194 units, ending a run of four consecutive quarterly declines, but remained at 3.2% of the market.
The Suburbs Led, the City Fringe Lagged
Regionally, demand concentrated further in the OCR, which accounted for 58.0% of transactions in Q2 2026, up from around half in Q1. OCR sales rose 55.0% year-on-year to 3,564 units, helped by launch-weekend take-up of 99% at Tengah Garden Residences and 72% at Vela Bay, as reported by ERA. The CCR recorded 804 transactions, up 15.0%, with almost nine in ten of them resales, since developers sold just 70 new CCR units in the absence of new launches. The RCR was the only region with fewer sales than a year earlier, down 16.4% to 1,780 units.
Number of residential units sold by submarket:
| New Sales, Q2 2026 |
YoY | Resales, Q2 2026 |
YoY | Sub-sales, Q2 2026 |
YoY | |
| Core Central Region (CCR) | 70 | 59.09% | 715 | 11.72% | 19 | 26.67% |
| Rest of Central Region (RCR) | 577 | -36.03% | 1,131 | 4.14% | 72 | -48.94% |
| Outside Central Region (OCR) | 1,494 | 461.65% | 1,967 | 2.39% | 103 | -8.85% |
| Total | 2,141 | 76.65% | 3,813 | 4.55% | 194 | -27.88% |
| Data source: URA. | ||||||
New Sales Slumped Over the Summer
Monthly developer data point to a weak third quarter for the primary market. Developers sold 731 new homes excluding ECs in July, 22.2% fewer than a year earlier, with Lentor Gardens Residences in the OCR selling 270 units at a median of SGD 2,357 (USD 1,842) per square foot. In August, sales collapsed to 153 units, down 79.1% from July and 92.9% from August 2025, the lowest monthly figure since February 2024. No new project was launched during the Lunar seventh month, traditionally a quiet period.
That leaves 5,038 new homes sold in the first eight months of 2026. CBRE still expects 7,500 to 8,500 new sales for the year, Huttons 7,500 to 9,000 and PropNex about 9,000. Even the lowest of those figures requires developers to sell more than 600 units a month from September to December, not far below July's pace, and Huttons expects launches for the full year to be the lowest since 2023.
Demand Remains Overwhelmingly Domestic
Singapore's private residential demand remains overwhelmingly domestic. Under the current Additional Buyer's Stamp Duty framework, foreigners buying any residential property pay a 60% ABSD, while Singapore citizens pay no ABSD on their first residential property and permanent residents pay 5%. The framework is unchanged this year despite industry requests ahead of the 2026 Budget for relief on ultra-luxury homes. PropNex reports that citizens and permanent residents accounted for 98.3% of new non-landed purchases in the first half of 2026.
Rental Market: Rents and Rental Yields
Rents Firm Up While Vacancy Creeps Higher
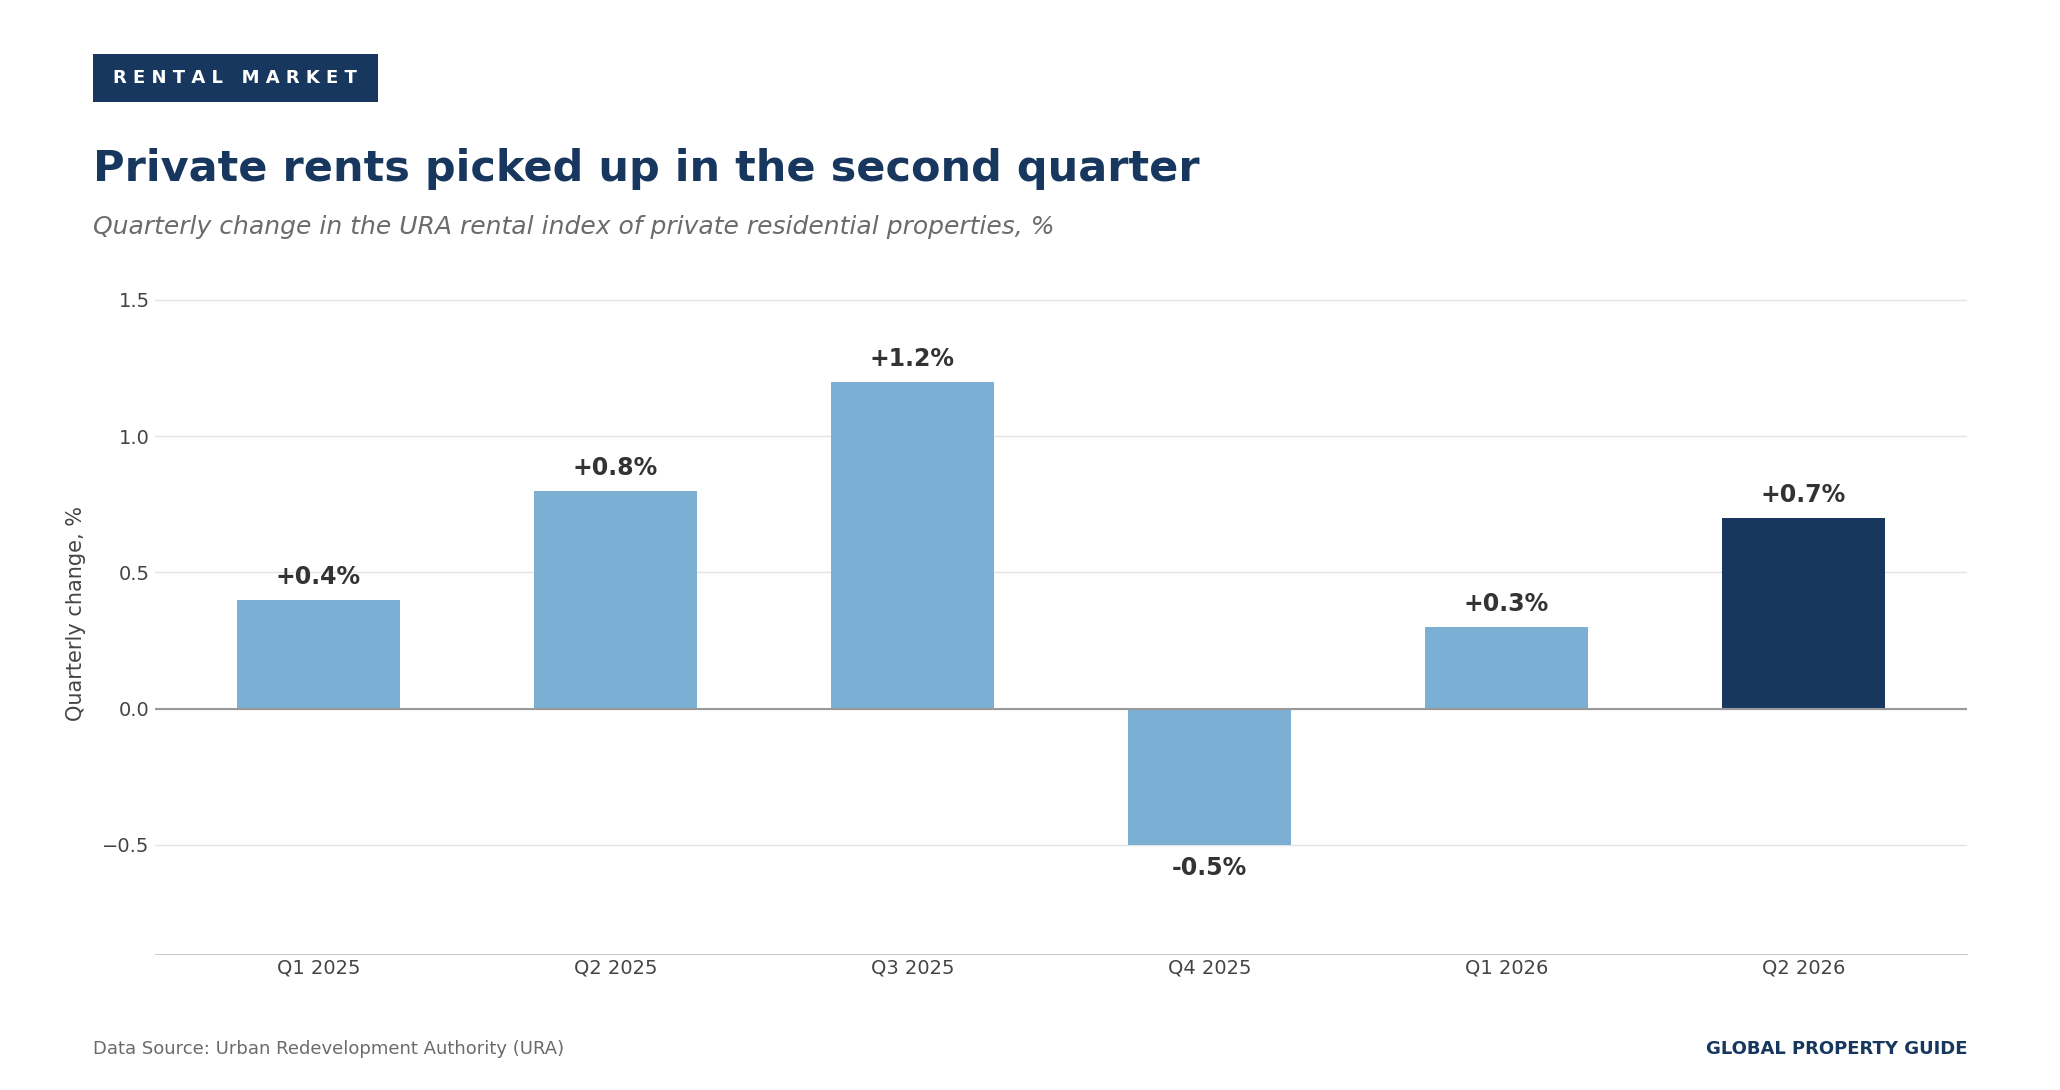
Private rents accelerated modestly in Q2 2026. The URA's Rental Index of Private Sector Residential Properties rose by 0.7% quarter-on-quarter, after 0.3% in Q1, and by 1.7% year-on-year. Growth in the first half totalled 1.0%.
Singapore's rent price index:
Our previous edition described rents as posting modest growth for five consecutive quarters. That was true on an annual basis, but on a quarterly basis the index fell by 0.5% in Q4 2025 before resuming its rise.
Landed rents drove the quarter with a 2.7% rise, while non-landed rents rose 0.4%. Among non-landed homes, rents increased by 1.2% in the CCR, were unchanged in the RCR, and fell by 0.3% in the OCR, a reversal of Q1, when the suburbs led.
Rental Index of Private Sector Residential Properties, quarterly and annual movement:
| Quarterly Movement (QoQ), Q2 2026 vs Q1 2026 |
Annual Movement (YoY), Q2 2026 vs Q2 2025 |
|
| All properties (whole island) | 0.7% | 1.7% |
| Landed properties (whole island) | 2.7% | 2.2% |
| Non-landed properties (whole island) | 0.4% | 1.8% |
| Core Central Region (CCR) | 1.2% | 1.9% |
| Rest of Central Region (RCR) | 0.0% | 2.2% |
| Outside Central Region (OCR) | -0.3% | 1.2% |
| Note: Annual changes computed from URA index levels. | ||
| Data source: URA. | ||
Leasing volumes were firm. Savills, citing URA data, reports 22,290 private rental contracts commencing in Q2 2026, up 5.1% on the quarter and 3.0% on the year, with increases in all three regions. The consultancy noted stronger demand from senior expatriate executives from North Asia for homes renting above SGD 10,000 (USD 7,814) a month.
Vacancy Is Approaching the Level That Softens Rents
The supply side is less supportive. The vacancy rate of completed private homes, excluding ECs, rose to 6.4% at the end of Q2 2026 from 6.2% in Q1, as the stock of occupied homes fell by 387 units while completed stock rose by 416. Vacancy stood at 8.3% in the CCR, 6.1% in the RCR and 5.6% in the OCR, where it rose the most. In our previous edition, Savills identified 6.5% as the threshold above which rental growth tends to soften. The market is now one-tenth of a point below it.
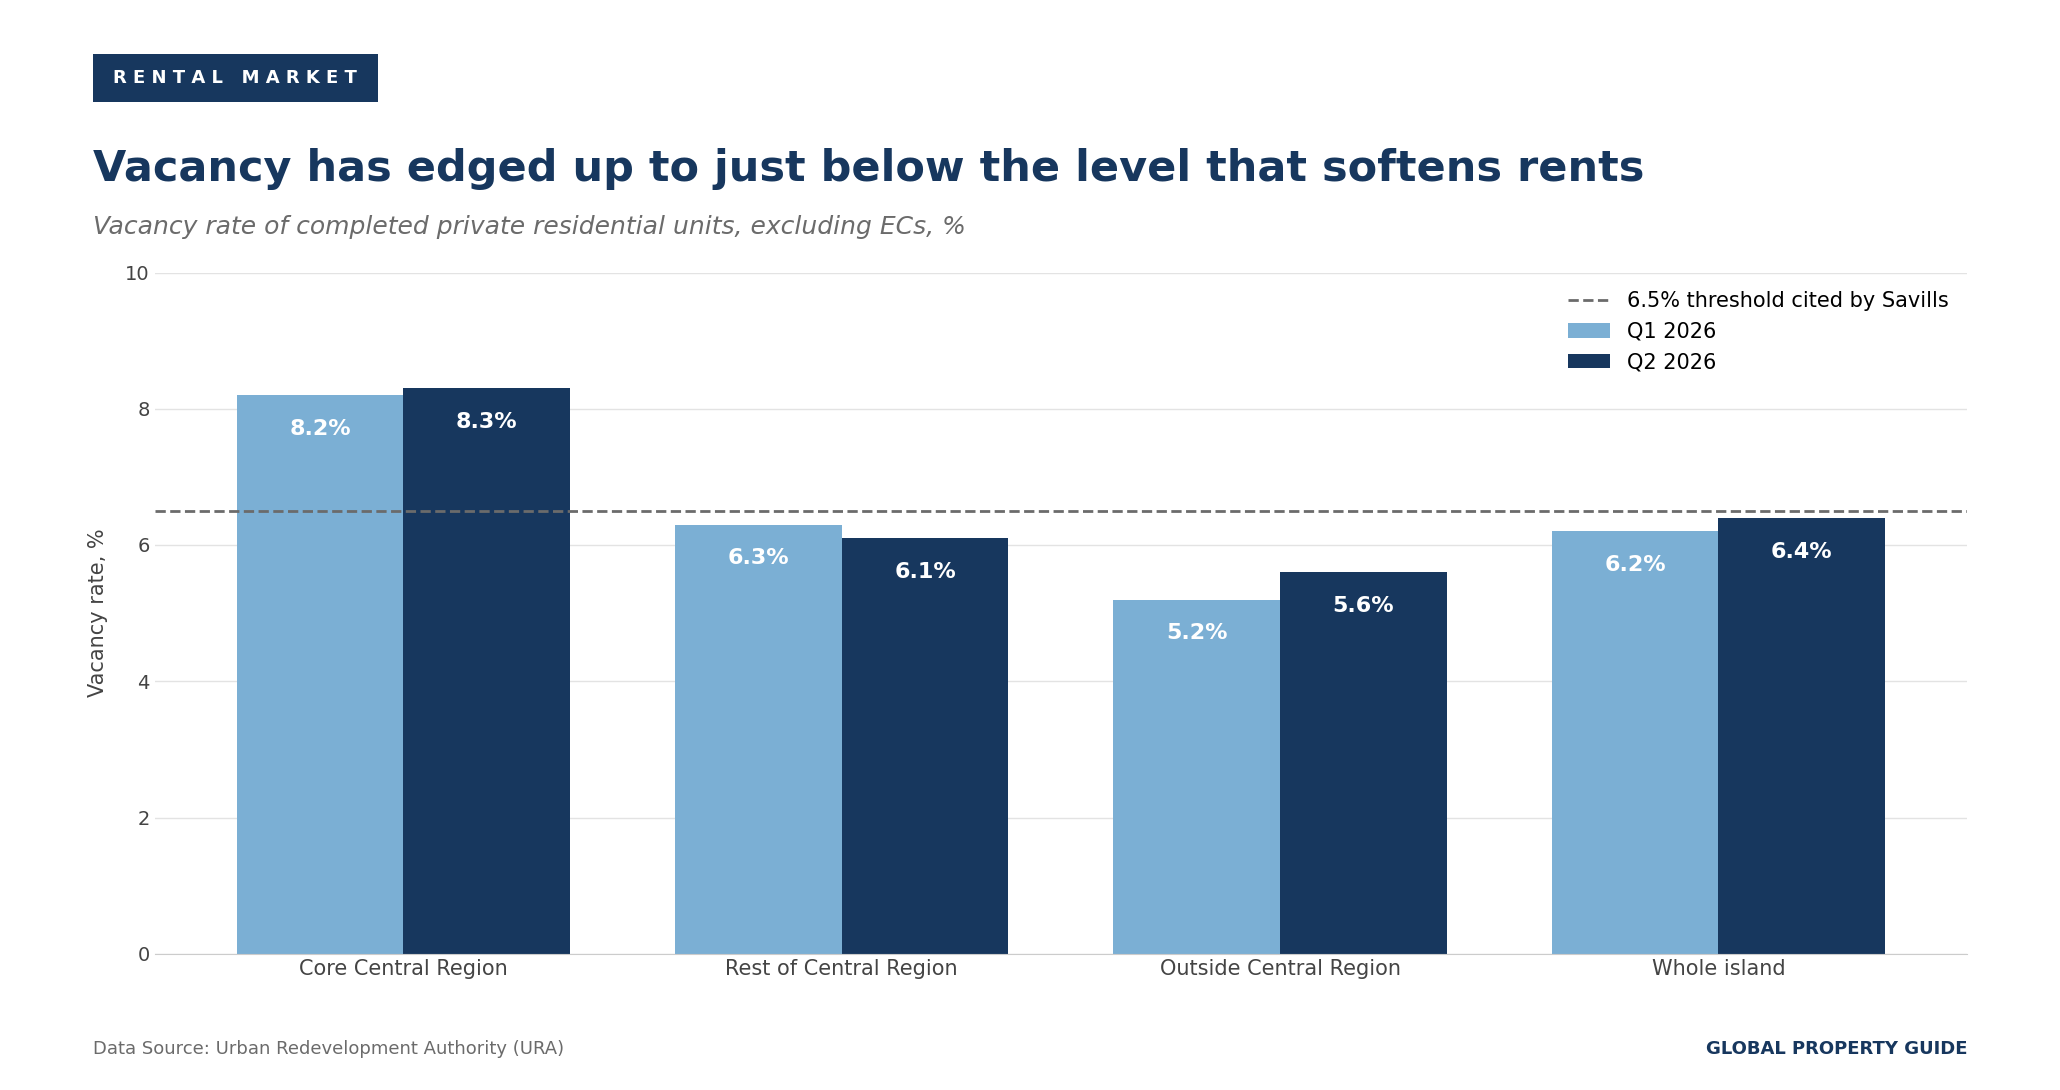
Forecasts reflect that balance. Savills expects private rents to remain broadly flat in 2026, arguing that productivity gains allow companies to expand output without matching growth in headcount. OrangeTee is slightly more positive, forecasting rental growth of 2% to 3% for the year.
Yields Remain Low but Stable
Research carried out by Global Property Guide in June 2026 shows gross rental yields on Singapore apartments averaging 3.06% in Q2 2026, broadly unchanged from the previous survey. Average advertised rents stood at USD 2,842 for 1-bedroom units, USD 3,821 for 2-bedroom units and USD 5,702 for 3-bedroom units, as published in US dollars.
Suburban Hougang, Punggol and Sengkang offered the highest average yield at 3.30%, and the highest single reading of 4.00% on 1-bedroom apartments. East Coast and Marine Parade offered the lowest at 2.72%. Across all six areas surveyed, yields fall as unit size rises.
Gross rental yields on apartments, Q2 2026:
| Area | 1-Bedroom | 2-Bedroom | 3-Bedroom | 4+ Bedroom | Average |
| Hougang / Punggol / Sengkang | 4.00% | 3.43% | 2.86% | 2.92% | 3.30% |
| Alexandra / Commonwealth | 3.74% | 3.33% | 3.11% | 2.60% | 3.20% |
| Tanglin / Holland / Bukit Timah | 3.30% | 3.03% | 3.10% | 3.18% | 3.15% |
| Orchard / River Valley | 3.66% | 3.18% | 2.82% | 2.38% | 3.01% |
| Newton / Novena | 3.43% | 3.03% | 2.91% | 2.60% | 2.99% |
| East Coast / Marine Parade | 3.14% | 2.78% | 2.74% | 2.22% | 2.72% |
| Singapore average | 3.06% | ||||
| Note: All yields are gross, before taxes, repair costs, ground rents, agents' fees, and other costs. Net yields are typically 1.5 to 2 percentage points lower. | |||||
| Data source: Global Property Guide. | |||||
Mortgage Market and Interest Rates
Interest Rates Have Bottomed and Are Rising
Unlike most central banks, the Monetary Authority of Singapore (MAS) does not conduct monetary policy by adjusting domestic interest rates. It manages the Singapore dollar nominal effective exchange rate (S$NEER), a trade-weighted basket of the currencies of major trading partners, within a policy band. Singapore's interest rates therefore depend on global markets and, above all, on US rates. The Singapore Overnight Rate Average (SORA), the benchmark for floating-rate mortgages, tends to move with the US federal funds target range while typically trending below it.
Singapore's mortgage loan interest rates:
The Rate Cycle Has Turned
Our previous edition expected SORA to bottom in Q2 2026 and then stabilize, with further US rate cuts postponed rather than reversed. The first half of that forecast proved right. The second did not.
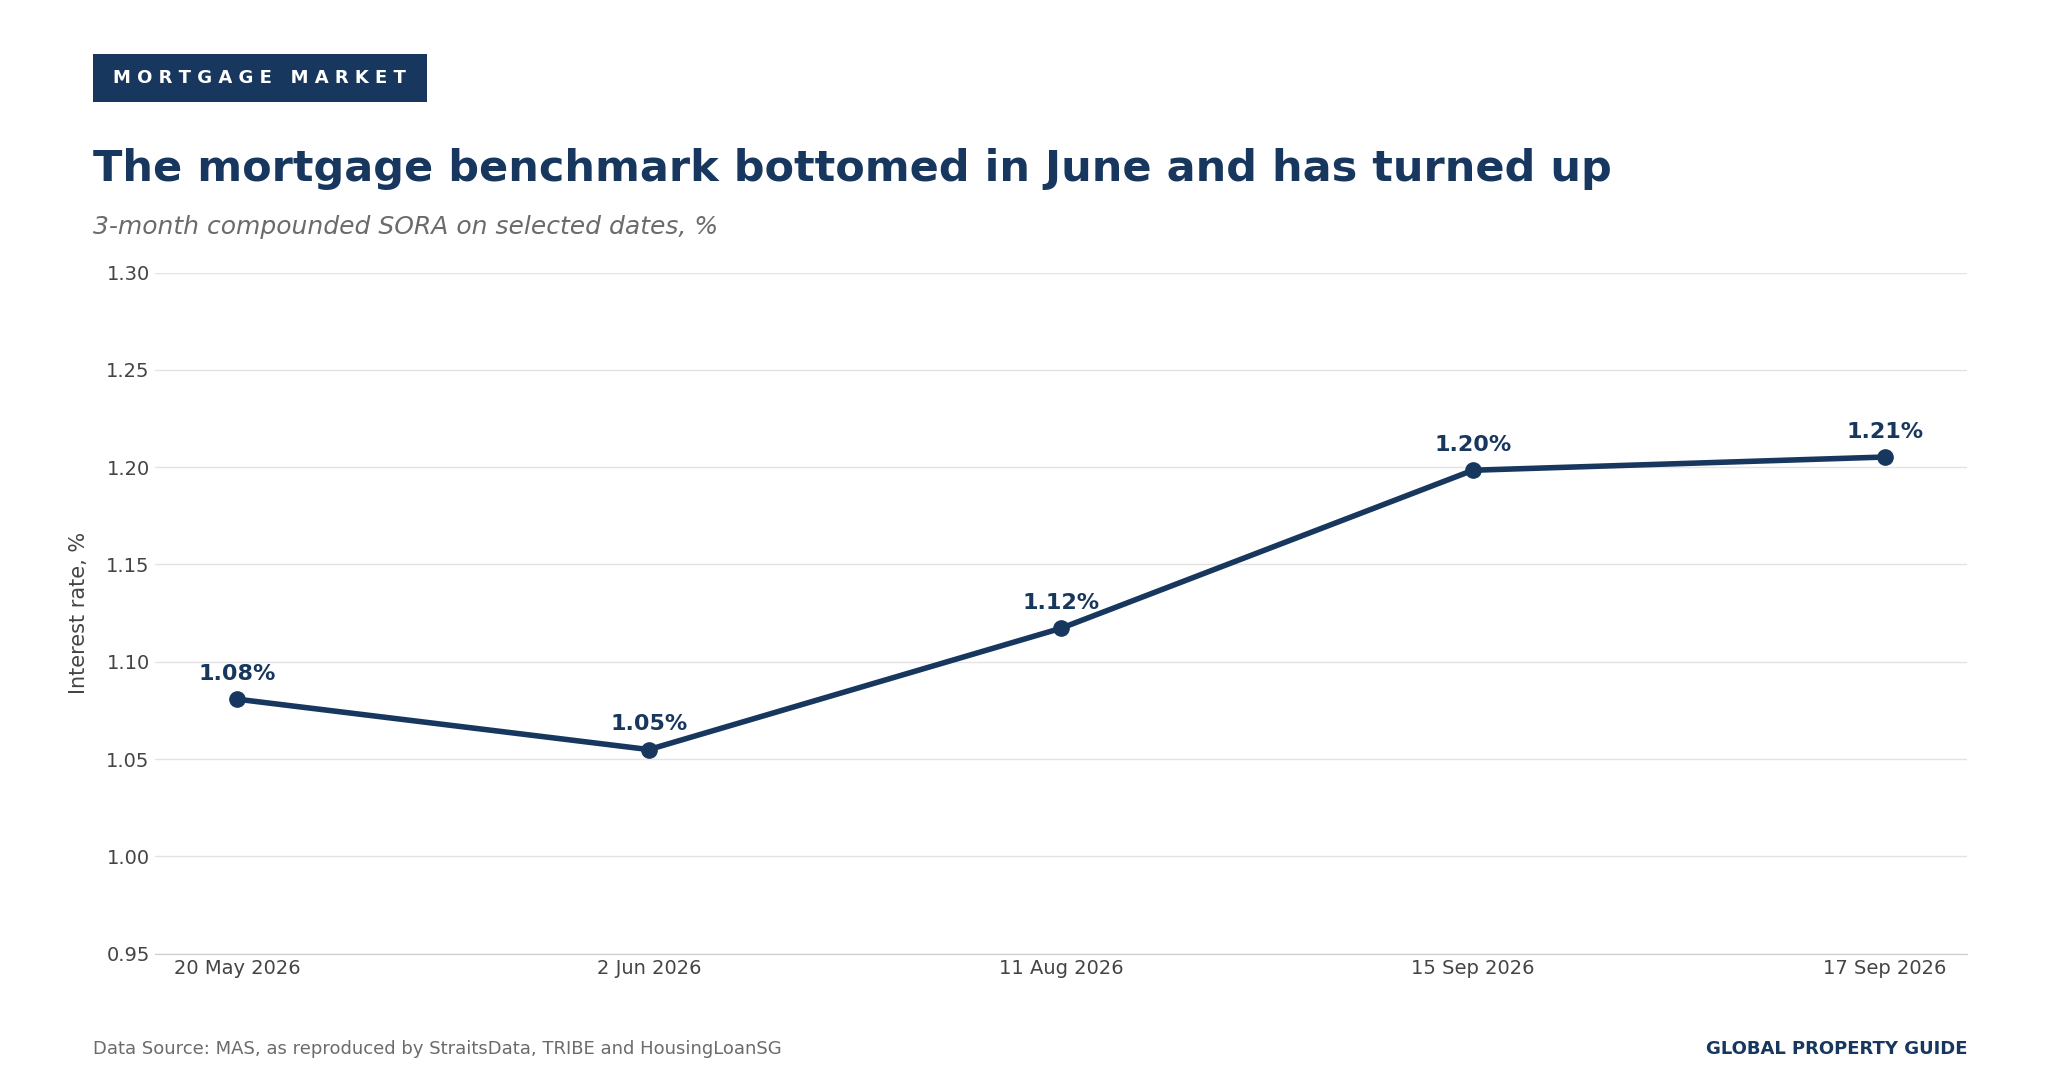
The 3-month compounded SORA fell to about 1.05% in early June, according to MAS data as reproduced by third-party trackers, and has risen since, to 1.12% on 11 August and about 1.21% by 17 September. Because compounded SORA averages past overnight rates, it lags the market: on 11 August the overnight rate was already 1.37%, a quarter-point above the compounded benchmark, which means further increases in floating mortgage rates are already locked in.
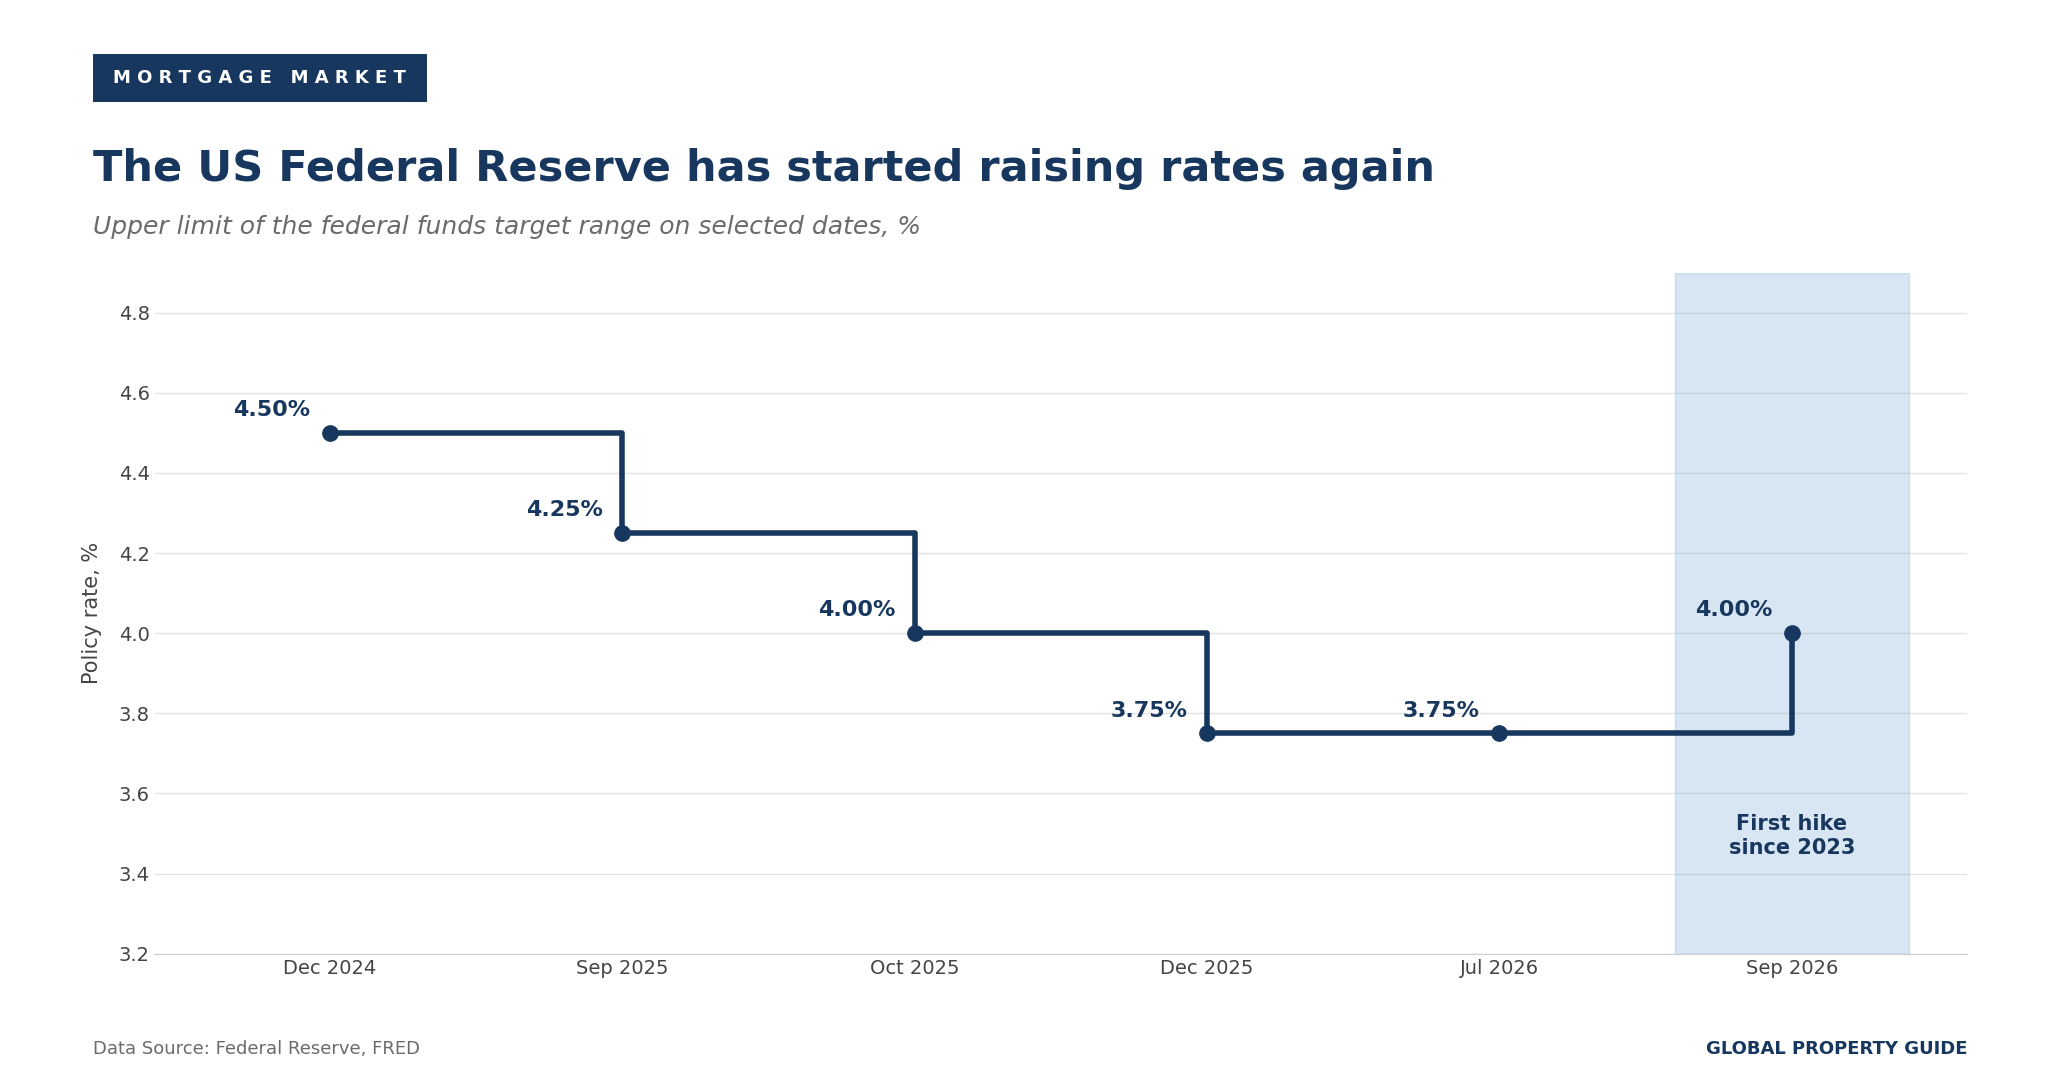
The US driver has reversed. After holding its target range at 3.50% to 3.75% through the first five meetings of 2026, with three members voting for a hike in July, the Federal Reserve raised rates by 25 basis points to 3.75% to 4.00% on 16 September 2026, its first increase since 2023. The committee said inflation "remains elevated", and its projections imply a further increase before the end of the year.
At home, MAS has tightened too. In April 2026, it slightly increased the rate of appreciation of the S$NEER policy band, and on 27 July it increased it again, very slightly, citing external price pressures expected to pass through more broadly to consumer prices. A stronger currency path restrains imported inflation rather than raising local rates directly, but it confirms that policy is no longer easing. The next policy statement is due in October.
Mortgage Packages Are Still Cheap, For Now
Banks in Singapore typically offer floating-rate mortgages priced at 1-month or 3-month compounded SORA plus a spread, and fixed-rate mortgages with a lock-in of one to three years, after which the rate reverts to SORA plus a spread. As of September 2026, the best floating packages for private homes were quoted at 1.39%, or 3-month SORA plus 0.20%, and the best 2-year fixed packages at 1.40%. Bank packages remain well below the HDB concessionary loan rate of 2.6%.
Lending Recovered Strongly in 2025
With rates at multi-year lows, lending recovered after two years of decline in new housing loans. Based on figures published by MAS, new housing loan limits granted in 2025 reached SGD 46.7 billion (USD 36.5 billion) for owner-occupied properties and SGD 8.9 billion (USD 7.0 billion) for investment properties, a combined increase of 9.1% on 2024, although the total remained below the 2021 peak of SGD 57.2 billion (USD 44.7 billion).
Outstanding housing loans grew by 4.7% in 2025, after 1.7% in 2024, to SGD 236.5 billion (USD 184.8 billion). Loans on owner-occupied properties made up about 81% of the stock and grew by 5.4%, while loans on investment properties made up about 19% and grew by 2.0%. Our previous edition reported this stock as USD 181.0 billion and the owner-occupied loan limits as USD 35.8 billion. Those figures were converted at a different exchange rate from the one declared for the article's price table, understating the loan stock by about USD 4.5 billion. All US dollar figures in this edition use a single rate: USD 1 = SGD 1.2797, as of 24 September 2026.
Sized against the economy, the residential mortgage market was equivalent to an estimated 30.0% of GDP in 2024, down from its peak of 45.3% in 2014. According to the DOS household balance sheet, mortgages represent 71.7% of total household debt, of which 60.3% are loans from financial institutions and 11.5% loans from the HDB.
Economic and Social Factors
A Stronger Economy, Higher Inflation and a Softer Job Market
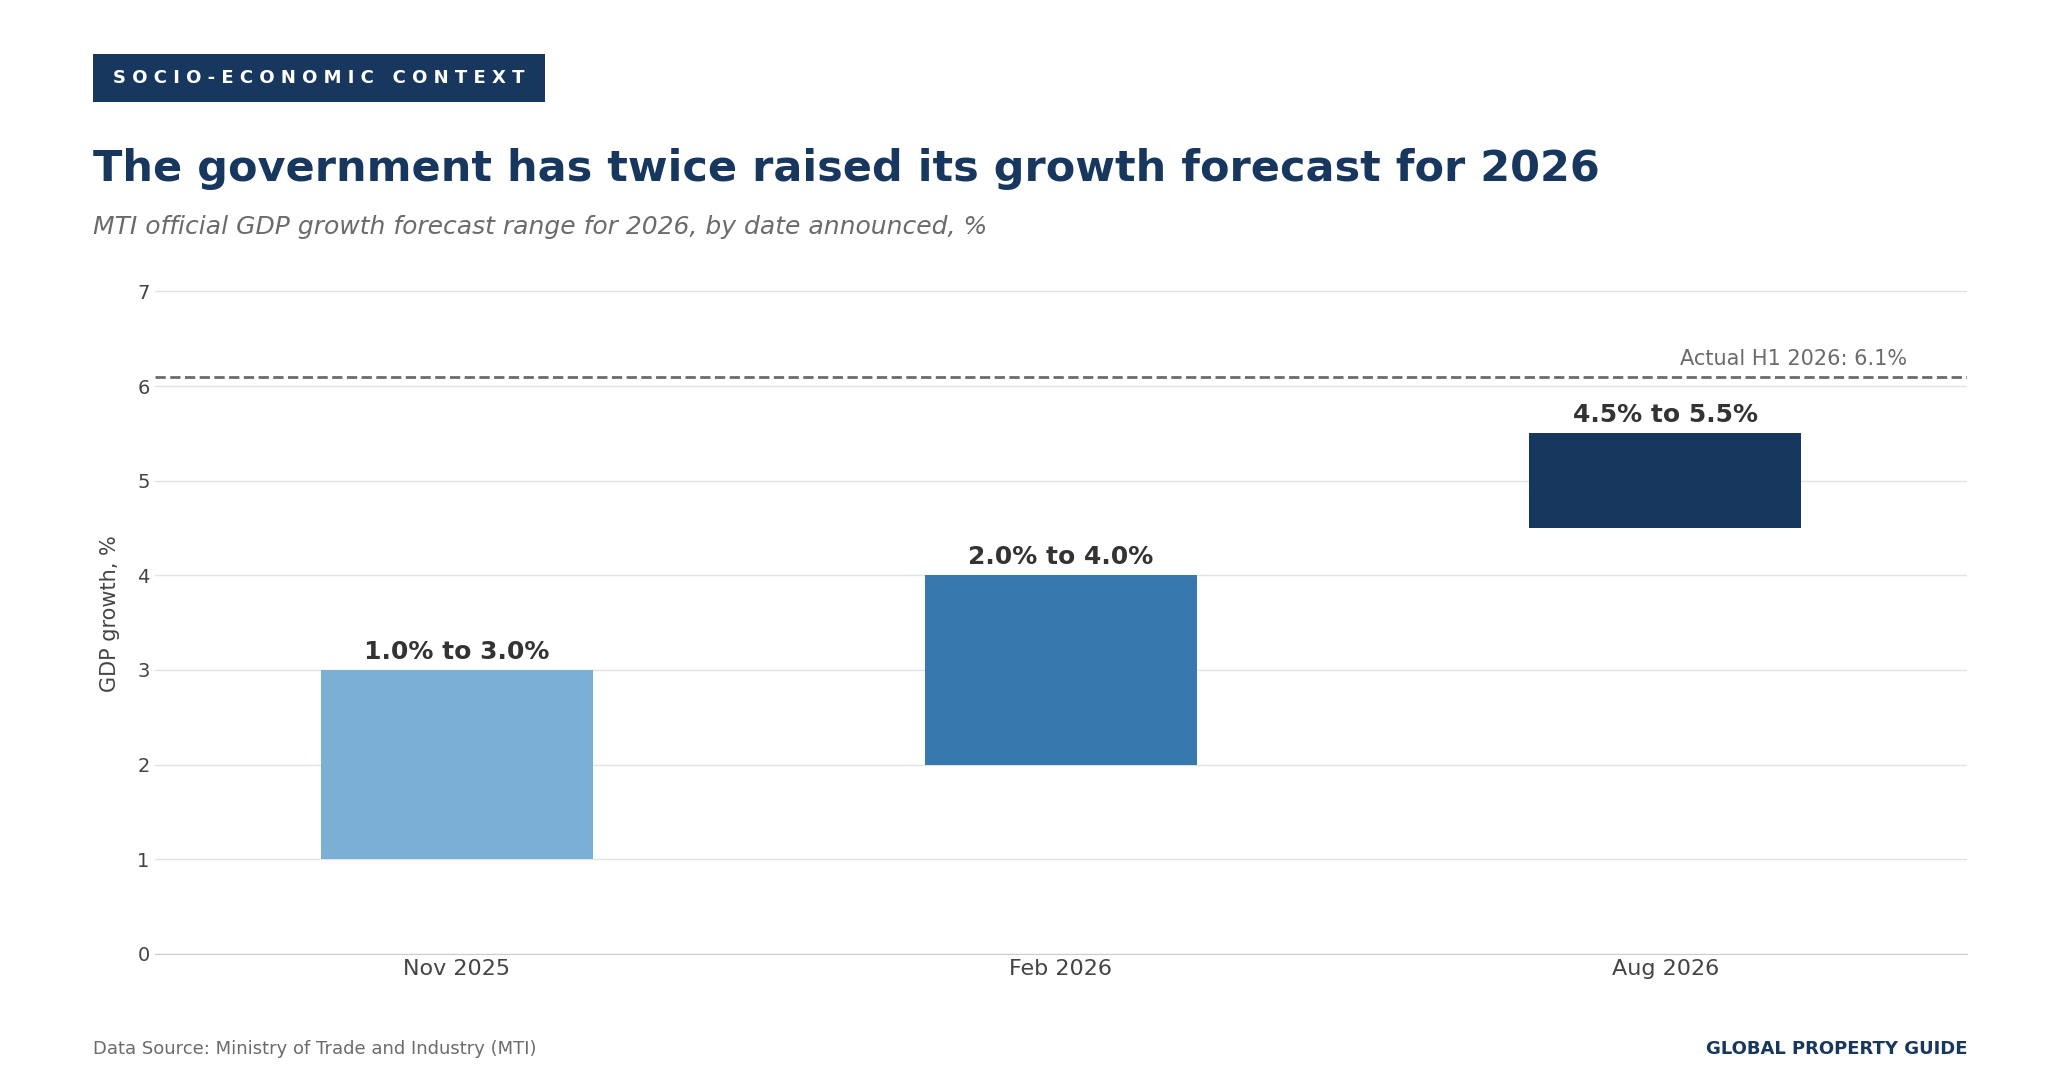
Our previous edition described an economy expected to slow, with growth risks tilted to the downside. The opposite has happened. Singapore's economy grew by 5.9% year-on-year in Q2 2026, after 6.3% in Q1, taking first-half growth to 6.1%. On 11 August, the Ministry of Trade and Industry (MTI) raised its 2026 growth forecast to 4.5% to 5.5% from 2.0% to 4.0%, its second upgrade this year, citing faster global investment in artificial intelligence. MTI also judged the economic impact of the Middle East conflict to be less severe than initially feared.
Inflation Has Returned
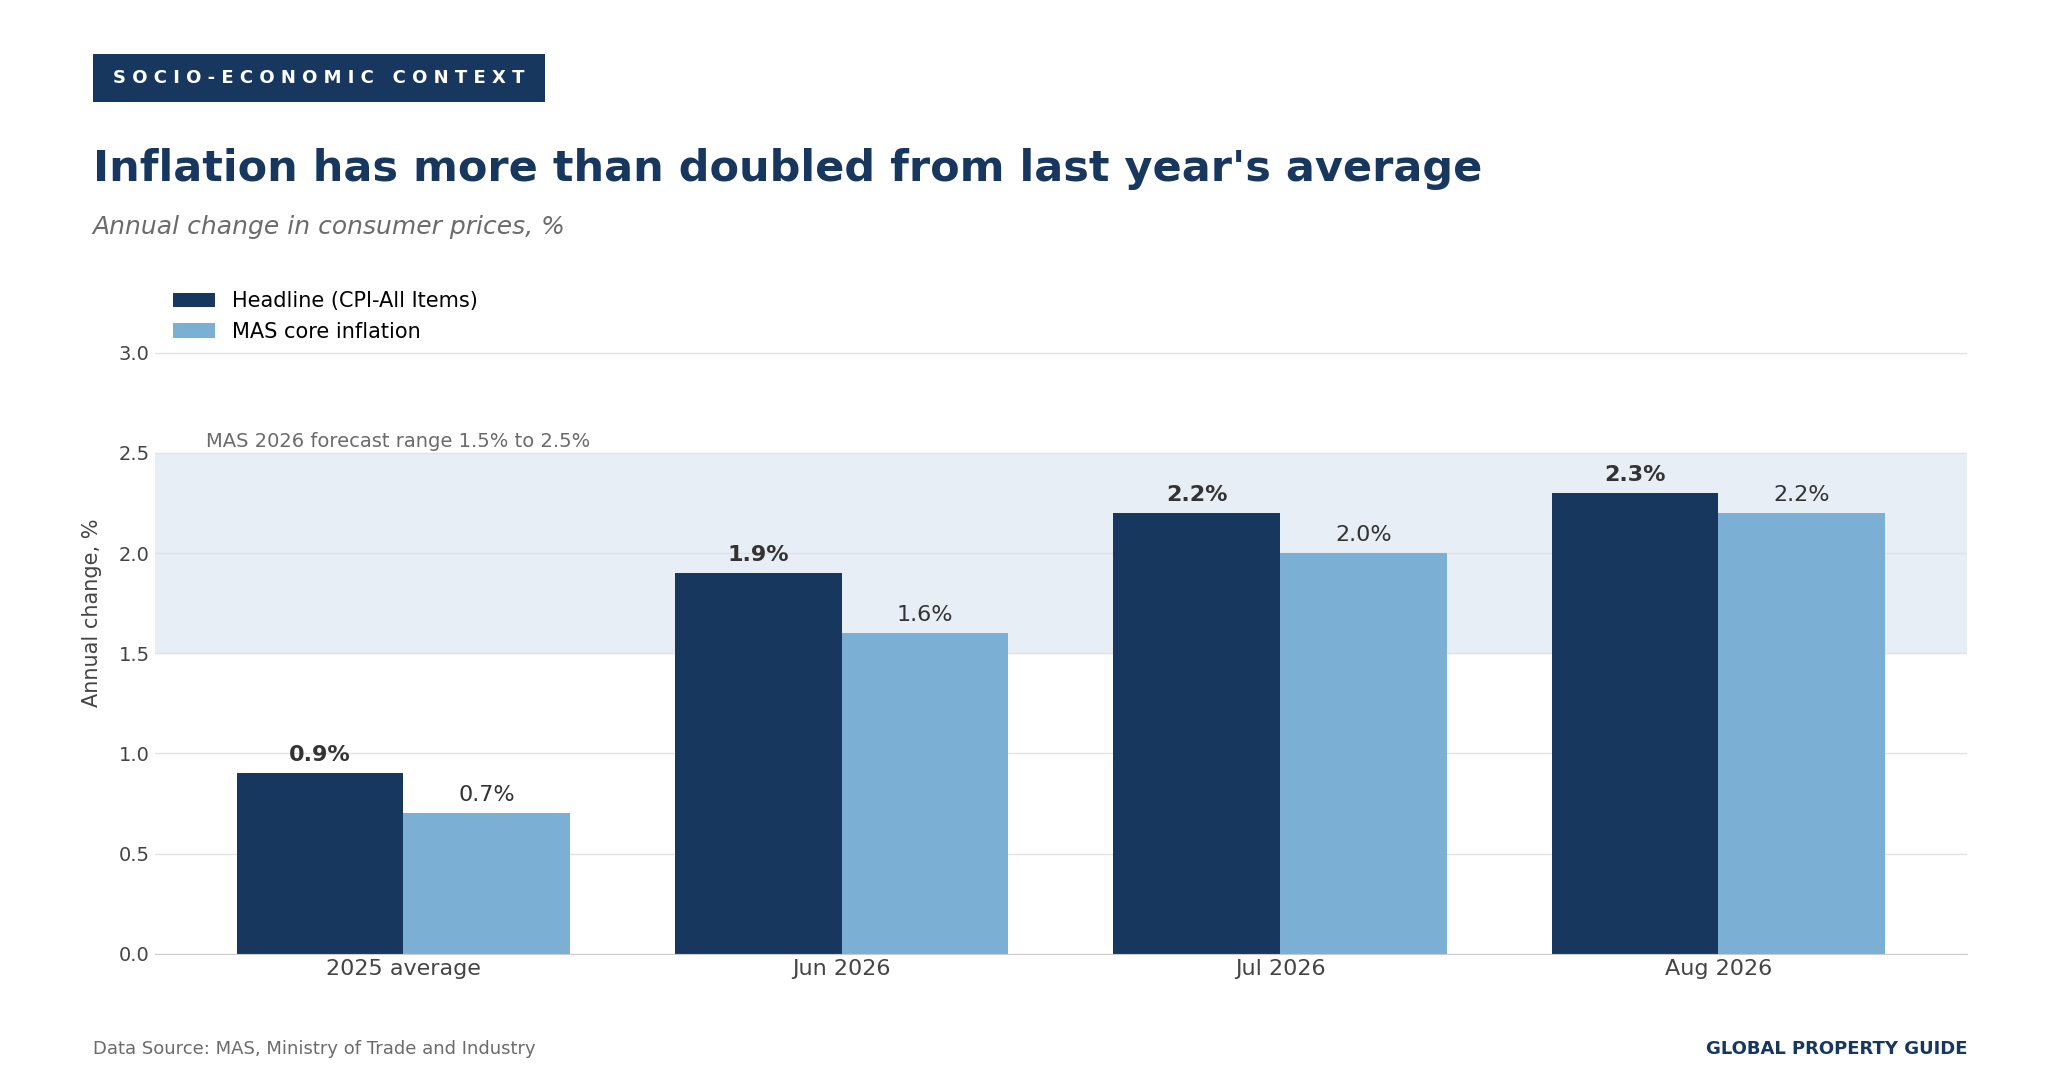
Consumer price inflation has risen steadily. Headline inflation reached 2.3% year-on-year in August 2026 and MAS core inflation 2.2%, its highest level in about two years, up from 0.9% and 0.7% respectively on average in 2025. Electricity and gas prices were 8.7% higher than a year earlier after a July tariff increase. MAS and MTI expect both measures to average 1.5% to 2.5% in 2026, with core inflation remaining elevated into next year before easing from around mid-2027.
The Labour Market Is Showing Signs of Softening
The labour market is weaker than the growth figures suggest. Unemployment remained low in June 2026 at 1.9% overall and 2.9% for residents, but retrenchments rose to 4,620 in Q2 2026 from 3,830 in Q1, the highest since Q4 2020, concentrated in manufacturing, information and communications, and financial services. Job vacancies fell to 68,600 from 73,300 in March, and the share of retrenched residents re-employed within six months dropped from 60.7% to 54.9%. Resident employment grew by just 2,200 in the quarter. The Ministry of Manpower described these as signs of softening.
As of 2025, citizens and permanent residents make up 60.4% of the labour force, with non-resident foreign workers representing the remaining 39.6%. Weaker hiring by outward-oriented firms is the most direct threat to the expatriate rental demand that supports the CCR.
Singapore's fundamental strengths, including high fiscal reserves, budget surpluses and a positive net international investment position, continue to cushion it against external shocks. In April 2026, Fitch Ratings affirmed Singapore's AAA rating with a stable outlook.
Sources:
- Urban Redevelopment Authority (URA)
- Release of 2nd Quarter 2026 Real Estate Statistics: www.ura.gov.sg
- Release of Flash Estimate for 2nd Quarter 2026 Private Residential Property Price Index: www.ura.gov.sg
- Private Housing Supply Under the Government Land Sales Programme Sustained at a High Level in the Second Half of 2026: www.ura.gov.sg
- Number of Unsold Private Residential Units from Projects with Planning Approvals, Q2 2026: isomer-user-content.by.gov.sg
- Number of New Sale, Sub-Sale and Resale Transactions by Market Segment, Q2 2026: isomer-user-content.by.gov.sg
- Housing and Development Board (HDB)
- Resale Price Index from 1st Quarter 1990 to 2nd Quarter 2026: www.hdb.gov.sg
- Flat and Grant Eligibility: www.hdb.gov.sg
- Monetary Authority of Singapore (MAS)
- MAS Monetary Policy Statement, July 2026: www.mas.gov.sg
- Macroeconomic Review, July 2026: www.mas.gov.sg
- Monetary Policy Framework: www.mas.gov.sg
- SORA: www.mas.gov.sg
- Monthly Statistical Bulletin: www.mas.gov.sg
- Ministry of Trade and Industry (MTI)
- MTI Upgrades 2026 GDP Growth Forecast to 4.5 to 5.5 Per Cent: www.mti.gov.sg
- Consumer Price Developments in August 2026: www.mti.gov.sg
- Singapore Department of Statistics (DOS)
- Household Sector Balance Sheet: www.singstat.gov.sg
- Statistics on Resident Households: www.singstat.gov.sg
- Ministry of Manpower
- Labour Force in Singapore 2025: stats.mom.gov.sg
- Inland Revenue Authority of Singapore (IRAS)
- Additional Buyer's Stamp Duty (ABSD): www.iras.gov.sg
- Federal Reserve
- Federal Reserve Issues FOMC Statement, 16 September 2026: federalreserve.gov
- Federal Reserve Issues FOMC Statement, 29 July 2026: www.federalreserve.gov
- Federal Reserve Economic Data (FRED)
- Federal Funds Target Range, Upper Limit: fred.stlouisfed.org
- Global Property Guide
- Gross Rental Yields in Singapore: www.globalpropertyguide.com
- CBRE
- Commentary on the Flash Estimate of Q2 2026 Private Residential Property Price Index: www.cbre.com.sg
- ERA Real Estate
- 2Q 2026 URA Quarterly Report: Resale Transactions Rebound in the Quarter Due to Fewer New Launches: www.era.com.sg
- 2Q 2026 HDB Quarterly Report: HDB Price Moderate for Second Quarter in a Roll: www.era.com.sg
- Realion (OrangeTee and ETC)
- Q2 2026 URA's Data Analysis: www.orangetee.com
- PropNex
- Singapore's Property Market to Remain Buoyant for Rest of 2026: www.homeanddecor.com.sg
- Savills
- Singapore Private Home Leasing Demand Rises 5.1% in Q2 2026: realestateasia.com
- Singapore Private Home Rents Forecast to Remain Flat in 2026: realestateasia.com
- Savills Maintains 3% Singapore Home Price Growth Forecast for 2026: realestateasia.com
- EdgeProp
- Developers' Sales Plunge to 153 Units in August, Down 79% M-o-M and 93% Y-o-Y: sg.news.yahoo.com
- StraitsData
- Singapore Interest Rates, Daily Domestic Interest Rates From MAS: straitsdata.com
- PropertyNet
- Latest Bank Mortgage Loan Rates Across Singapore: propertynet.sg
- The Star
- Singapore Labour Market Expands in Q2 Even as Retrenchments Rise and Job Vacancies Fall: www.thestar.com.my
- Fitch Ratings
- Fitch Affirms Singapore at AAA; Outlook Stable: www.fitchratings.com