Australia's Residential Property Market Analysis 2026
After peaking in March, Australian housing values have fallen for five consecutive months, with the downturn broadening from the premium end of Sydney and Melbourne into almost every capital city suburb as higher borrowing costs and a sweeping change to investment property taxation reshape demand.
This extended overview from Global Property Guide covers key aspects of the Australian housing market and takes a closer look at its most recent developments and long-term trends.
Table of Contents
- Property Prices and Price Index
- Historic Perspective
- Property Demand Trends
- Property Supply Trends
- Rental Market: Rents and Rental Yields
- Mortgage Market and Interest Rates
- Economic and Social Factors
Property Prices and Price Index
Australia's housing market has turned. The national median dwelling value stood at AUD 912,885 (USD 647,896) at the end of August 2026, down 0.9% over the month, according to Cotality's Home Value Index. That was the fifth consecutive monthly decline and left national values 3.6% below the record peak recorded in March 2026, the same month the previous edition of this report was published. Across the combined capitals, the median fell to AUD 990,394 (USD 702,906), 4.6% below its own March peak, while combined regional markets held up better at AUD 764,020 (USD 542,243), down 1.2% from a May peak.
Australia's house price annual change:
The more telling development is how broad the decline has become. Cotality reported that the share of capital city suburbs recording a fall in values more than doubled through winter, from 45.8% in autumn to 93%. Every capital except Darwin declined over the three months to August. Tim Lawless, Cotality's research director, described a shift from concentrated easing at the top of the market to generalised softening, with the vast majority of capital city suburbs now recording some level of decline.
Sydney continues to set the pace. Values fell 1.4% in August and are 7.1% below their February 2026 peak, a faster rate of decline than the 2022-23 correction produced over the equivalent number of months after that peak. Melbourne and Canberra both fell 1.1% over the month, and Brisbane 1.0%. Adelaide and Perth, which led the market through 2025, both fell 0.8%.
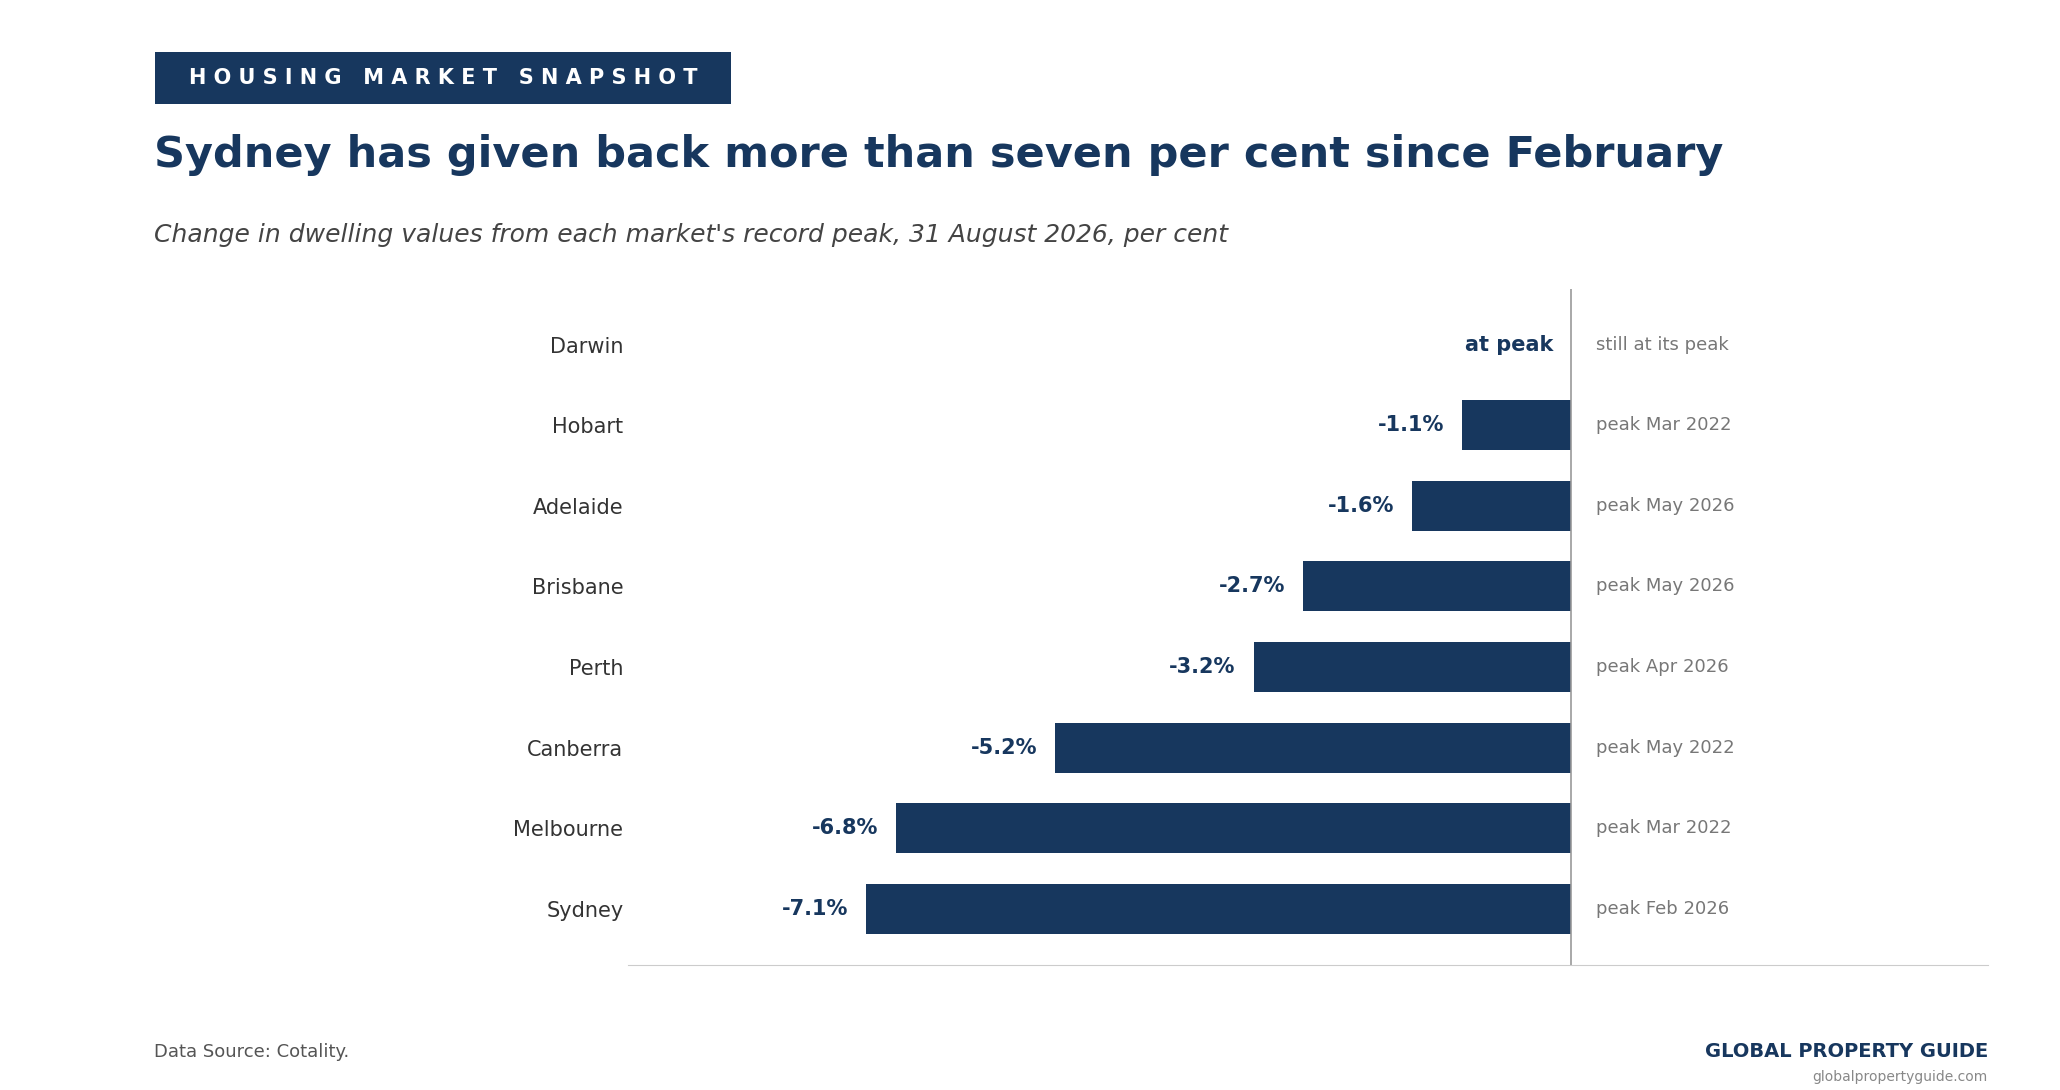
Annual figures still show a divided country, but they are a lagging picture. Perth remains up 15.6% over the year and Darwin 14.6%, while Sydney is down 4.6% and Melbourne 4.7%. The quarterly numbers show the convergence: Sydney down 4.7%, Melbourne 3.9%, Perth 3.2% and Canberra 2.8% over the three months to August.
| Median dwelling values by state and territory capital | |||||
| City | Median Dwelling Value (AUD), Aug 2026 |
Median Dwelling Value (USD), Aug 2026 |
Month, % | Quarter, % | Annual, % |
| Sydney | AUD 1,222,718 | USD 867,791 | -1.4% | -4.7% | -4.6% |
| Melbourne | AUD 786,718 | USD 558,352 | -1.1% | -3.9% | -4.7% |
| Brisbane | AUD 1,080,142 | USD 766,602 | -1.0% | -2.7% | 10.8% |
| Adelaide | AUD 937,207 | USD 665,158 | -0.8% | -1.6% | 8.6% |
| Perth | AUD 999,987 | USD 709,714 | -0.8% | -3.2% | 15.6% |
| Hobart | AUD 752,397 | USD 533,994 | -0.2% | -0.2% | 8.1% |
| Darwin | AUD 647,259 | USD 459,375 | 0.6% | 0.9% | 14.6% |
| Canberra | AUD 864,998 | USD 613,909 | -1.1% | -2.8% | -0.4% |
| Combined capitals | AUD 990,394 | USD 702,906 | -1.1% | -3.7% | 1.1% |
| Combined regional | AUD 764,020 | USD 542,243 | -0.4% | -1.2% | 7.7% |
| Australia | AUD 912,885 | USD 647,896 | -0.9% | -3.1% | 2.7% |
| Note: Exchange rate as of August 2026: USD 1 = AUD 1.4090. | |||||
| Data source: Cotality. | |||||
The composition of the decline has also shifted. Houses fell 1.1% nationally over the month against 0.5% for units, and 3.3% against 2.2% over the quarter. Premium segments still record the weaker results, but Lawless noted that the gap between upper and lower quartiles has narrowed as affordability pressures and softer demand spread more evenly. Lower-priced housing, which was insulated through the first half of the year, is now falling too.
Two forces drive the outlook, and both point down. The Reserve Bank has raised the cash rate three times in 2026, and financial markets attach a 76% probability to a fourth increase at the 29 September meeting. Separately, the May federal budget restricted negative gearing on established residential property and announced the replacement of the 50% capital gains tax discount from July 2027. Commonwealth Bank estimates that the tax package alone leaves prices about 3% lower than they would otherwise have been, and cut its forecast for dwelling price growth to December 2026 to 3% from 5%.
Cotality's own assessment is that the risk profile has shifted firmly to the downside, with sticky inflation, the prospect of higher rates and continued pressure on household budgets likely to keep demand subdued through spring. Offsetting factors remain: new supply is still insufficient relative to underlying demand, unemployment is low by historical standards, and first home buyer incentives continue to support the more affordable end of the market. Together, these should limit the depth of the correction rather than reverse it.
Historic Perspective
Two Decades of Cycles
Australia's housing market has moved through several distinct phases over the past two decades. After a strong upswing ahead of the Global Financial Crisis, prices and transaction activity softened in 2008, although the downturn was relatively modest by international standards. The rebound in 2009 and 2010 was supported by sharp interest rate cuts, improved affordability, and first-home-buyer stimulus. The market then entered a softer phase in 2011 and 2012, with prices broadly stable and building activity subdued. From 2013 to 2017, the cycle turned upward again, supported by very low interest rates and stronger investor demand, particularly in the eastern capitals.
The next downswing, from 2017 to 2019, was driven largely by tighter credit conditions. The Australian Prudential Regulation Authority's lending restrictions on investor and interest-only loans, together with broader tightening in lending standards, helped cool the market. The pandemic then triggered a powerful new upswing, as ultra-low interest rates, the HomeBuilder program, and shifting housing preferences supported demand through 2020 and 2021. That boom reversed in 2022, when the Reserve Bank's rapid tightening cycle reduced borrowing capacity and weighed on prices. From 2023 onward, the market recovered sooner than many had expected, as strong population growth and tight rental conditions met limited new supply, and by 2025 it had shifted into a renewed but supply-constrained recovery.
What Makes This Downturn Different
That recovery ended in March 2026. What distinguishes the current phase from the 2022 correction is its cause. The 2022 downturn was a pure interest rate event. The present one combines a monetary tightening cycle that resumed in February 2026 with a structural change to the tax treatment of residential investment, announced in May and legislating from July 2027. For the first time in the modern cycle, the policy settings that made leveraged residential investment attractive are themselves being withdrawn.
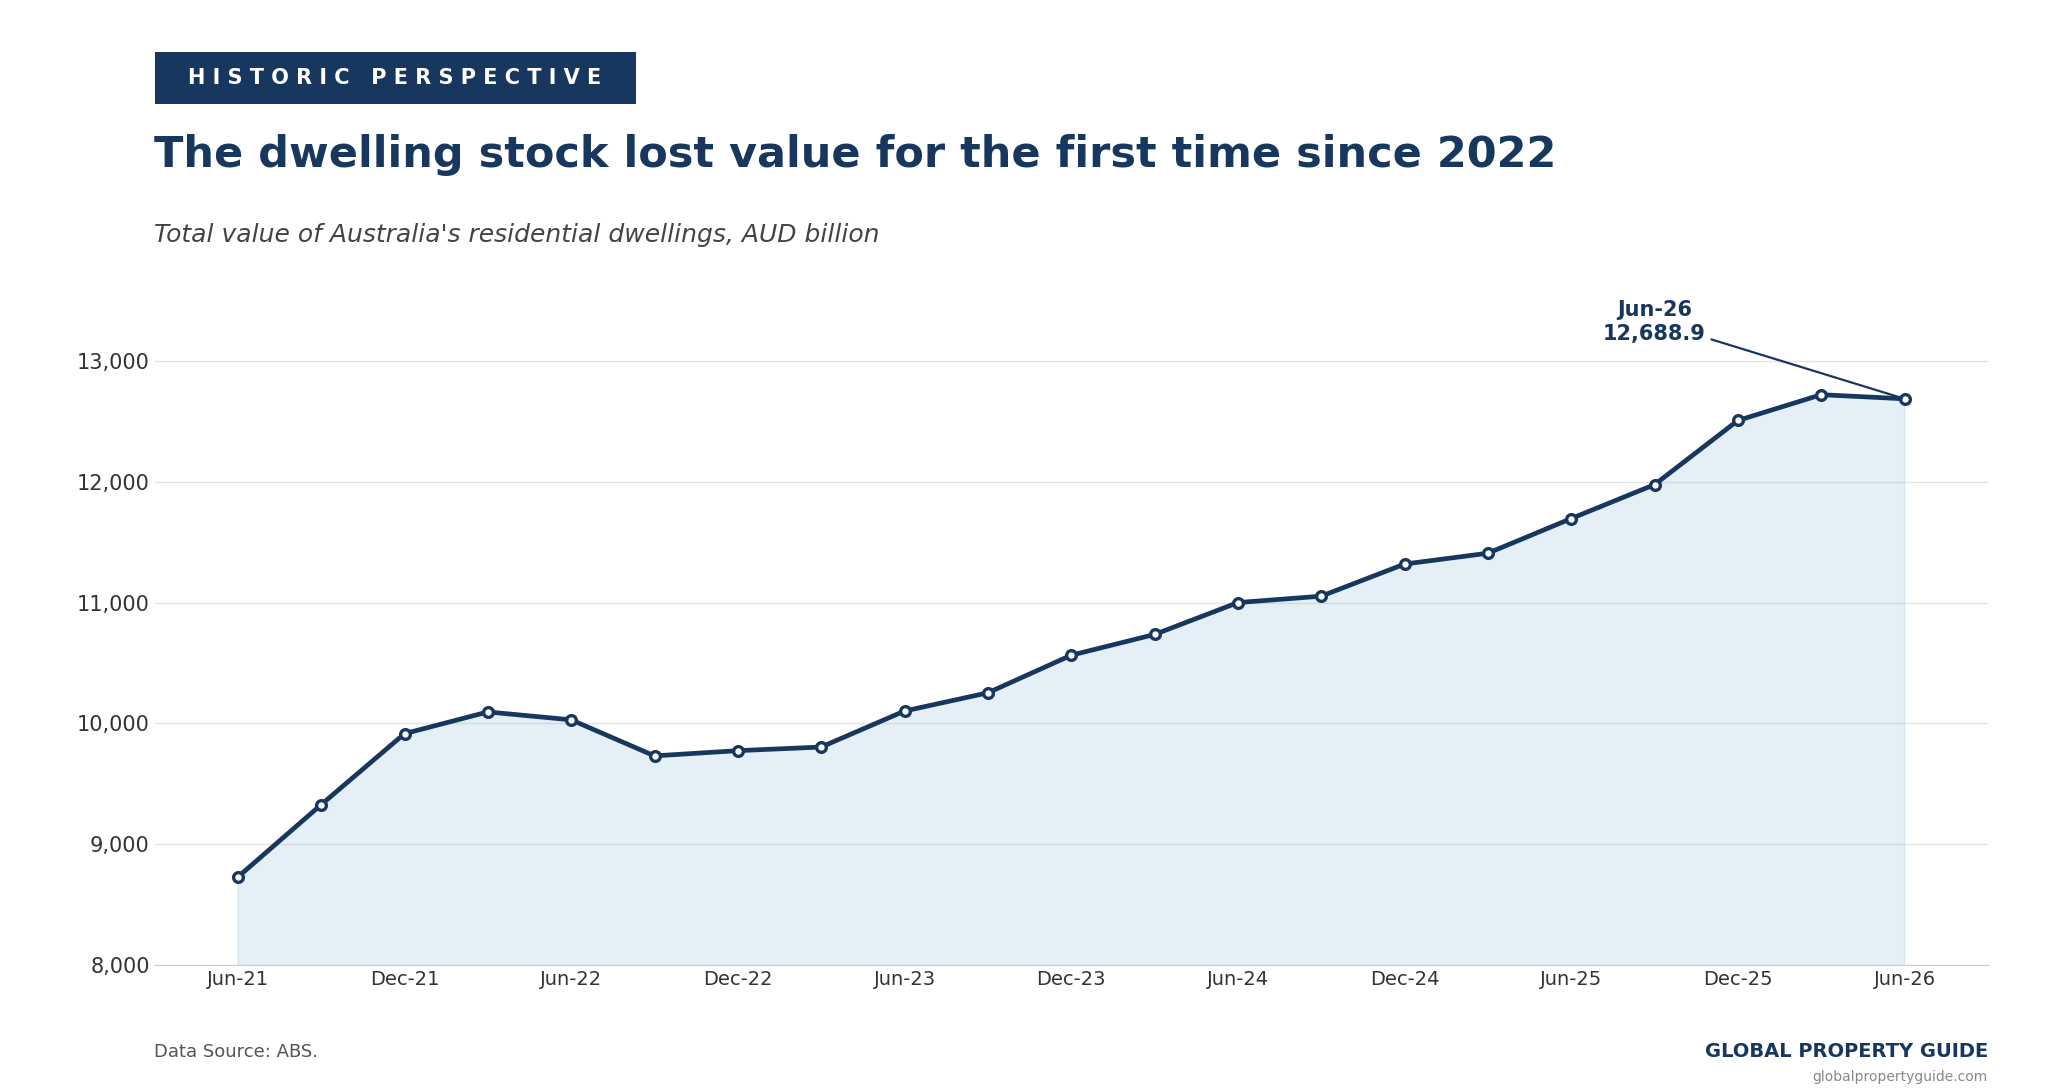
The scale of the asset base involved is substantial. The Australian Bureau of Statistics reported that the total value of Australia's residential dwellings fell by AUD 34.1 billion, or 0.3%, to AUD 12,688.9 billion (USD 9,005.6 billion) in the June quarter 2026. Dr Mish Tan, the ABS head of finance statistics, noted that the value of the dwelling stock fell for the first time since the September quarter 2022. Even after that fall, the stock is 8.5% larger in value than a year earlier, a reminder of how much the market gained before it turned.
Property Demand Trends
Investor Lending Falls Away
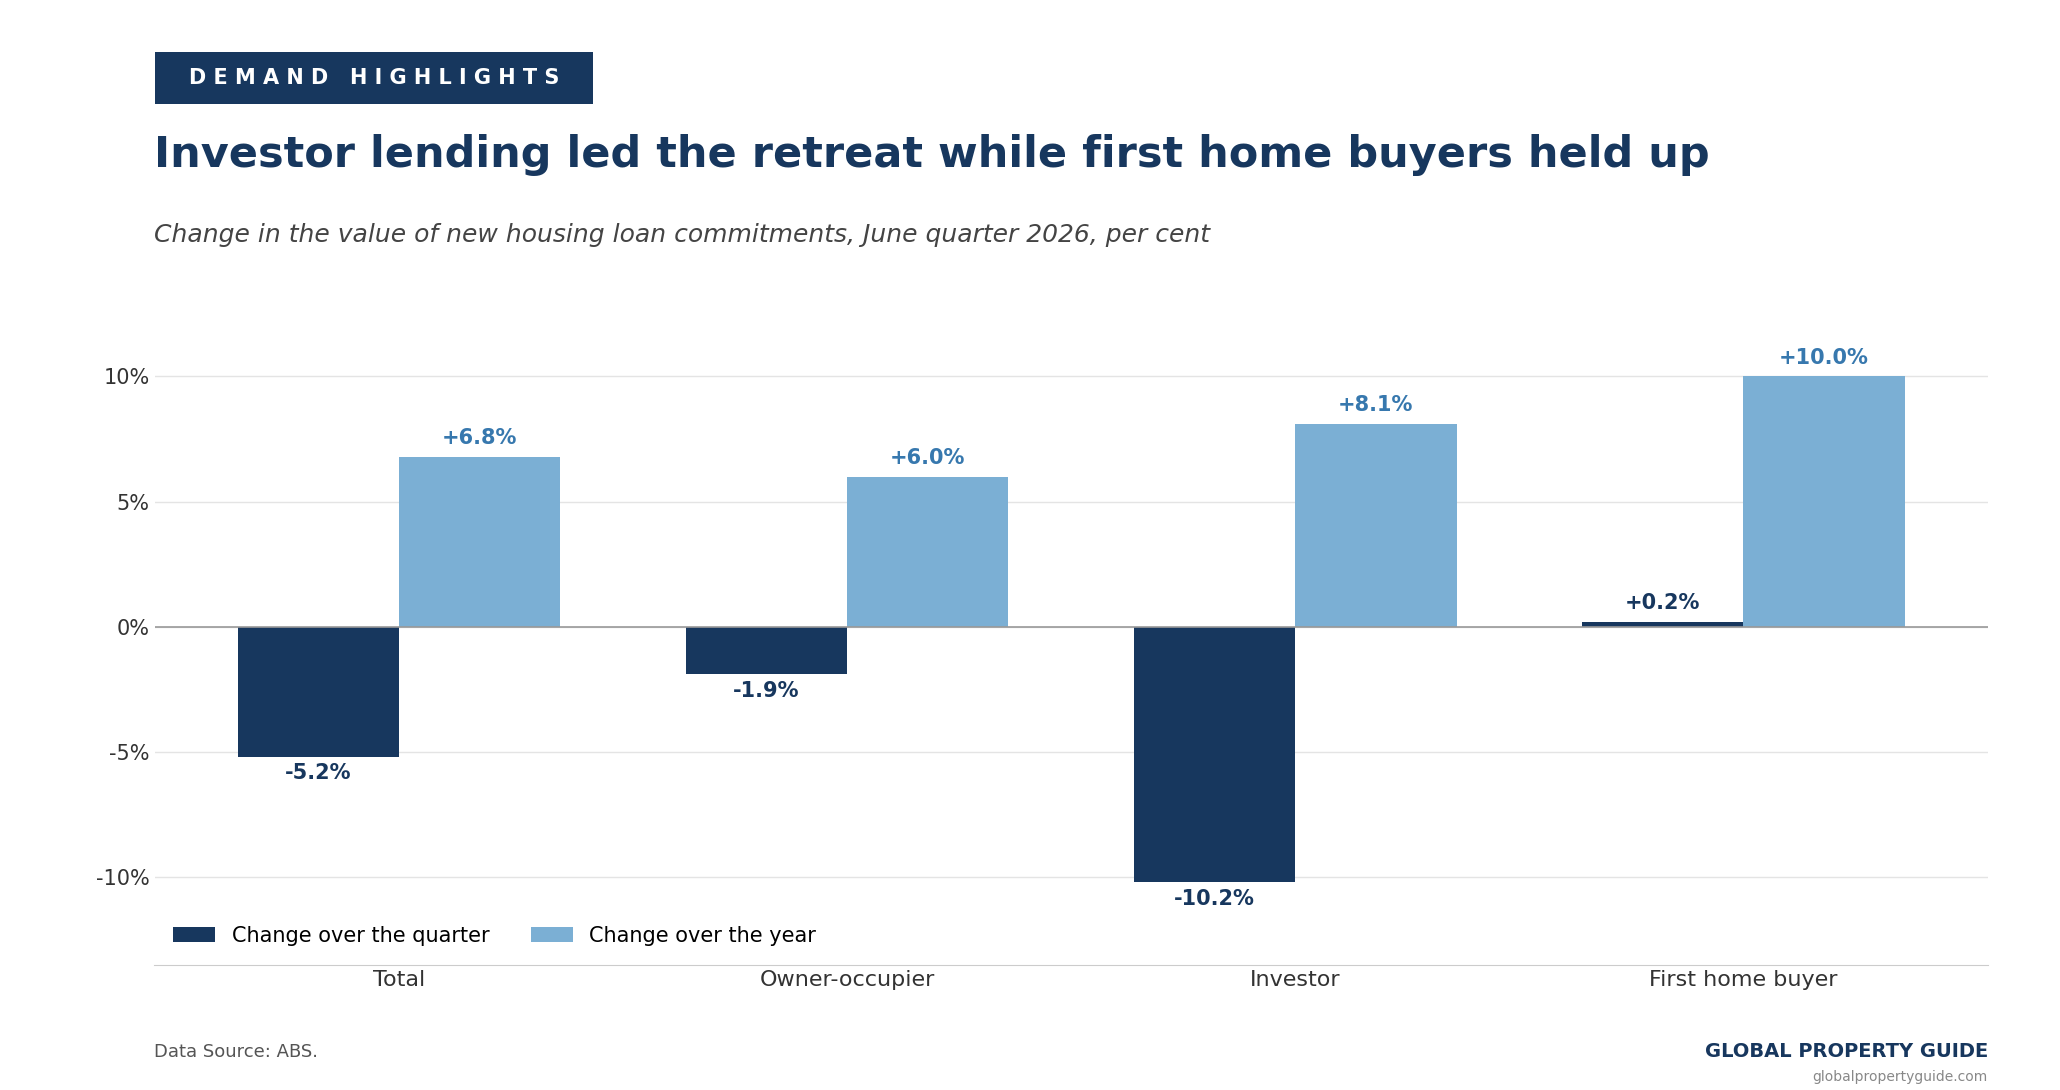
Housing demand weakened sharply through the June quarter, and the retreat was led by investors. According to the ABS, the total number of new loan commitments for dwellings fell 5.4% to 134,225 in the June quarter 2026, while the value fell 5.2% to AUD 97.6 billion (USD 69.3 billion). It was the second consecutive quarterly decline and the largest quarterly fall in value since the September quarter 2020.
The split by borrower type is where the story sits. Investor commitments fell 8.6% in number and 10.2% in value, to AUD 37.1 billion (USD 26.3 billion). Dr Tan noted that the fall in investor loans was the largest since the September quarter 2022, led by New South Wales at 15.5%, Victoria at 14.2% and Queensland at 10.1%, with rises recorded only in the Northern Territory, the Australian Capital Territory and Tasmania. Owner-occupier commitments fell more modestly, by 3.3% in number and 1.9% in value. First home buyers were the one resilient segment: their number fell 2.9% but the value of their commitments rose 0.2% over the quarter and 10.0% over the year.
What the Budget Changed
The May budget is the proximate cause of the investor withdrawal. From 7:30pm AEST on 12 May 2026, purchases of established residential property no longer attract unrestricted negative gearing; from 1 July 2027 investors who bought after that moment will be unable to offset net rental losses against salary or other personal income, and may deduct them only against residential rental income or future capital gains on rental property. Properties held or under contract before the announcement are grandfathered, and newly built dwellings remain exempt, as do investments supporting government affordable-housing programs. Commercial property and other asset classes are unaffected by the negative gearing measure.
The capital gains change is broader. The 50% CGT discount will be replaced from 1 July 2027 with cost base indexation plus a 30% minimum tax on net capital gains, applying across CGT assets held by individuals, trusts and partnerships. Transitional arrangements limit the new regime to gains arising on or after that date, the main residence exemption is untouched, income support recipients are exempt from the minimum tax, and investors in new residential property may elect between the old and new regimes on disposal. The government expects the package to move roughly 75,000 properties from investors to owner-occupiers over a decade.
Transactions, Listings and Prices
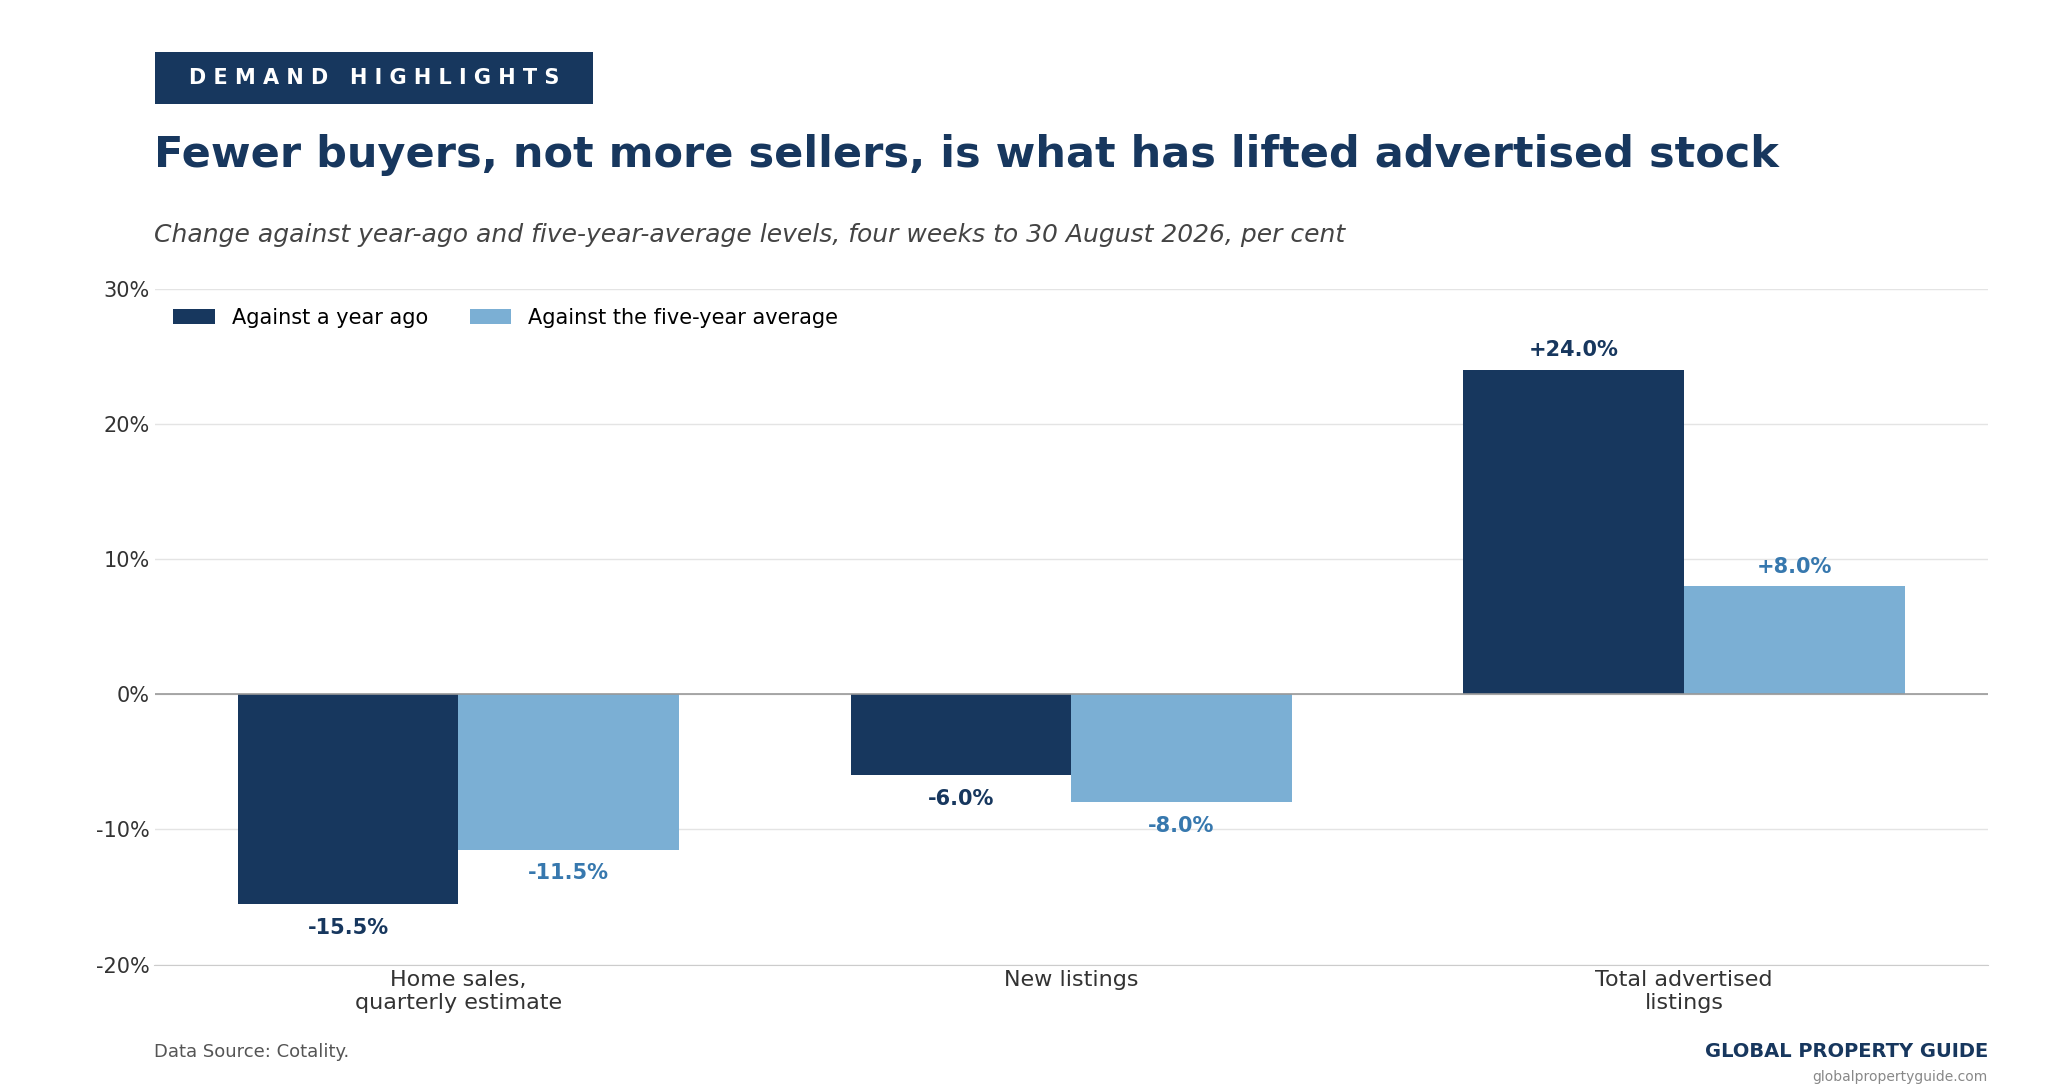
Transaction activity has fallen further than lending. Cotality's quarterly estimate of home sales is tracking 15.5% below the same period last year and 11.5% below the five-year average, with Brisbane, Perth and Sydney all down more than 20%. The consequence is visible in advertised stock: over the four weeks to 30 August, capital city listings were 24% higher than a year earlier and 8% above the five-year average, even though the flow of new listings was 6% lower than a year ago and 8% below average. As Lawless put it, higher advertised stock is a function of a slower rate of absorption rather than a wave of new sellers.
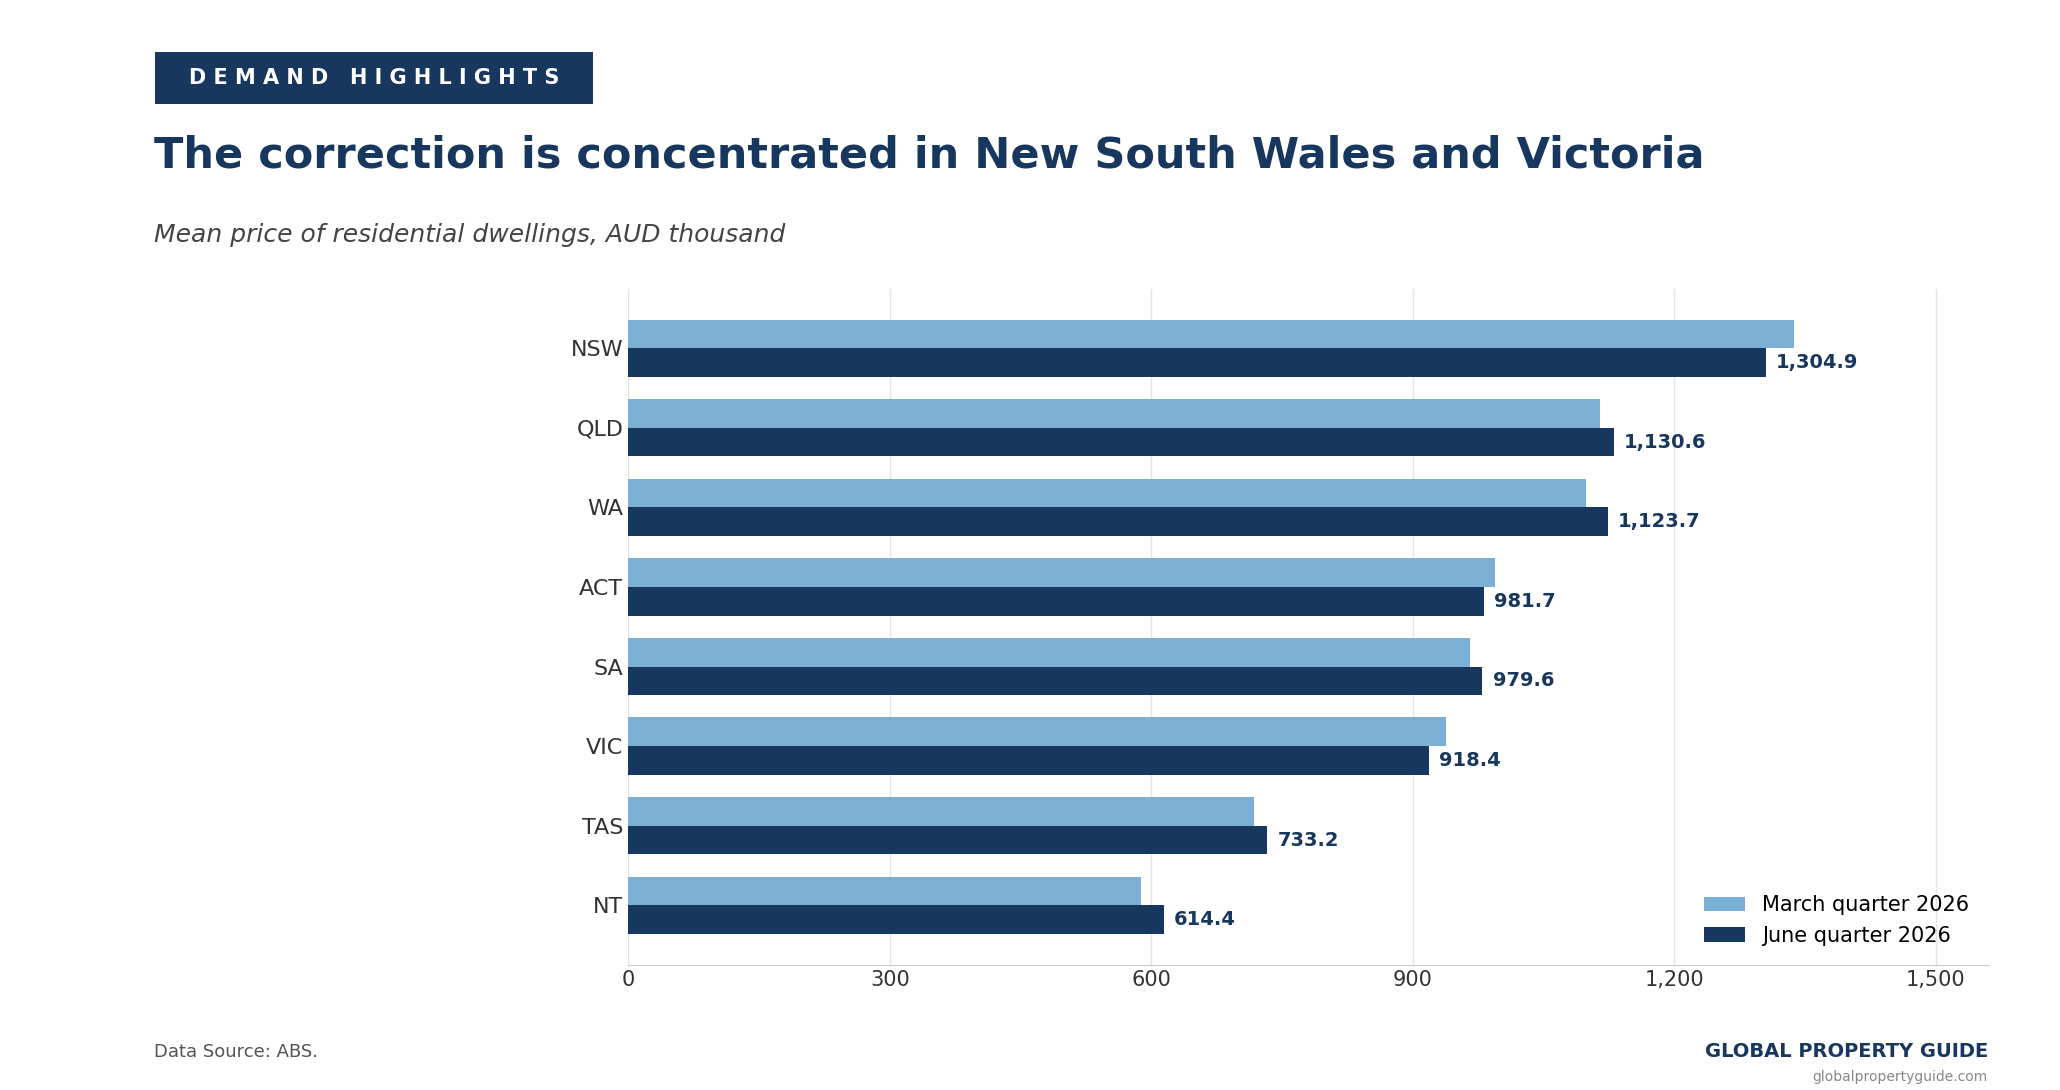
The price consequences are already in the official statistics. The ABS mean dwelling price fell AUD 8,200, or 0.7%, to AUD 1,100,400 (USD 780,979) in the June quarter. The mean fell in New South Wales by 2.4%, Victoria by 2.1% and the Australian Capital Territory by 1.3%, and rose in every other state and territory, with Queensland at AUD 1,130,600 and Western Australia at AUD 1,123,700 now sitting second and third behind New South Wales.
Foreign Buyers
Foreign demand remains a small and constrained component. From 1 April 2025 to 31 March 2027, foreign persons, including temporary residents and foreign-owned companies, are generally banned from purchasing established dwellings unless an exemption applies, with investment still permitted in new housing and in cases that materially add to supply. Doubled vacancy fees apply to foreign-owned residential properties left vacant for more than 183 days in a vacancy year, and enforcement against land banking has been strengthened.
Property Supply Trends
Approvals Reach a Five-Year High
The supply pipeline is the one part of the market that improved over the past year. In original terms, 205,249 dwellings were approved across 2025-26, a 9.2% increase on the 187,944 approved the previous financial year and the highest level since 2020-21. Private sector houses reached their highest level since 2021-22, and private dwellings excluding houses reached their highest since 2017-18.
Momentum cooled at the start of the new financial year. Total dwellings approved fell 3.6% in July to 17,687 in seasonally adjusted terms, with private sector house approvals down 4.2% to 10,199 and private dwellings excluding houses down 0.4% to 7,119. Both series remain well above year-ago levels, at 6.0% and 19.9% respectively, and the Housing Industry Association noted that approvals over the three months to July were 8.3% higher than a year earlier.
Completions Have Not Followed
Approvals, however, are not completions. ABS Building Activity data for the March quarter 2026, the most recent available, showed total dwellings completed down 0.4% to 43,816, with new house completions down 0.6% to 26,201, and commencements falling over the quarter. The gap between a strengthening approvals pipeline and flat delivery remains the central supply problem.
The Accord Shortfall
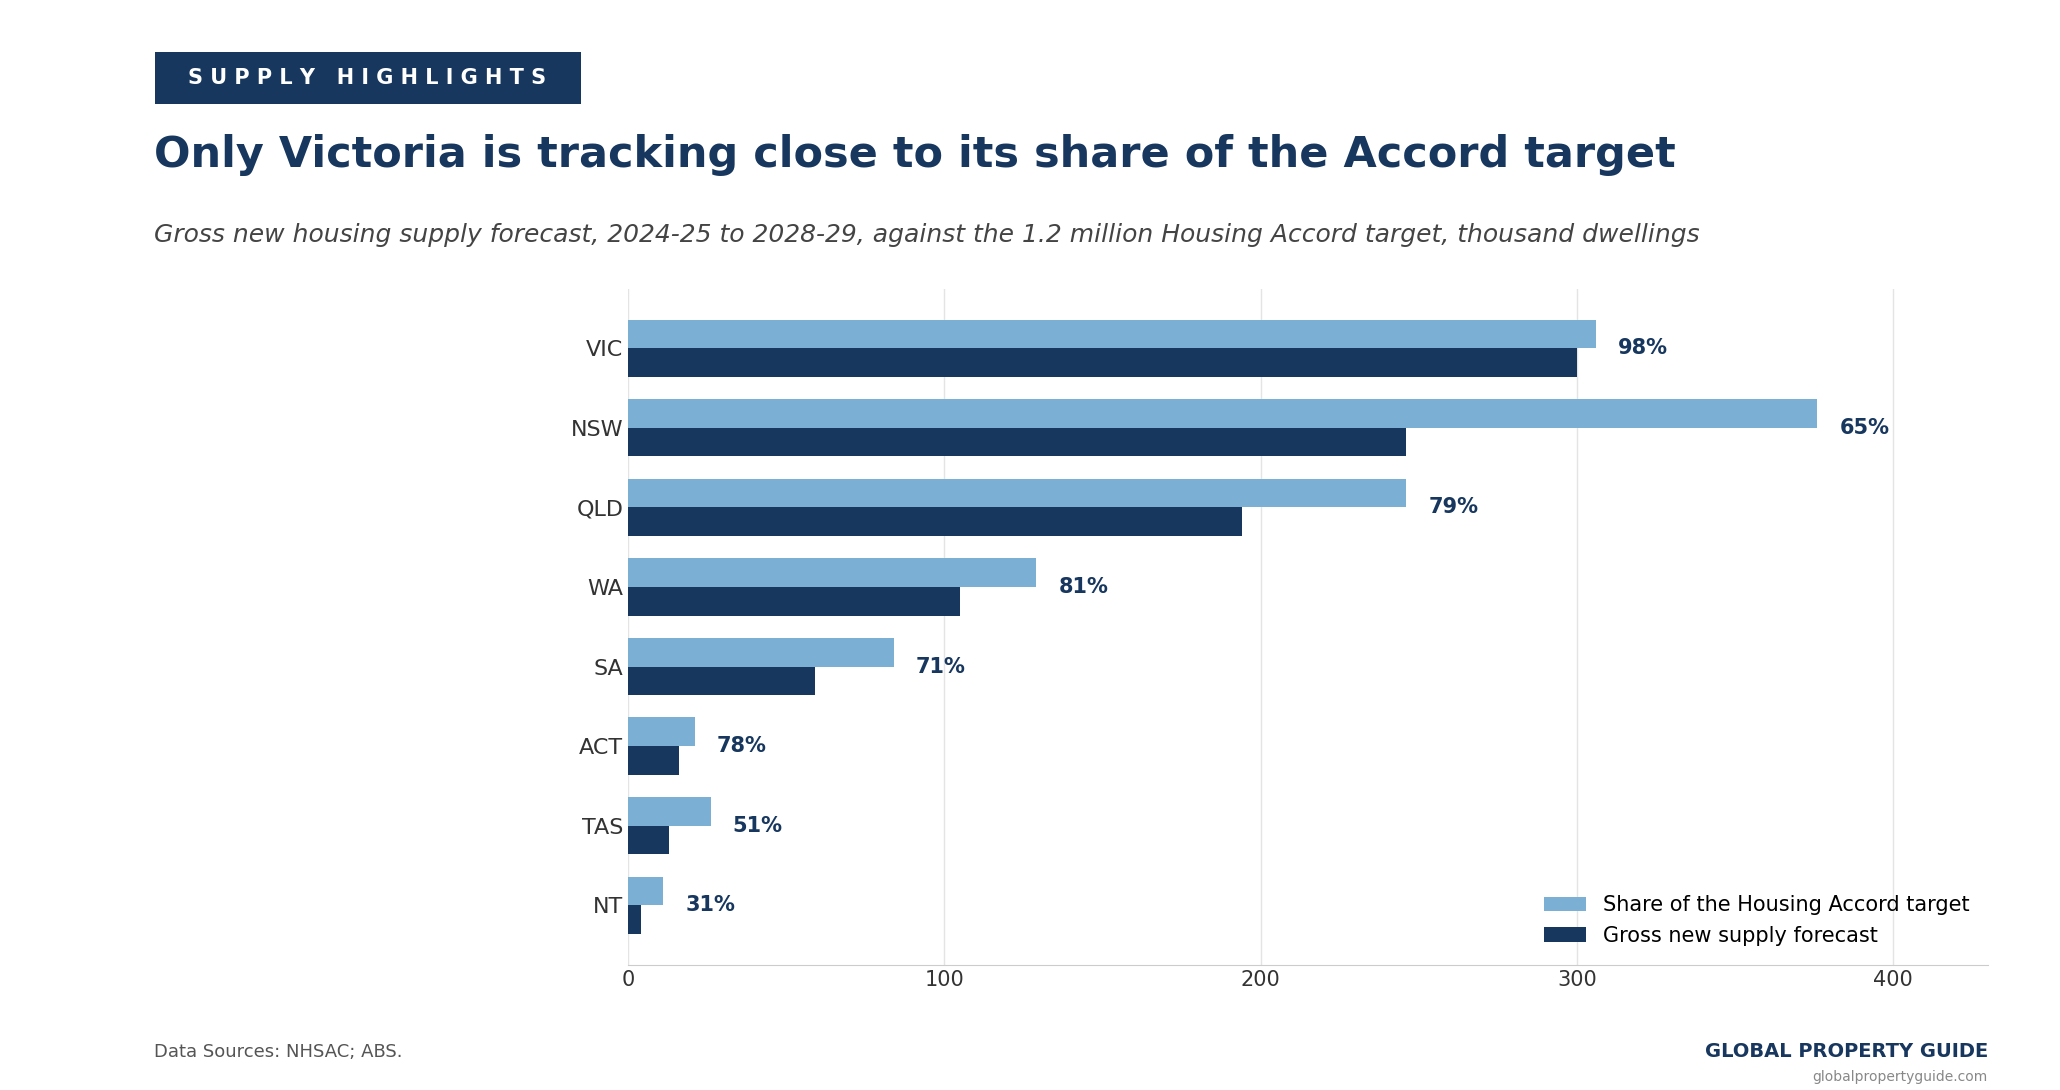
The National Housing Supply and Affordability Council continues to project that total output over the five-year Housing Accord period will reach 938,000 dwellings, falling short of the 1.2 million target by approximately 262,000 units. Only Victoria is tracking close to its population-implied share, at 98%, while the Northern Territory at 31% and Tasmania at 51% are furthest behind.
Cotality expects elevated construction costs, capacity constraints and feasibility challenges to keep a material lift in completions out of reach in the near term. That constraint is now working in an unusual direction. In a rising market, tight supply amplifies price growth; in the current one, it is one of the few factors limiting the depth of the correction.
A second supply-side effect is likely to emerge from the tax changes. Because negative gearing remains available on newly built dwellings while it is withdrawn on established ones, the package creates a deliberate incentive to direct investor capital toward new construction. Whether that shift materialises at scale before the July 2027 start date is among the more consequential open questions for the market.
Rental Market: Rents and Rental Yields
Rents Accelerate as Vacancy Stays Tight
Rental conditions remain tight, and rents have continued to accelerate even as values fall. Cotality's Rental Review for the June quarter 2026 recorded a national median weekly rent of AUD 705 (USD 500), up 1.6% over the quarter and 5.9% over the year, an acceleration from 5.7% in the March quarter and 3.4% at the cyclical low in mid-2025. The national vacancy rate stood at 1.6% in June, with every capital city below 2.0%.
Australia's rent price index:
The geography of rental growth has inverted alongside the sales market. Capital city rents rose faster than regional ones over the quarter, reversing the regional outperformance that ran from late 2024 into early 2026, which Cotality attributes to regional markets hitting affordability ceilings. Sydney remains the most expensive capital, but Perth at AUD 784 and Brisbane at AUD 734 have narrowed the gap substantially, and Darwin now records the fourth-highest median rent of any capital despite having the lowest home values on the mainland.
| Median weekly rent by submarket | ||||
| City | Median Weekly Rent (AUD), Jun 2026 |
Median Weekly Rent (USD), Jun 2026 |
Annual change, % | Vacancy rate, % |
| Sydney | AUD 841 | USD 597 | 5.9% | 1.9% |
| Perth | AUD 784 | USD 556 | 7.8% | 1.3% |
| Brisbane | AUD 734 | USD 521 | 6.4% | 1.9% |
| Darwin | AUD 725 | USD 515 | 10.1% | 1.3% |
| Canberra | AUD 706 | USD 501 | 3.2% | 1.7% |
| Adelaide | AUD 662 | USD 470 | 4.8% | 1.0% |
| Melbourne | AUD 641 | USD 455 | 4.9% | 1.3% |
| Hobart | AUD 632 | USD 449 | 8.6% | 1.9% |
| Combined capitals | AUD 739 | USD 524 | 6.0% | 1.6% |
| Australia | AUD 705 | USD 500 | 5.9% | 1.6% |
| Data source: Cotality. | ||||
By August the picture had softened slightly at the margin. The national vacancy rate rose to 1.9%, its highest since January 2025 and up from the record low of 1.5% recorded in February 2026, though still well below the pre-COVID decade average of 3.3%. Rents were up 5.7% over the twelve months to August, adding roughly AUD 38 to the national median weekly rent. Over five years, rents have risen 39%, leaving tenants paying around AUD 200 more per week than in 2021. Perth has seen the largest five-year increase at 56%, about AUD 283 per week.
Two Measures of Rental Inflation
Two measures of rental inflation are worth distinguishing. The ABS rents series within the consumer price index rose 3.6% over the year to July 2026, well below Cotality's 5.9%. The gap is methodological rather than contradictory: the CPI prices the entire stock of tenancies, including sitting tenants whose rents reset infrequently, while Cotality tracks advertised rents on properties coming to market. The CPI figure describes what renters are paying on average; the Cotality figure describes what a renter moving today would face.
Yields Turn Higher
The combination of rising rents and falling values has pushed yields up. Cotality's national gross rental yield reached 3.79% in August, its highest since September 2019. Research carried out by Global Property Guide in August 2026 found gross rental yields on Australian apartments at an average of 4.94%, up from 4.69% in the February 2026 round and reversing two consecutive declines. Darwin recorded the highest average yield at 6.46%, followed by Melbourne at 5.78% and Canberra at 5.54%, while Brisbane was lowest at 3.73%.
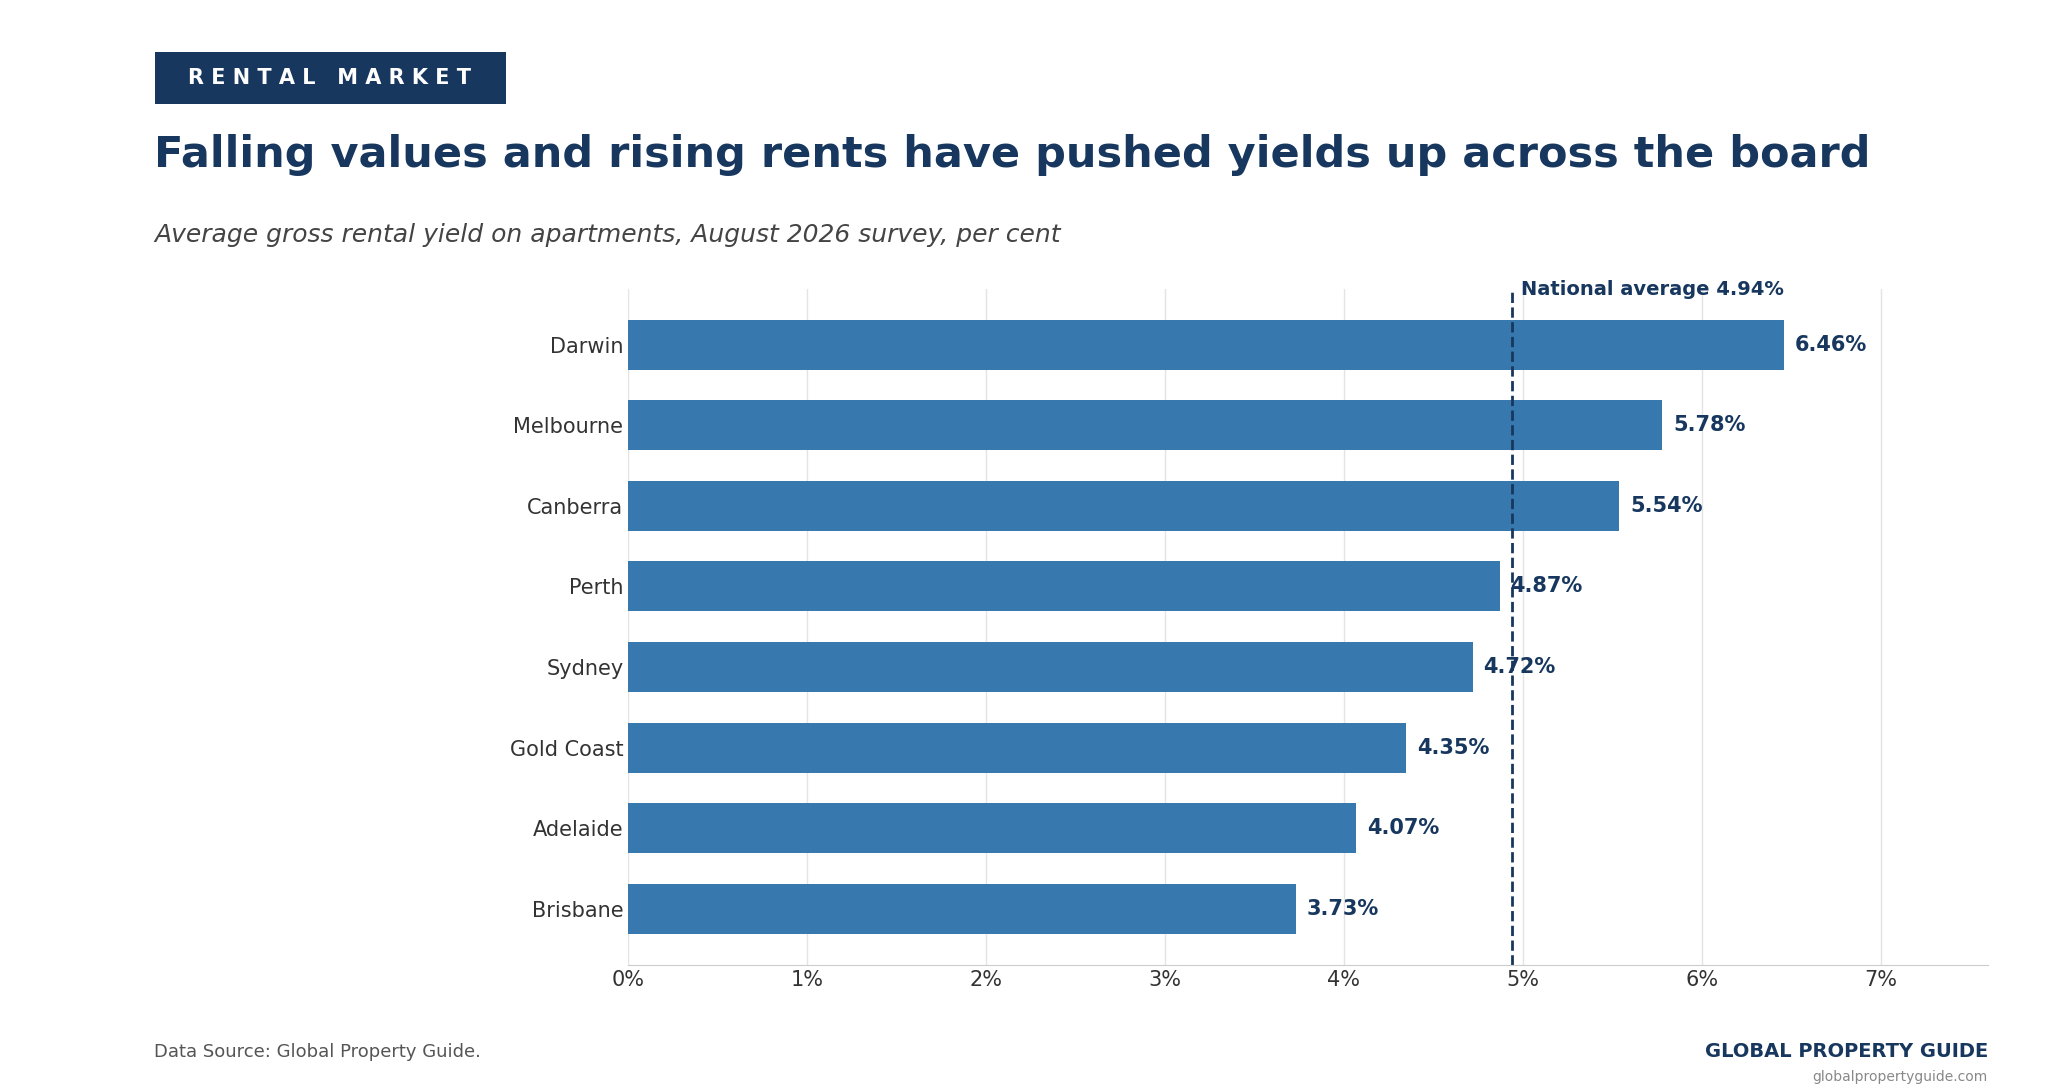
The tax changes are expected to make yield matter more to investors than it did before. Lawless observed that investors are likely to place greater emphasis on higher-yielding opportunities than they did before 12 May, while cautioning that yields would need to rise substantially before rental income offsets holding costs while interest rates remain elevated. He also noted that record rental unaffordability may itself constrain how much further rents can rise. Wage growth provides the ceiling: the ABS Wage Price Index rose 3.2% over the year to the June quarter 2026, 2.7 percentage points below Cotality's rental growth rate.
Mortgage Market and Interest Rates
Three Hikes Delivered
The Reserve Bank has raised the cash rate three times in 2026, taking it from 3.60% to 4.35%. The tightening began in February, continued in March, and concluded with a 25 basis point increase on 5 May that the Monetary Policy Board carried by majority, eight members to one. The Board has since held rates at its June and August meetings while assessing the effect of the increases already delivered.
Australia's mortgage loan interest rates:
The previous edition of this report noted that bank economists expected at least one more hike after February. Two followed.
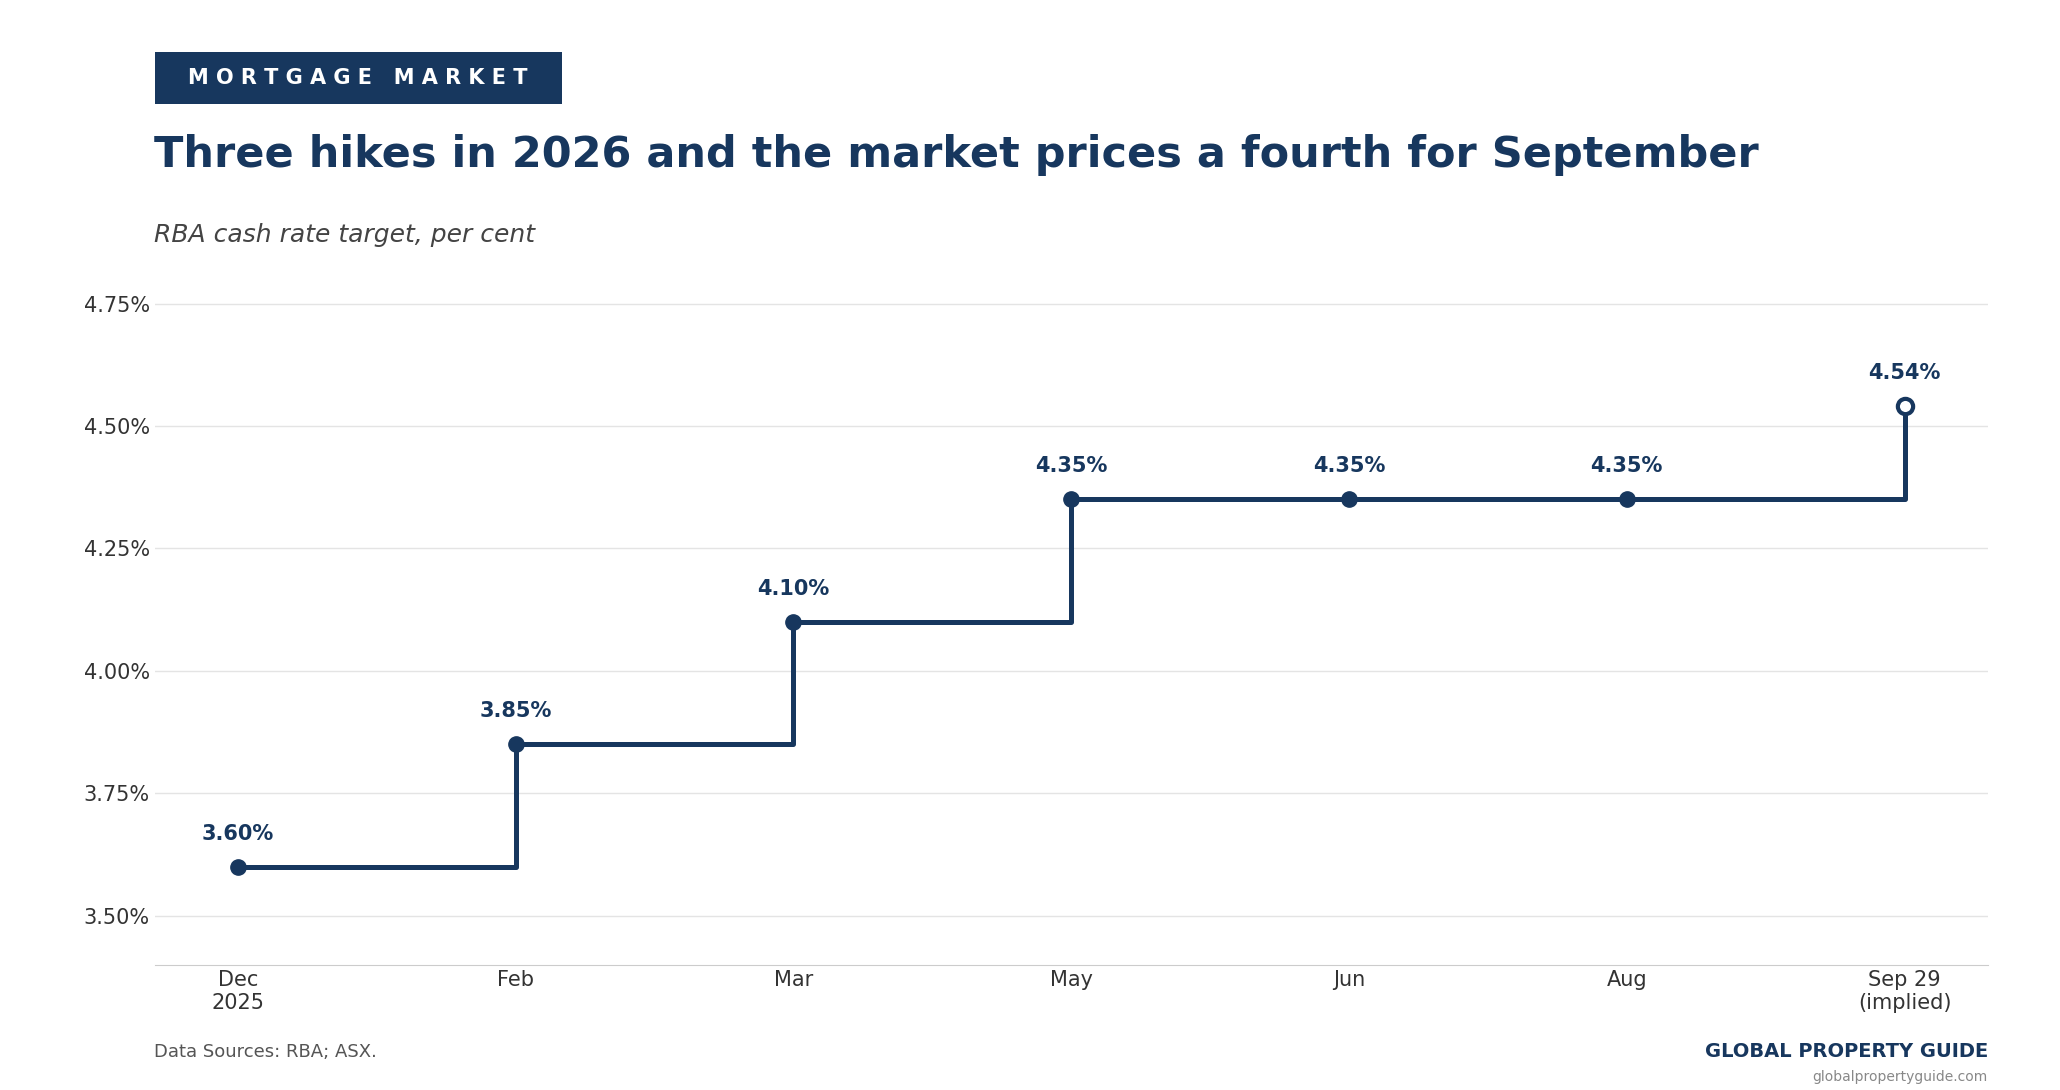
The next decision falls on 29 September. As at 14 September, ASX futures implied a 76% probability of a further 25 basis point increase to 4.60%, with the market pricing that level as reached by the November meeting in either case. Forecasts are split: National Australia Bank expects a move in September, Commonwealth Bank and ANZ in November, and Westpac no further increase this year. Governor Michele Bullock has said the Board is prepared to act as required, including by increasing the cash rate further if needed. All mortgage market figures in this section predate that decision.
Borrowing Costs and Household Stress
Borrowing costs have moved with the cash rate. Average interest rates on new housing loans reached approximately 6.25% for owner-occupiers and 6.4% for investors by mid-2026, according to Reserve Bank lending rate data, against 5.50% and 5.66% respectively in January 2026. Fixed rates of three years or less have run marginally below variable rates, with the gap narrow enough that the choice turns on flexibility rather than price.
The pressure on existing borrowers is measurable. Roy Morgan classified 32.5% of Australian owner-occupier mortgage holders, roughly 1,786,000 people, as at risk of mortgage stress in July 2026. That is an 18-year high and the sixth consecutive monthly increase.
The Credit Stock
The stock of housing debt continues to grow, but growth is decelerating, and the composition is shifting. Reserve Bank financial aggregates put total outstanding housing credit at AUD 2.633 trillion (USD 1.869 trillion) in July 2026, up 0.5% over the month and 7.4% over the year, the slowest annual pace since March 2026. Owner-occupier credit of AUD 1.765 trillion grew 6.1% over the year and investor credit of AUD 868.5 billion grew 10.1%, down from 10.4% the previous month and the slowest monthly pace since October 2024. Owner-occupiers hold 67.0% of the stock and investors 33.0%.
The deceleration in investor credit is the clearest evidence that the tax changes are transmitting into the credit aggregates rather than remaining a sentiment story. Westpac attributed the moderation to higher interest rates, lower house prices and, most importantly, the tax changes for investment properties, noting that the divergence between owner-occupier and investor growth indicates the policy is having a more immediate effect on investment decisions.
Whether the market absorbs a fourth rate rise without a sharper price adjustment is the central question for the remainder of 2026. Cotality warns that a further increase would be challenging against a backdrop of elevated household debt, reducing borrowing capacity further, adding to repayment pressures and weighing on consumer confidence.
Economic and Social Factors
Growth Slows
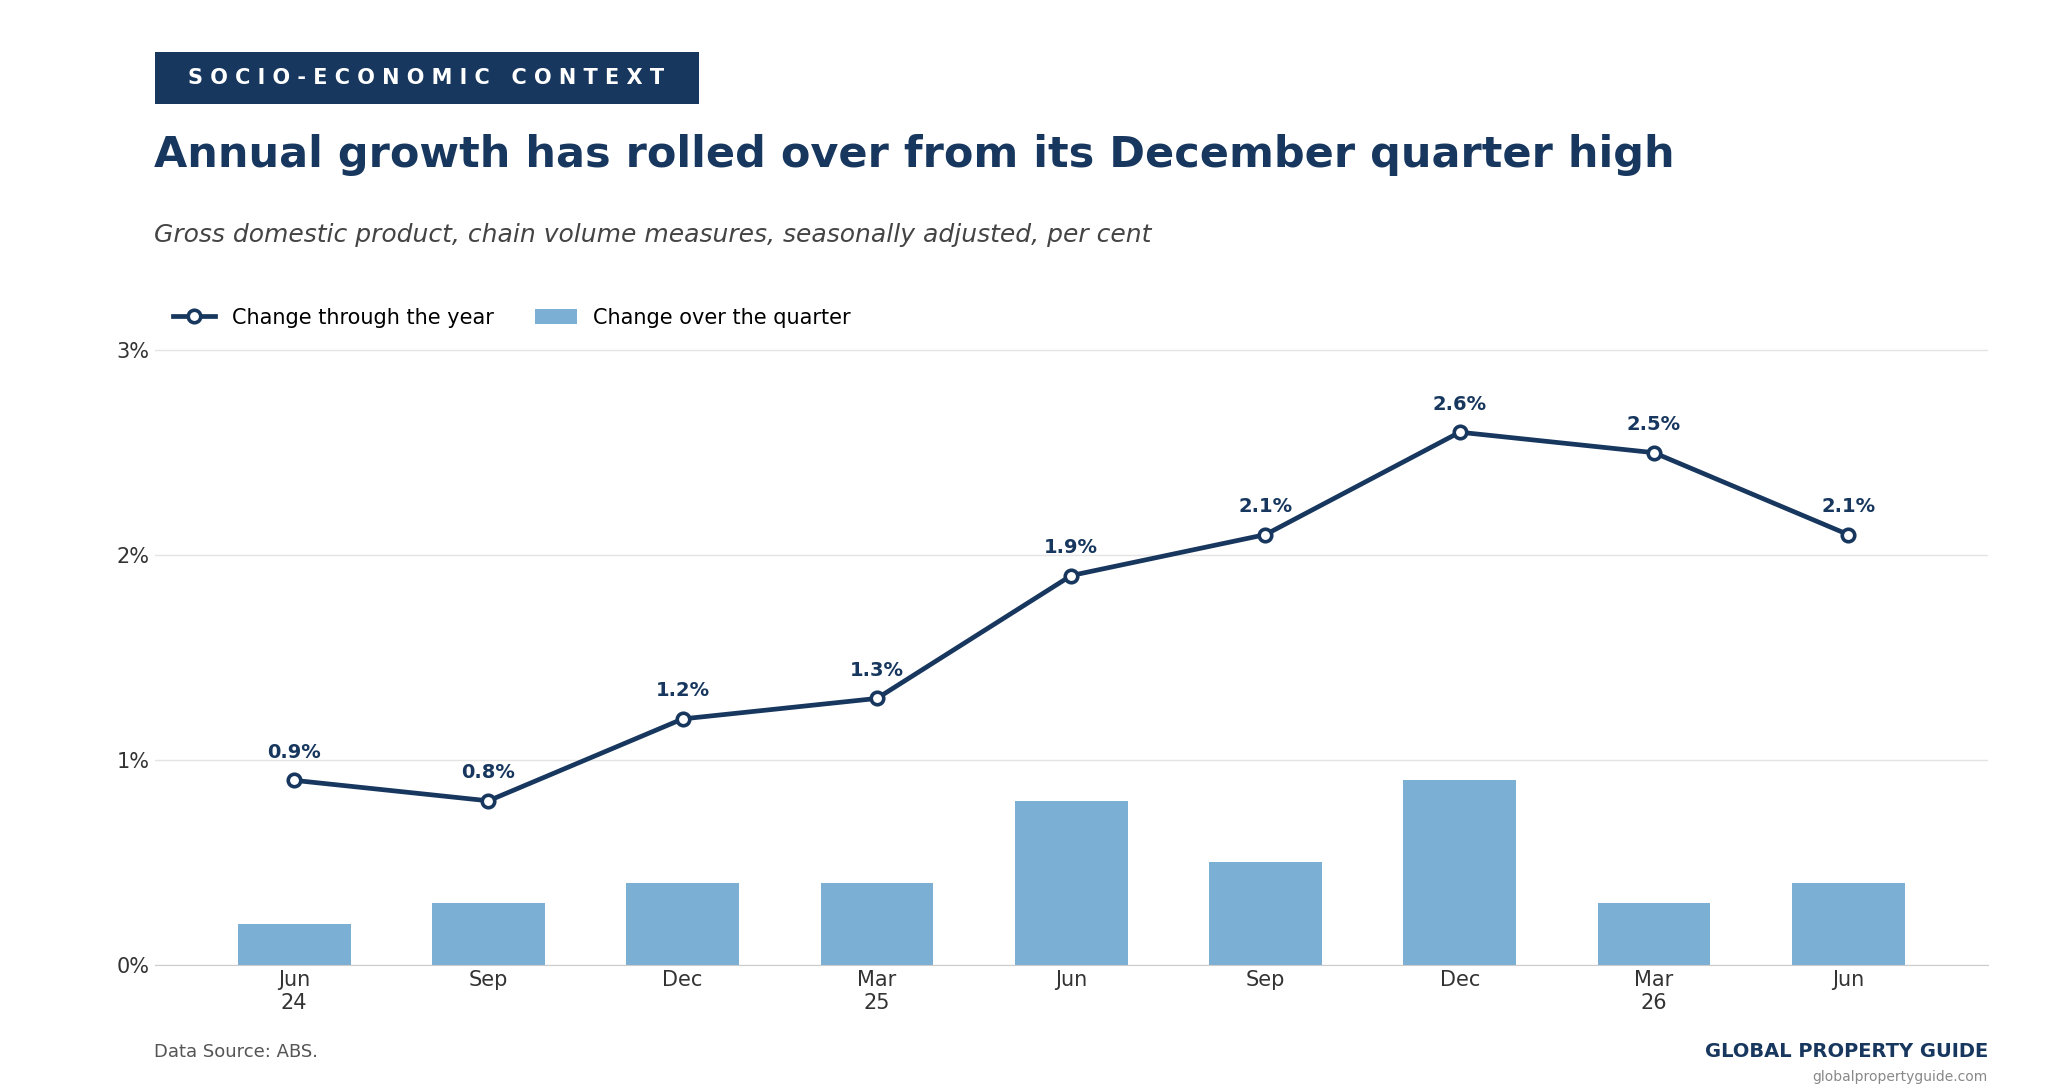
The Australian economy is decelerating. Gross domestic product rose 0.4% in the June quarter 2026 and 2.1% through the year in seasonally adjusted chain volume terms, with growth of 2.4% across the 2025-26 financial year. Grace Kim, the ABS head of National Accounts, described growth as remaining subdued as households continued to behave cautiously, with imports servicing much of the increase in private demand. Annual growth has slowed from 2.6% at the end of 2025, and the household saving ratio rose to 6.5%.
The International Monetary Fund cut its Australian growth forecast in the July 2026 World Economic Outlook Update to 1.9% for 2026 from 2.0% in April and 2.1% in January, and to 1.7% for 2027 from 2.2%. The downgrade reflects persistent inflation and the demand cooling required to return the economy to balance.
Inflation Stays Above the Band
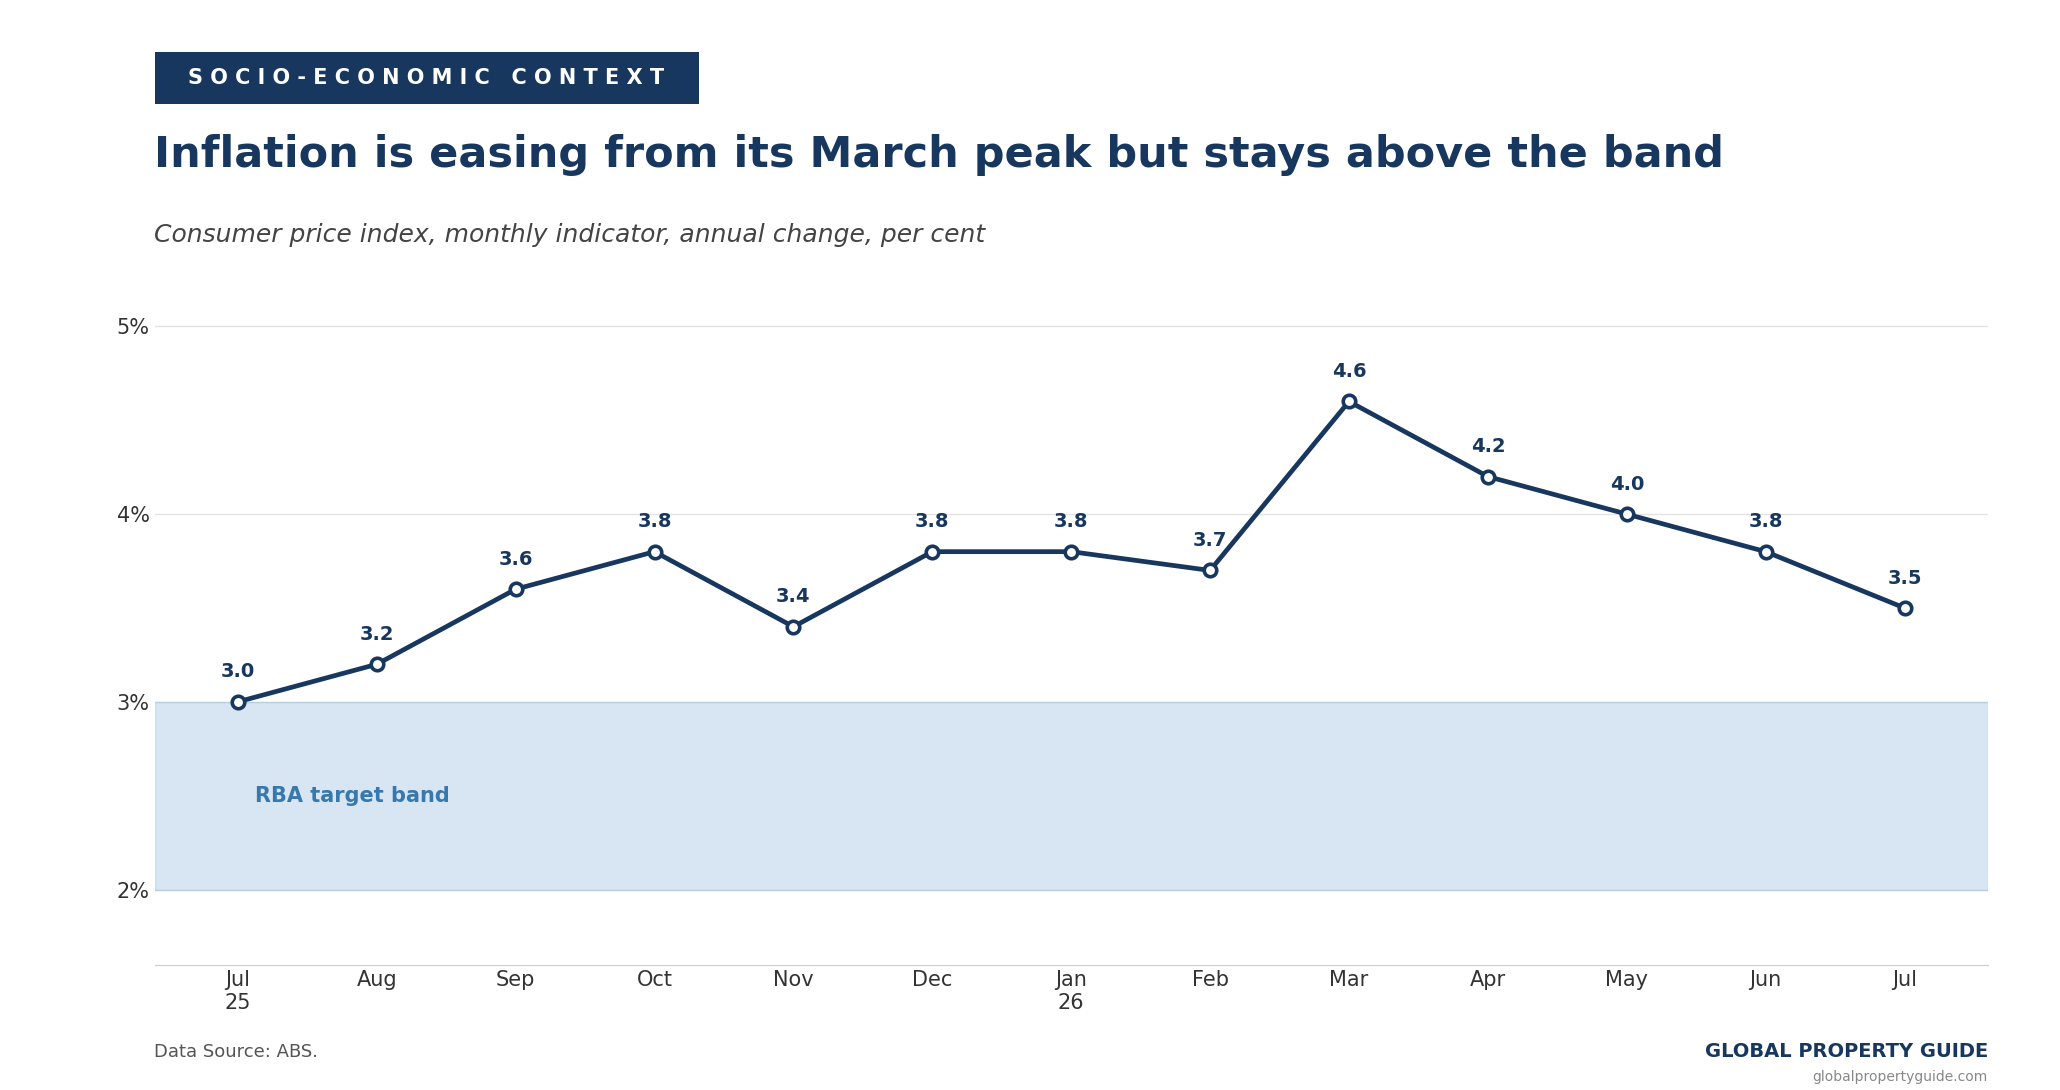
Inflation remains the binding constraint. The consumer price index rose 3.5% over the twelve months to July 2026, down from 3.8% in the year to June and from a March peak of 4.6%, but still above the Reserve Bank's 2% to 3% target band. Trimmed mean inflation held at 3.6% through the June quarter. Housing was the largest contributor to the annual rise at 5.0%, driven by new dwellings at 5.7%, rents at 3.6% and electricity at 6.1%, the last reflecting the unwinding of Commonwealth and state electricity rebates.
Households are absorbing the difference. The Wage Price Index rose 0.8% in the June quarter and 3.2% over the year, down from 3.4% a year earlier and below headline inflation, and Cotality notes that real wages have now declined for four consecutive quarters. That squeeze makes deposit accumulation harder and is one reason consumer sentiment, while improved from its lows earlier in the year, remains deeply pessimistic.
Labour Market and Population
The labour market is loosening gradually. The unemployment rate reached 4.5% in July 2026, with 691,500 people unemployed, up from 4.4% and 686,800 in June. The employment-to-population ratio eased to 63.9%. Unemployment remains low by historical standards, which should limit the risk of widespread arrears or distressed selling, but a softer labour market will weigh further on housing demand.
Population growth has normalised from its post-pandemic surge, removing some of the demand-side support that underpinned housing conditions in recent years. Net overseas migration in the 2024-25 financial year eased to 306,000 people from 429,000 a year earlier, a fall of 28.7%.
Australia's sovereign credit standing is unchanged. Fitch Ratings affirmed Australia's 'AAA' rating with a stable outlook in October 2025, citing institutional strengths that support economic resilience to shocks.
The external environment remains the principal source of uncertainty. The continuing conflict in the Middle East has kept energy prices elevated and is the main reason inflation has proven stickier than expected, complicating the Reserve Bank's path and, through it, the outlook for housing.
Sources:
- Australian Bureau of Statistics (ABS)
- Total Value of Dwellings: abs.gov.au
- Value of Dwellings Falls 0.3%: abs.gov.au
- Lending Indicators: abs.gov.au
- New Home Loans Fall 5.4 Per Cent in June Quarter: abs.gov.au
- Building Approvals: abs.gov.au
- Dwelling Approvals Rise in June 2026: abs.gov.au
- Total Dwelling Approvals Fall 3.6% in July: abs.gov.au
- Australian National Accounts: abs.gov.au
- Australian Economy Grew 0.4% in the June Quarter: abs.gov.au
- Consumer Price Index: abs.gov.au
- Wage Price Index: abs.gov.au
- Labour Force: abs.gov.au
- Overseas Migration: abs.gov.au
- Reserve Bank of Australia (RBA)
- Cash Rate Target: rba.gov.au
- Lenders' Interest Rates: rba.gov.au
- Financial Aggregates: rba.gov.au
- Statement by the Monetary Policy Board, May 2026: rba.gov.au
- Measures of Consumer Price Inflation: rba.gov.au
- Australian Government Department of Treasury
- Delivering the National Housing Accord: treasury.gov.au
- First Home Buyers Program: firsthomebuyers.gov.au
- Guidance Note 6: foreigninvestment.gov.au
- National Housing Supply and Affordability Council (NHSAC)
- State of the Housing System 2025: nhsac.gov.au
- Cotality
- Cotality Indices: cotality.com
- Housing Downturn Spreads as 93% of Capital City Suburbs Record Winter Value Falls: cotality.com
- Rental Growth Accelerates Annually as Perth and Brisbane Close the Gap to Sydney: cotality.com
- Global Property Guide
- Gross Rental Yields in Australia: globalpropertyguide.com
- Commonwealth Bank
- 2026 Budget: Updated Housing Outlook: commbank.com.au
- William Buck
- Federal Budget Analysis 2026: Negative Gearing: williambuck.com
- Baker McKenzie
- Australia: Budget Bites, CGT Discount and Negative Gearing: bakermckenzie.com
- Fitch Ratings
- Fitch Affirms Australia at 'AAA'; Outlook Stable: fitchratings.com
- ABC News
- Government Breaks Promise with Restrictions to Negative Gearing: abc.net.au
- Housing Industry Association
- Building Approvals Slow in July: hia.com.au
- Roy Morgan
- Mortgage Stress at an 18-Year High: azurehomeloans.com.au